
Topping up your CPF is one of the more quietly powerful money moves available to Singapore Citizens and Permanent Residents. Done thoughtfully, a CPF top up can grow your future retirement payouts and, in many cases, lower the income tax you pay today. This guide explains how top-ups work, the main schemes involved, and the caps and catches worth knowing.
This is a general overview, not financial or tax advice. The schemes, limits and relief amounts are set by the authorities and change, so confirm the current rules with the CPF Board and the Inland Revenue Authority of Singapore (IRAS) before acting.
Why people top up
There are two main reasons. The first is to build a larger nest egg: money in your CPF accounts earns interest, and adding to it compounds your retirement savings. The second is tax: certain top-ups can qualify for income tax relief, so you strengthen your future while trimming your current tax bill. For many working residents, that combination is hard to ignore.
Topping up your Retirement or Special Account
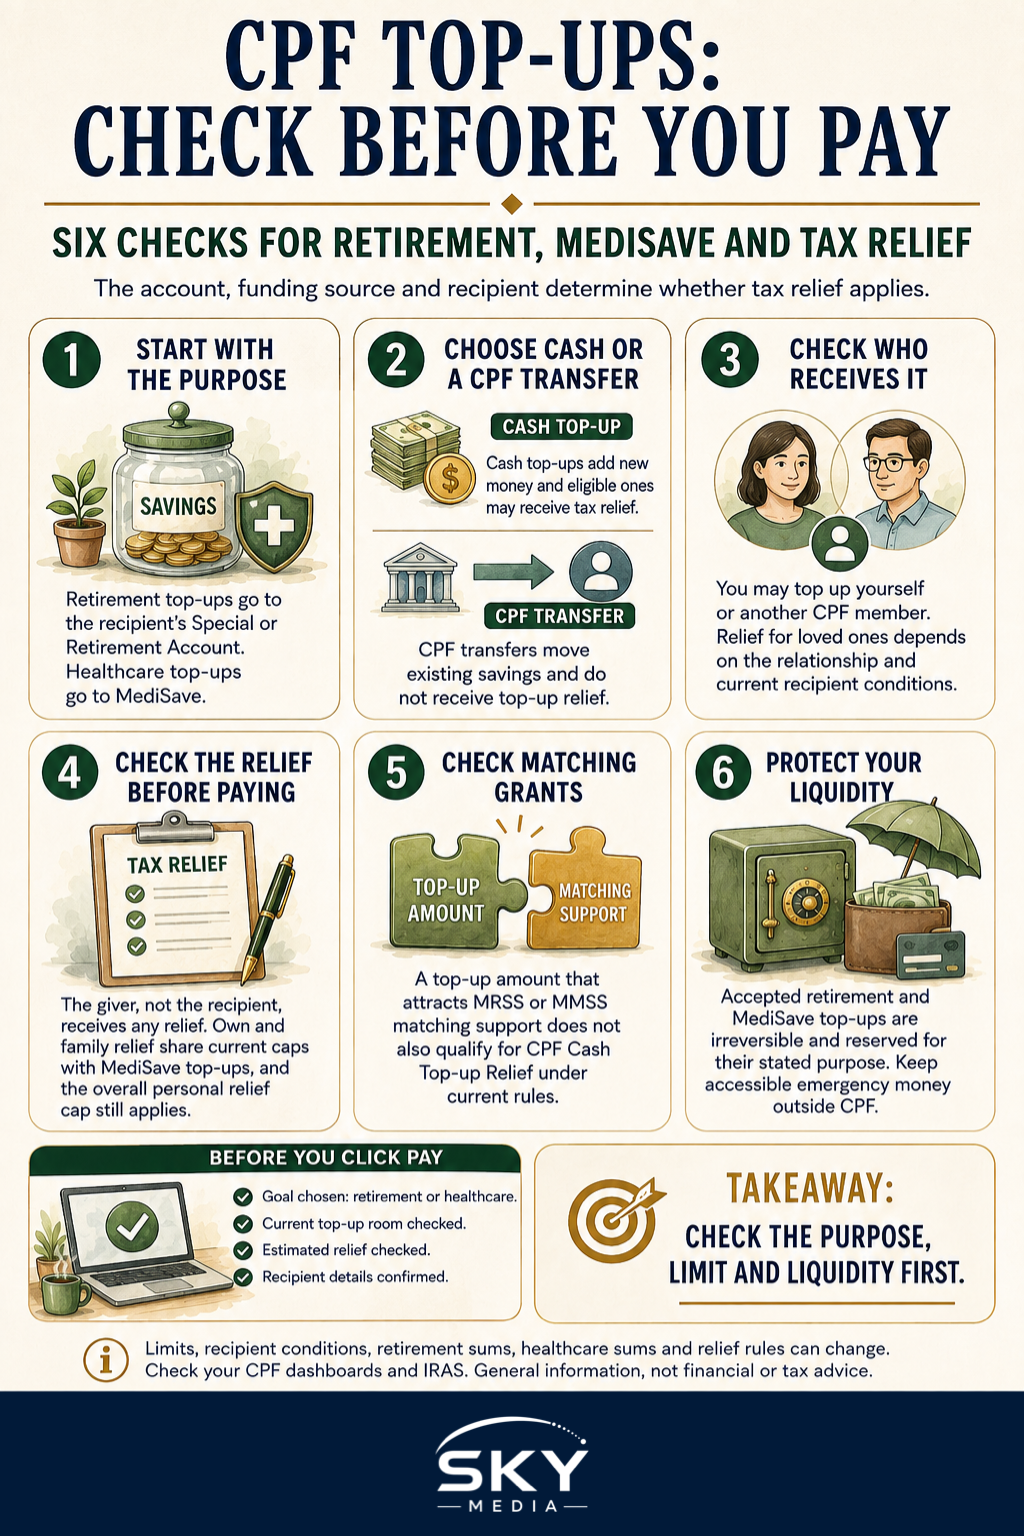
The main scheme for retirement top-ups lets you add cash to your own Special Account, or your Retirement Account once it is formed, to build towards a higher retirement sum. You can also top up the account of a loved one, such as a parent or spouse, which is a meaningful way to support their retirement.
Cash top-ups made under this scheme can attract income tax relief, both for topping up your own account and, separately, for topping up eligible family members. There are annual caps on how much relief you can claim, so plan your top-ups with those limits in mind.
MediSave top-ups
You can also top up your MediSave, the CPF account used for healthcare costs. Voluntary cash top-ups to MediSave can likewise qualify for tax relief, subject to limits and your account’s ceiling. This is useful if you want to bolster your healthcare buffer specifically rather than your retirement savings.
Cash versus transfers
There are two broad ways to boost your Special or Retirement Account.
- Cash top-ups use money from your bank account. These are the ones that can attract income tax relief.
- Transfers from your Ordinary Account move existing CPF savings from one account to another to earn higher interest. These do not attract tax relief, since no new money is entering CPF, but they can still raise your retirement savings.
Choosing between them depends on whether you have spare cash and whether tax relief matters to you this year.
Comparing the Main Top-Up Routes
Each route suits a different goal. This is a general comparison rather than a list of amounts, since the figures change each year.
- RSTU (SA or RA): boosts retirement savings. The money is locked for retirement and earns CPF interest rather than being invested.
- MediSave top-up: for healthcare and premiums. Funds are for approved medical use and earn CPF interest.
- SRS: retirement plus investing. You can invest it yourself, and withdrawals from the statutory age are taxed.
- Top-up for family: helps parents or a spouse. Their account rules apply and the money earns CPF interest.
Notice the trade-off: CPF routes give you certainty and a set interest rate but no investment control, while SRS gives you the flexibility to invest at the cost of market risk and different withdrawal rules.
The caps to keep in mind
| Consideration | Why it matters |
|---|---|
| Annual tax relief cap on top-ups | Limits how much relief you can claim in a year |
| Overall personal income tax relief cap | A total ceiling across all your reliefs |
| Account ceilings and the current retirement sum | Top-ups may be limited once a ceiling is reached |
| Timing within the calendar year | Top-ups usually count for the year they are made |
Because there is an overall cap on total personal income tax relief, very high earners may find additional top-ups no longer reduce their tax even if they still boost savings. Check where you stand before assuming a top-up will cut your bill.
A sensible way to approach it
- Decide your goal. Are you chasing higher retirement payouts, a healthcare buffer, or tax relief this year? Your goal points to the right scheme.
- Check the caps. Confirm the current relief limits and your account ceilings with the CPF Board and IRAS.
- Mind the timing. If tax relief is the aim, make cash top-ups before the year ends so they count for that tax year.
- Consider family. Topping up a parent’s or spouse’s account can support them and may bring you relief too.
- Do not overstretch. CPF savings are locked for their purpose, so only top up money you will not need in the near term.
How to Make a Top-Up
The process is largely digital and quick once you have Singpass, the national digital login.
- Log in to the CPF website or app with Singpass and go to the top-up section for the account you want.
- Choose the scheme, for example RSTU for retirement savings or a MediSave top-up, and whether it is for yourself or a family member.
- Check the cap the system shows you before paying, so your top-up stays within the limit that qualifies for relief.
- Pay by PayNow, GIRO or bank transfer as prompted.
- Keep the record. Relief is usually reflected automatically in your tax assessment, but keep the confirmation in case you need it.
For SRS, you open the account with a participating bank first, then contribute through the bank. To have a top-up count towards a given tax year, do it before the year-end cut-off the CPF Board publishes, since a late top-up counts for the following year.
Weigh the trade-off
The one real catch is liquidity. Money you put into CPF is committed to retirement or healthcare and cannot simply be withdrawn on a whim. That is a feature, not a bug, since it enforces discipline, but it means you should keep an accessible emergency fund outside CPF first. Once your short-term safety net is in place, regular top-ups can be a steady, low-effort way to build long-term security while enjoying a lighter tax bill along the way.
Things Newcomers Often Get Wrong
A few misunderstandings come up again and again:
- Assuming the money is accessible. CPF top-ups are for the long term and cannot simply be withdrawn when you change your mind.
- Topping up past the cap. Amounts above the relief cap will not earn extra relief, so check the limit first.
- Forgetting the overall relief ceiling. All your personal reliefs together are subject to a cap, so a top-up may give less benefit if you already claim many reliefs.
- Leaving it to the last day. Processing takes time, so top up well before the year-end deadline.
A simple way to picture the benefit
It helps to think of a top-up as doing two jobs at once. Imagine a working adult who has already built an emergency fund and has some spare cash at the end of the year. By making a cash top-up to a parent’s Retirement Account, that money starts earning CPF interest for the parent, supports their retirement directly, and may reduce the adult’s own income tax for that year, subject to the relief caps. One action, three outcomes.
Compare that with letting the same cash sit idle in a low-interest account, where it neither grows meaningfully nor trims any tax. The contrast is what makes top-ups popular among those who have the spare funds.
Who tends to benefit most
- Steady earners with spare cash who want to lower their tax bill while building savings.
- Adult children wanting to support ageing parents in a structured, lasting way.
- Anyone chasing a higher retirement sum to lift their eventual CPF LIFE payouts.
Those who should pause are people without an emergency buffer, or very high earners who have already hit the overall personal income tax relief cap, since further top-ups would still grow savings but no longer cut their tax. As always, confirm your own position before committing.
Explore more: Your CPF accounts explained · CPF LIFE explained · Filing your income tax in Singapore