
Investing can sound intimidating, full of jargon and charts that seem designed to keep ordinary people out. It does not have to be that way. This guide to investing for beginners in Singapore explains the ideas that actually matter, in plain language, so you can decide whether and how investing fits your life. Before we start, one honest line that runs through everything below: all investing carries risk, including the risk of losing money, and nothing here is a promise of returns. This is general information, not financial advice, so weigh it against your own situation and, where relevant, speak with a licensed financial adviser or the MAS-regulated provider before you commit.
Why People Invest in the First Place
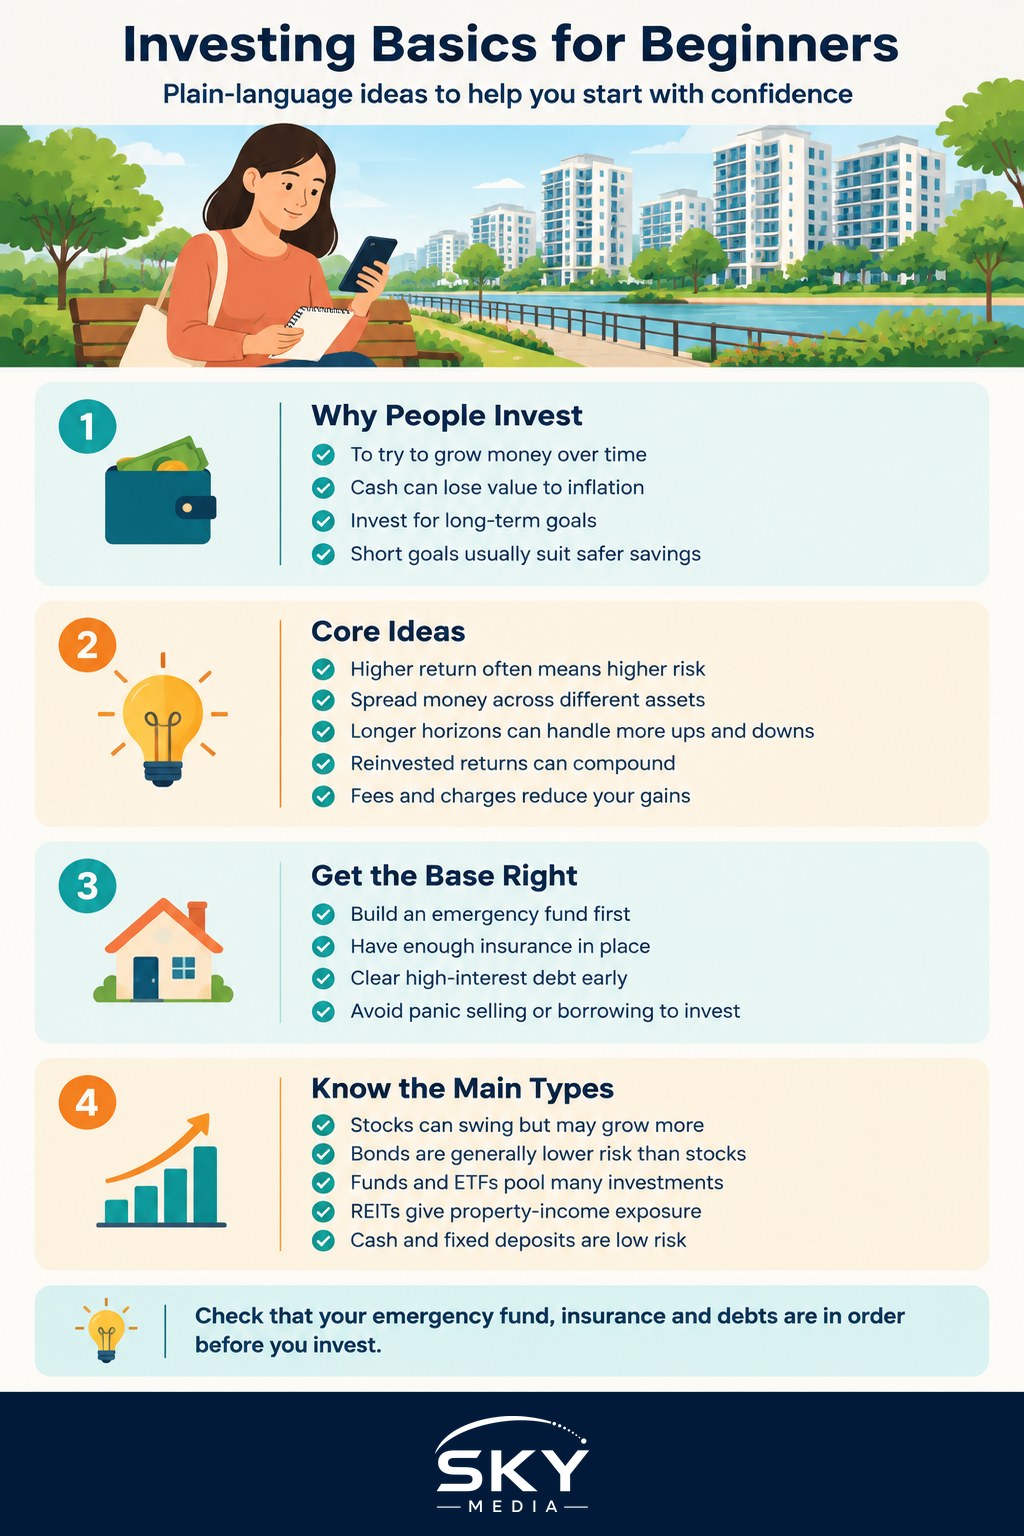
The simplest reason to invest is that money left idle tends to lose value over time. Prices generally rise year after year, a process called inflation, so a fixed sum of cash buys a little less each year. Keeping some money in a savings account is sensible and necessary, but over long periods cash alone can struggle to keep pace with rising costs. Investing is one way people try to grow their money faster than inflation, though it comes with the trade-off of uncertainty and possible loss.
The second reason is long-term goals. A retirement decades away, a child’s future education, or simply building wealth over a working lifetime are all goals measured in years rather than months. Time is the ingredient that makes investing worthwhile, because it gives your money room to grow and to recover from the ups and downs that come with markets. If your goal is only a year or two away, investing is usually the wrong tool, and a safer home for the money makes more sense.
The Core Concepts Worth Understanding
A handful of ideas explain most of what beginners need. Learn these and the rest becomes far easier to follow.
- Risk versus return. In general, investments that offer higher potential returns also carry higher risk, meaning a wider range of outcomes including losses. There is no free lunch where high returns come with no risk, and anything sold that way deserves deep suspicion.
- Diversification. Spreading money across many investments, rather than putting it all in one, reduces the damage if any single one performs badly. The old phrase about not putting all your eggs in one basket captures it well.
- Time horizon. How long before you need the money shapes what is suitable. Longer horizons can generally tolerate more short-term ups and downs; shorter horizons cannot.
- Compounding. When returns are reinvested, they can, over long periods, generate returns of their own. This snowball effect rewards patience, though it is never guaranteed and works in reverse when values fall.
- Costs and fees. Every dollar paid in fees, charges, or spreads is a dollar not working for you. Small percentages add up meaningfully over decades, so keeping costs low matters.
- Dollar-cost averaging. Investing a fixed amount at regular intervals, rather than a lump sum all at once, spreads your entry across different prices and removes the pressure to guess the perfect moment.
Get the Foundations Right Before You Invest
Investing sits near the top of a financial house, not at its foundation. Building the base first protects you from being forced to sell investments at a bad time. Three foundations usually come before putting money into markets.
First, an emergency fund of readily accessible savings, so an unexpected bill or a job loss does not force you to touch your investments. Second, adequate insurance for the big risks, such as health and, if others depend on you, income and life cover, so one event does not undo years of saving. Third, clearing high-interest debt, especially credit card balances, because the interest charged there often outweighs any realistic investment return. Paying that down is one of the surest financial wins available.
Only once these are in place does regular investing tend to make sense. Rushing past them is how people end up selling in a panic or borrowing to invest, both of which usually end badly.
Common Asset Types at a High Level
Beginners in Singapore will meet a few broad categories. This is a general map, not a recommendation to buy any of them, and each behaves differently in good times and bad.
| Asset type | General risk and return character |
|---|---|
| Stocks (shares) | Higher risk, potential for higher long-term growth, values can swing sharply |
| Bonds and Singapore Savings Bonds | Generally lower risk than stocks, more modest returns, still not risk-free |
| Funds and ETFs | Pooled, diversified baskets; risk depends on what they hold |
| REITs (property trusts) | Exposure to property income; can be volatile and sensitive to rates |
| Cash and fixed deposits | Lowest risk, low return, main risk is losing ground to inflation |
Stocks represent part-ownership of a company and can grow or fall in value. Bonds are effectively loans to a government or company that pay interest, with Singapore Savings Bonds being a government-backed option many beginners read about. Funds and exchange-traded funds (ETFs) pool many investments into one product, offering instant diversification, though fees and holdings vary widely. REITs let you invest in property-related income without buying a building. The right mix, if any, depends entirely on your goals, horizon, and comfort with risk, which is a personal decision.
Staying Safe and Avoiding Get-Rich-Quick Schemes
In Singapore, capital-market products and the firms that sell them are regulated by the Monetary Authority of Singapore (MAS). Dealing with MAS-regulated providers does not remove risk, but it means the firm operates under supervision and rules. Before putting money anywhere, it is worth checking that the provider is properly licensed, a step MAS and MoneySense both encourage.
Be deeply wary of anything promising high or guaranteed returns with little or no risk, pressure to act fast, or returns that sound too good to be true. Past performance is never a reliable guide to future returns, and no legitimate investment guarantees profit. Schemes built on hype, secrecy, or urgency are classic warning signs of scams. When something feels off, slow down, verify independently, and remember that missing an opportunity is far cheaper than losing your capital. MoneySense, Singapore’s national financial-education programme, is a trustworthy, non-commercial place to keep learning.
Explore more
When you are ready to move from concepts to action, our guide to how to start investing in Singapore walks through the practical first steps at a beginner’s pace. It also helps to know what you are investing for, so setting financial goals in Singapore is a useful companion that turns these basics into a plan you can actually follow.
Frequently Asked Questions
How much money do I need to start investing? You do not need a large sum, since many platforms and products let you begin with a modest amount, though minimums vary. What matters more is that the money is not needed soon and that your emergency fund is in place. Check the minimum amounts and fees with each provider before you commit.
Should I pay off debt or start investing first? If you carry high-interest debt such as unpaid card balances, clearing it is usually the safer first move, because interest on it can outweigh likely investment gains. Investing returns are uncertain, while debt costs are certain. Once the costly debts are gone and a buffer exists, investing becomes easier to consider.
What is the difference between saving and investing? Saving keeps money safe and easy to reach, usually in a bank account, with little risk to your capital. Investing puts money into assets that can grow but can also fall in value. Saving suits short-term needs and emergencies, while investing suits long-term goals where you can ride out ups and downs.
What are the most common mistakes new investors make? Typical mistakes include putting everything into one investment, chasing hot tips, trying to time the market, and panicking when prices fall. Ignoring fees is another. Having a clear plan, spreading your money and staying patient helps you avoid most of them, though no approach removes risk entirely.
Official sources: MoneySense
Further reading: Investing in Silver in Singapore: Bars, Coins and Storage · How to Invest a Small Amount of Money · Halal and Shariah Investing