

Many Singapore drivers head across the Causeway or Second Link for food, shopping, family visits or longer holidays up the peninsula. Before you go, it pays to understand exactly what your policy does in Malaysia, and whether a Malaysia car insurance add on, extension or rider is worth having. Insurers word these features differently, and the cover that feels generous on a Singapore road can look quite different once you are a few hundred kilometres north.
This guide does not walk through the whole road trip. It focuses on one task: reading and comparing the optional cross-border cover on your motor policy so you can decide what you actually need. It is general information only. Your policy wording and your insurer are the final word, and terms change, so always confirm current details directly with them.
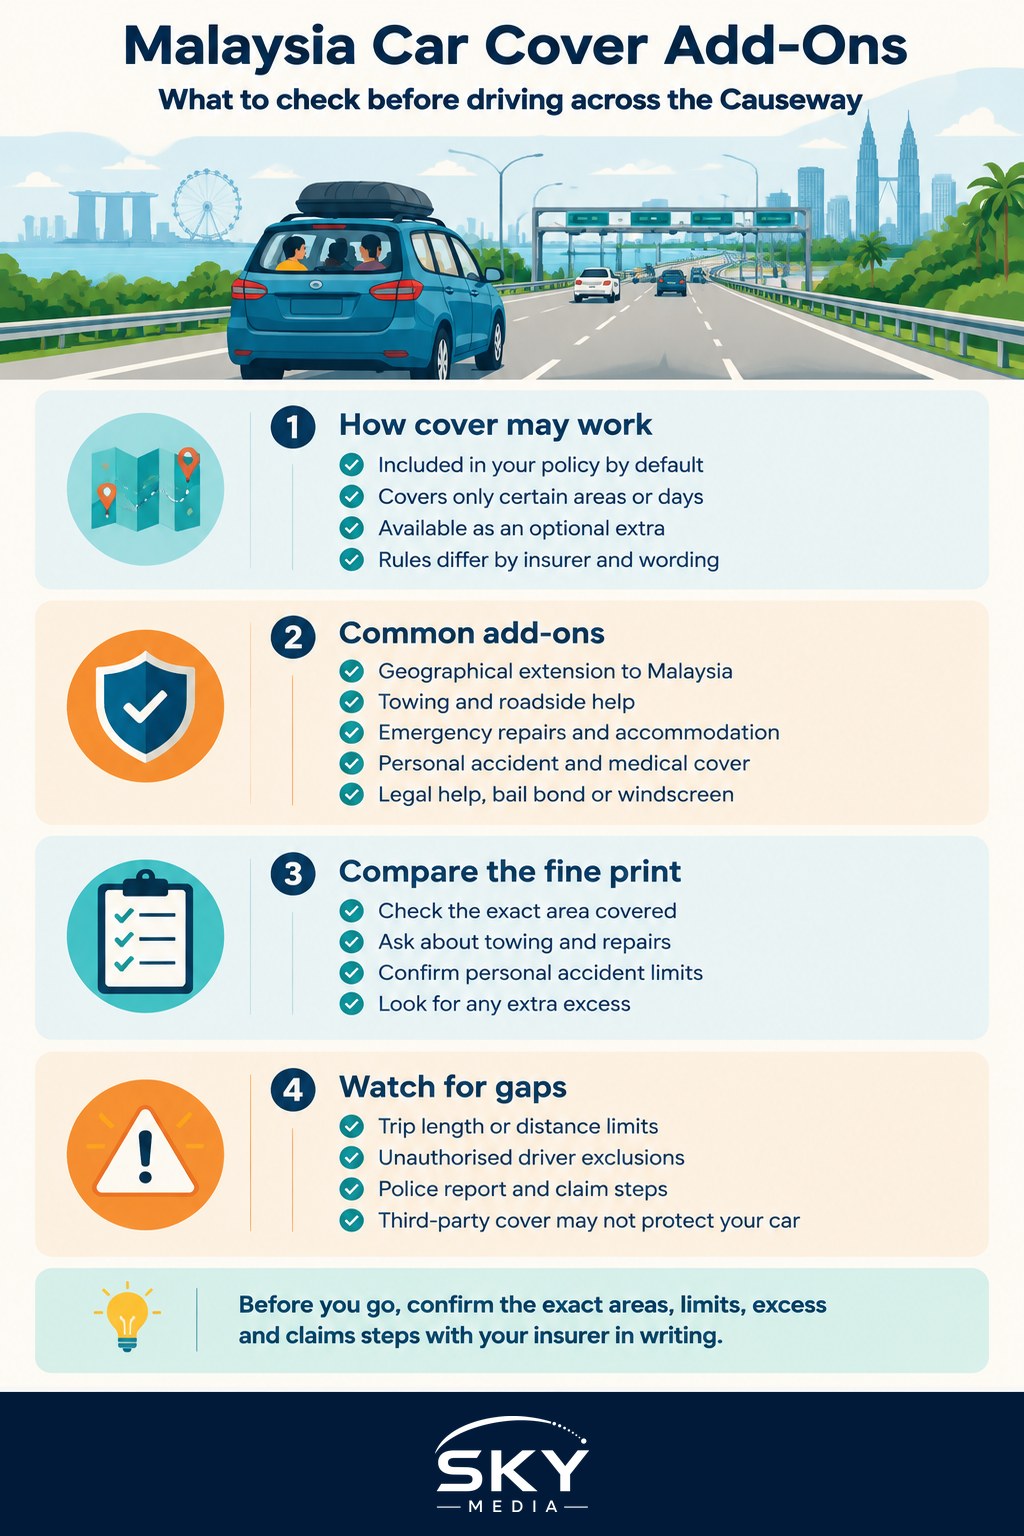
How Cross-Border Cover Usually Works
Singapore motor policies are written for Singapore roads first. Cover in Malaysia is commonly handled in one of three ways:
- Included as standard. Some policies extend cover to West Malaysia, and sometimes southern Thailand, automatically. Look for a section titled “geographical area” or “territorial limits”.
- Included with limits. The policy may cover Malaysia but only within a certain distance from Singapore, or for a set number of days per trip, or with reduced benefits.
- Available as an optional add-on. You pay extra, or opt in, to extend cover or enhance specific benefits while you are in Malaysia.
Whichever applies, the key point is that “covered in Malaysia” rarely means “covered exactly the same as at home”. The differences sit in the details below.
Malaysia also has its own compulsory insurance requirements for foreign vehicles entering the country. Check the current rules with the relevant Malaysian authorities and your insurer, since requirements and accepted documents can change. If you are new to Singapore motor insurance in general, start with our overview of car insurance in Singapore.
Common Malaysia Add-Ons and What They Typically Mean
Different insurers bundle and name these differently, so treat the list below as a guide to what to look for rather than a description of any specific product.
- Geographical extension. Extends your existing cover to Malaysia, possibly beyond the default distance limit.
- Towing and roadside assistance in Malaysia. Covers breakdowns or accident recovery across the border. Check whether towing back to Singapore is included, or only to the nearest workshop.
- Emergency repairs and accommodation. Some riders help with costs if your car is undriveable and you are stranded overnight.
- Personal accident extension. Increases or extends personal accident benefits for the driver and passengers while abroad.
- Medical expenses. Covers treatment costs for occupants after an accident in Malaysia, up to a stated limit.
- Legal assistance or bail bond. Supports you if you face legal proceedings after an accident overseas.
- Windscreen cover. Confirms whether windscreen claims made in Malaysia are treated the same way as local ones.
Comparing Add-On Options Side by Side
When you have two or three quotes or policy documents open, it helps to line up the same questions for each. Here is one way to frame the comparison.
| Feature to check | What a basic extension may offer | What an enhanced add-on may offer | Question to ask your insurer |
|---|---|---|---|
| Area covered | Part of West Malaysia within a set distance | Wider area, possibly including southern Thailand | Exactly which areas and distance limits apply? |
| Towing | Limited or none outside Singapore | Towing to a nominated workshop or back to Singapore | Who arranges the tow and up to what limit? |
| Repairs after an accident | May require repair in Singapore | Option for emergency repairs locally | Must I get approval before local repairs? |
| Personal accident and medical | Standard policy limits | Higher limits for overseas incidents | Are passengers covered, and up to how much? |
| Excess | Same as or higher than in Singapore | May be reduced or unchanged | Is there an additional excess for claims in Malaysia? |
Your insurer can confirm the actual figures and limits. Do not assume a feature exists because a competitor offers it.
Gaps and Exclusions to Watch
The most painful surprises are usually in the exclusions section, not the benefits list. Read these carefully:
- Distance and duration limits. Long trips up north may fall outside the covered area or time window.
- Unauthorised drivers. If a friend or relative drives in Malaysia and is not a named or authorised driver, a claim may be rejected or attract a higher excess.
- Claims handling process. Find out whether you must report the accident to the Malaysian police within a set time, and what documents you need to bring back.
- Repairs and approval. Some policies require the car to be brought back to an approved Singapore workshop. Others allow repairs in Malaysia only with prior approval.
- Higher or additional excess. The amount you pay yourself on each claim may differ for overseas incidents. Our guide to understanding your insurance excess explains how this works.
- Third-party only policies. If you hold third-party or third-party fire and theft cover, damage to your own car in Malaysia may not be covered at all, whatever add-ons you pick. See comprehensive vs third-party car insurance for the difference.
Deciding Whether You Need an Add-On
A quick self-check can help you decide.
- How far do you usually go? If your trips are mainly to Johor Bahru, standard cover may be enough. If you drive to Melaka, Kuala Lumpur, Penang or beyond, check distance limits closely.
- How often do you go? Frequent weekend drivers may benefit more from a permanent extension than occasional travellers.
- Who drives? If you share driving with family or friends, check named driver rules first.
- How old is your car, and how would you get it home? Older cars may be more likely to break down, which makes towing and recovery cover more valuable.
- What does your travel insurance already cover? Some travel policies include certain personal accident or medical benefits. Avoid paying twice, but also check for gaps between the two.
Practical Steps Before You Drive Across
Once you have chosen your cover, a few simple habits help if something goes wrong.
- Save your insurer’s 24-hour hotline and any overseas assistance number on your phone and on paper in the glovebox.
- Keep a copy of your certificate of insurance, and any document required for entry into Malaysia, in the car.
- Know what to photograph after an accident: vehicles, number plates, road layout, damage and the other driver’s details.
- Understand how to make a police report in Malaysia if your policy requires one.
- Read our guide to car insurance claims explained so you know what your insurer will likely ask for when you return.
A few minutes spent on the policy wording before you leave is far less stressful than discovering a gap at a roadside in another country. If anything is unclear, ask your insurer or agent to confirm it in writing.
Frequently Asked Questions
What if a friend who is not a named driver drives my car in Malaysia? A claim may be rejected or attract a higher excess if the driver is not named or authorised under your policy. Check the named driver rules with your insurer before lending the car, and get any change confirmed in writing.
Does third-party insurance cover damage to my own car in Malaysia? Probably not. With third-party or third-party fire and theft cover, damage to your own car in Malaysia may not be covered at all, whatever add-ons you choose. Comprehensive cover is where cross-border add-ons make a real difference.
Will my Singapore insurer tow my car back from Malaysia after a breakdown? It depends on the policy. Some towing add-ons cover only the nearest workshop, while others include towing back to Singapore, and limits apply. Ask your insurer who arranges the tow and up to what limit before you cross.
Should I buy a Malaysia add-on if I only drive to Johor Bahru? Standard cover may be enough for short trips, but check the distance limits and what your policy says about territorial limits. If you drive to Melaka, Kuala Lumpur or Penang, read the limits closely and consider an add-on.
Do I need to make a police report if I have an accident in Malaysia? Your policy may require it, often within a set time, so ask your insurer before you go. Photograph the vehicles, number plates, road layout and damage, note the other driver’s details, and keep your insurer’s 24-hour hotline handy.