
Deciding how to turn a lifetime of savings into a steady income is one of the biggest questions in retirement, and private annuities vs CPF LIFE sits right at the heart of it. Both are forms of longevity insurance, meaning they are designed to keep paying you for as long as you live so you do not outlast your money. They work in different ways, though, and understanding how each one functions helps you ask the right questions. This guide explains the mechanics, not what to buy. It is general information, not financial advice, so speak to a licensed financial adviser and check current details with the CPF Board and MAS before deciding.
What Longevity Insurance Actually Means
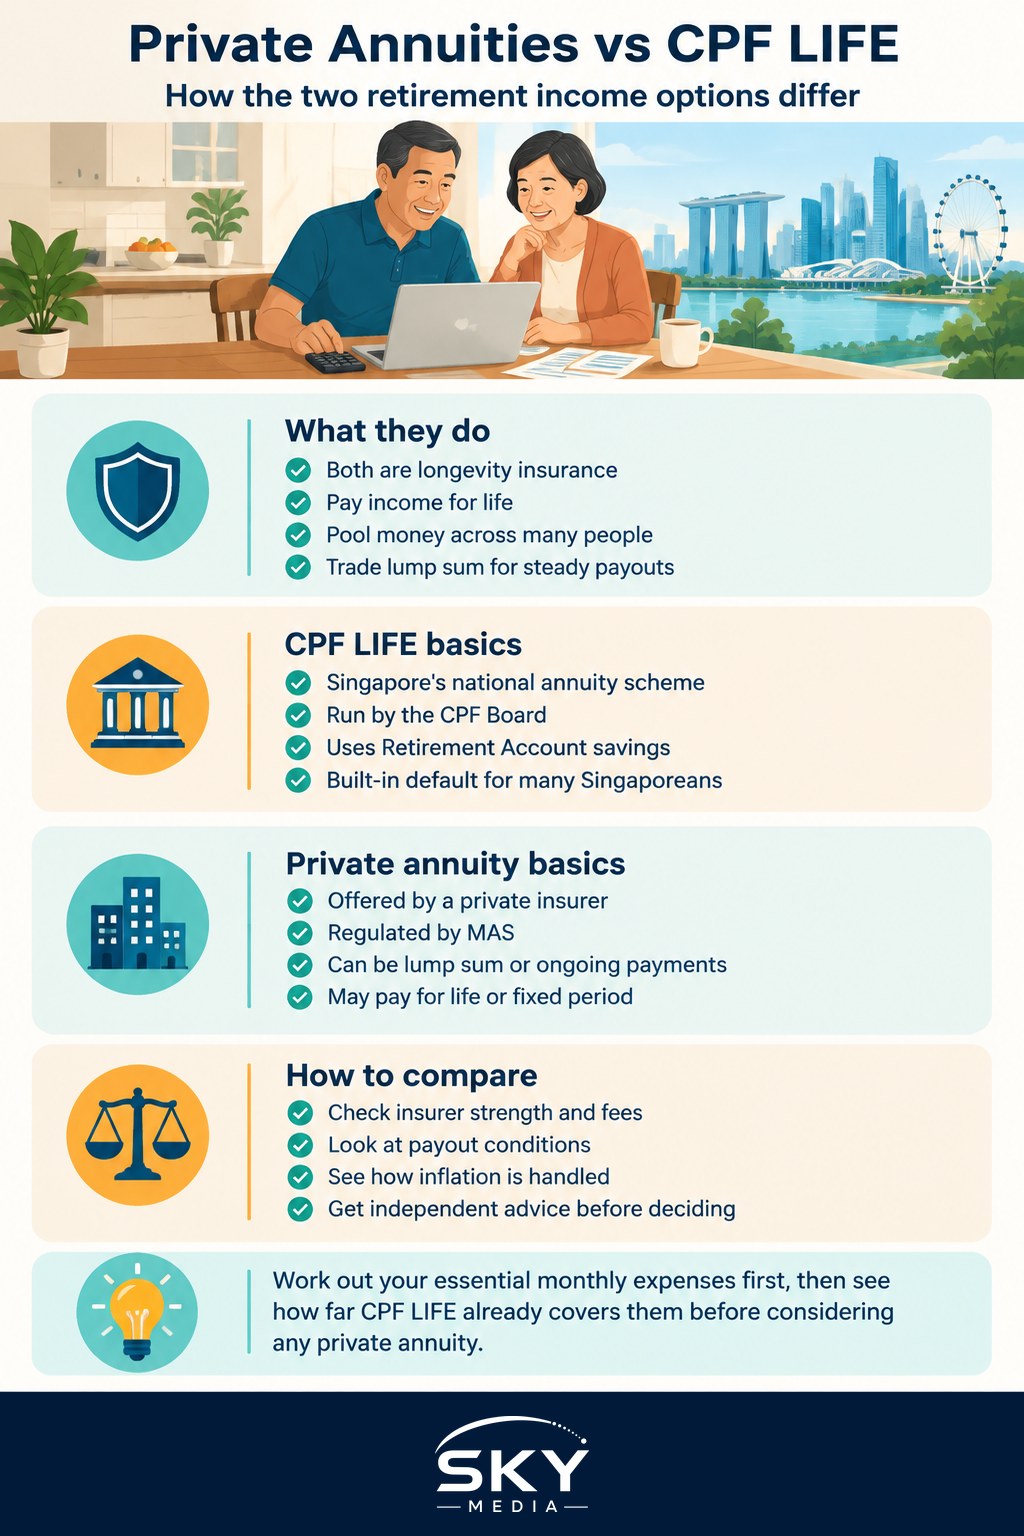
A long retirement brings a genuine risk that many people underestimate: the risk of living longer than expected and running low on savings. Longevity insurance addresses this by pooling money across many people. Those who live longer keep receiving payouts funded, in part, by the pool. In exchange for giving up access to a lump sum, you receive the reassurance of income that does not stop.
Both CPF LIFE and private annuities use this pooling idea. The trade-off in both cases is similar: you commit a sum of money now, and in return you receive a stream of payments for life rather than keeping the capital to spend or leave behind. That trade-off is the core of the decision, and it is why neither option should be judged purely on the size of the payout.
How CPF LIFE Works
CPF LIFE is Singapore’s national annuity scheme, run by the CPF Board. When you reach the relevant age, the savings set aside in your Retirement Account are used to provide monthly payouts for the rest of your life. The scheme is built into the CPF system, so for most Singaporeans it is the default foundation of retirement income.
A few plain features stand out. Payouts continue for life, which directly tackles longevity risk. The scheme offers different plan options that balance the size of payouts against how much is left for beneficiaries, and the details are set and periodically revised by the CPF Board. Because it is a national scheme, it is not sold by agents and carries no commission. Exact payout levels, ages and options change over time, so always check the current position on the CPF Board website rather than relying on older figures.
How Private Annuities Work
A private annuity is a product offered by an insurer, regulated in Singapore by the Monetary Authority of Singapore (MAS). You pay the insurer a sum, either as a lump sum or over time, and in return the insurer promises a stream of income, which may be for a fixed period or for life depending on the product.
Private annuities can add flexibility that a national scheme may not, such as different start dates, payout structures or features tailored to particular needs. That flexibility comes with things to scrutinise: the financial strength of the insurer, the fees and charges built into the product, any conditions on payouts, and whether the income keeps pace with inflation. Because these are commercial products with many variations, it is essential to read the details carefully and get independent advice rather than relying on a sales illustration. No product is risk-free, and figures in any illustration are not guarantees.
Comparing the Two Side by Side
The clearest way to see the differences is to line them up. Remember that specifics change and vary by product, so use this as a way to frame questions, not as current fact.
| Feature | CPF LIFE | Private annuity |
|---|---|---|
| Provider | CPF Board, national scheme | Private insurer, regulated by MAS |
| Main purpose | Lifelong baseline retirement income | Additional or tailored lifelong or fixed income |
| Flexibility | Set options within the scheme | Wider range of structures, varies by product |
| Costs | No commission | May include fees and charges, read the details |
| Best used for | Core, dependable foundation | Supplementing or customising once the core is set |
For many people the two are not rivals so much as layers: CPF LIFE forms the dependable base, and a private annuity, if it suits, sits on top to fill a specific gap.
Questions to Ask Before You Decide
Rather than reaching for a product, start with your own needs.
- Work out what your essential monthly expenses are, so you know how much guaranteed income you actually need.
- See how far your CPF LIFE payouts already go towards covering those essentials before considering anything extra.
- If a gap remains, ask whether an annuity, more savings, or another approach is the most sensible way to fill it.
- For any private product, examine the insurer’s standing, the fees, the payout conditions and how inflation is handled.
- Get independent advice from a licensed adviser, and never commit to something you do not fully understand.
The order matters: secure your dependable base first, then decide whether a supplement genuinely adds value for you.
It is also worth being clear-eyed about the emotional side of the decision. Committing a lump sum in exchange for income you cannot later reclaim can feel uncomfortable, and it is natural to worry about handing over control of your money. That discomfort is exactly why longevity insurance is valuable: it protects you from a risk that is easy to underestimate when you are healthy and the future feels far away. Balance that against the desire to keep capital accessible or to leave a larger inheritance, and be honest about which matters more to you. There is no universally right answer, only the one that fits your circumstances, your family and your peace of mind.
Making the Decision in Context
Neither option exists in a vacuum. How you weigh private annuities vs CPF LIFE depends on your other savings, your health, whether you have dependants, and how much you value leaving a legacy versus maximising income. It also connects to how you draw down everything else. Reading about the retirement drawdown order and building a retirement income portfolio will help you see where lifelong income fits alongside your investments and cash.
The honest bottom line is that both CPF LIFE and private annuities exist to solve the same worry: outliving your savings. CPF LIFE gives most Singaporeans a solid national foundation, and a private annuity may or may not add worthwhile flexibility on top. Understand the mechanics, get independent advice, and confirm every current detail with the CPF Board and MAS before you decide.
Related across Sky Media: CPF LIFE Explained in Singapore · CPF LIFE Payouts, Explained
Official sources: CPF Board
Further reading: Private Annuities and Retirement Income