

As Additional Buyer’s Stamp Duty has grown, more couples have looked at property decoupling Singapore as a way to free up one partner’s name so they can buy a second home without the second-property surcharge. Decoupling can work, but it carries real costs and risks that are easy to underestimate. This guide explains how it works, when it might make sense, and what to weigh before you go ahead. It is general information only, not personalised tax, legal or financial advice.
What Decoupling Actually Means
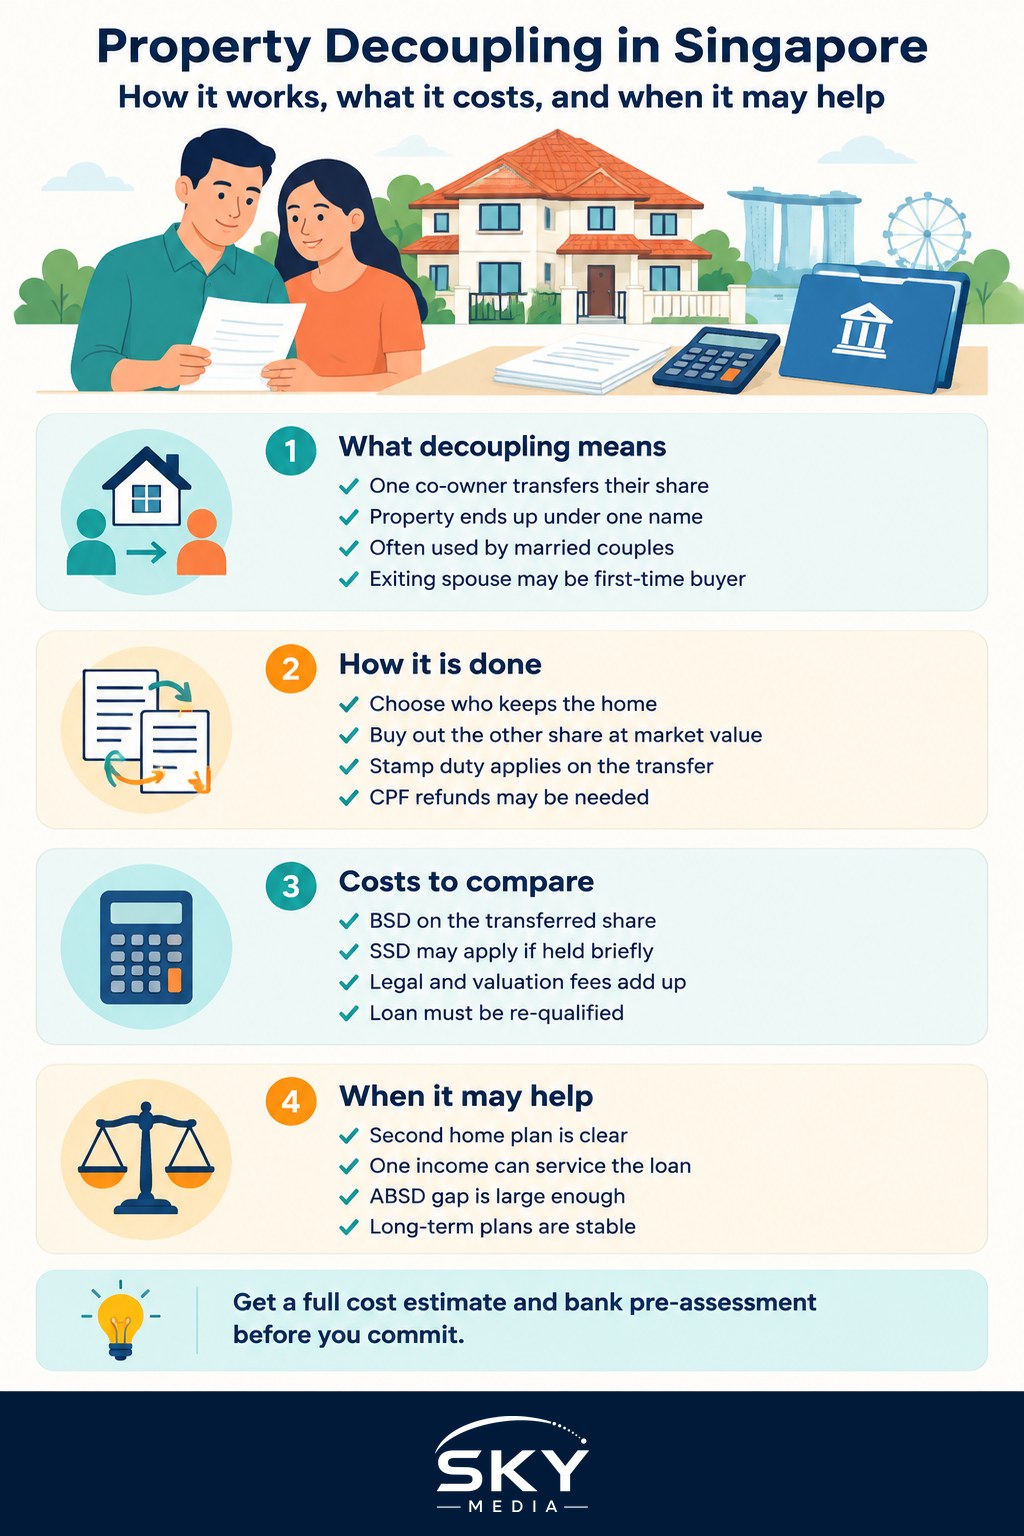
Decoupling is the process where one co-owner of a property transfers their share to the other co-owner, so that afterwards the property is held by a single owner. Most commonly, a married couple who jointly own their first home arrange for one spouse to buy out the other’s share. The spouse who exits then owns no residential property, at least on paper, and may be treated as a first-time buyer when purchasing the next home.
The appeal is straightforward. If ABSD steps up sharply on a second property, having one clean name can, in the right situation, mean the next purchase attracts a much lower ABSD position than buying it as an existing property owner. That said, decoupling is a transfer of real estate between two people, so it triggers its own duties and costs, and those can offset or even exceed the ABSD you hoped to save.
How the Process Works
At a high level, decoupling follows a familiar conveyancing path, just between two people who already own the home together.
- The couple decides which spouse will retain the property and which will transfer out their share.
- The retaining spouse buys the exiting spouse’s share at market value, usually with a fresh valuation to support the price.
- Stamp duty is assessed on the transferred share, and legal and financing steps follow, including refinancing if there is an outstanding loan.
- CPF funds used by the exiting spouse generally have to be refunded to their CPF account with accrued interest, which affects the cash that changes hands.
- Once complete, the property sits in one name, and the other spouse is positioned to buy separately.
Because a mortgage is usually involved, the retaining spouse must qualify to hold the loan on their income alone. Lenders will reassess affordability, and this is where many plans stall.
Costs and Trade-Offs to Weigh
Decoupling is only worthwhile if the savings clearly beat the costs, and the costs are more than just legal fees. The table below lays out the main moving parts so you can compare them for your own case. It does not show figures, which depend on your property value, loan and current rules, so confirm those with the relevant authorities and your advisers.
| Factor | Why it matters | Where to confirm |
|---|---|---|
| Buyer’s Stamp Duty on the transferred share | The retaining spouse pays BSD on the share bought over | IRAS |
| Seller’s Stamp Duty exposure | May apply if the property was held for a short period | IRAS |
| CPF refund with accrued interest | Reduces cash proceeds and can strain the retaining owner | CPF Board |
| Loan re-qualification | Retaining spouse must service the loan on one income | Your bank |
| Legal and valuation fees | Two conveyancing matters and a valuation add up | Your lawyer |
When you total these, the exercise sometimes saves less than expected, especially on lower-value homes or where a fresh loan is hard to secure. The savings tend to be larger where the ABSD gap on the next purchase is wide and the home’s value makes the transfer duties proportionally small.
The CPF side of the cost
If CPF savings were used to buy the home, the exiting owner will generally need to refund the CPF amount used together with the accrued interest back into their own CPF account. That accrued interest grows over time, so this can be substantial and should be included in your calculations alongside stamp duty, legal fees and any refinancing costs.
When you compare the transfer costs and CPF refund against the hoped-for saving on the next purchase, the maths does not always favour decoupling. Sometimes it does, sometimes it clearly does not, and it depends on your numbers and the rules in force at the time.
When Decoupling May or May Not Help
Decoupling is a tool, not a default. It tends to make more sense when several conditions line up, and much less sense when they do not.
It may help when:
- The couple genuinely intends to buy a second property and hold both for the medium term.
- One spouse can comfortably service the existing home loan alone after the buyout.
- The value of the second purchase, and the ABSD it would otherwise attract, is high enough that the saving clearly beats the transfer costs.
It may not help when:
- The retaining spouse cannot re-qualify for the loan without the other’s income, which can force a sale.
- The property was bought recently and Seller’s Stamp Duty could apply to the transfer.
- The CPF refund leaves the household short of cash for the next purchase.
- The couple’s plans might change, since unwinding the arrangement later is costly.
There are also non-financial angles. Decoupling changes legal ownership, which affects what each spouse owns outright, how the asset is dealt with in estate planning, and how things would be divided if the relationship broke down. Those are reasons to involve a lawyer, not just a mortgage broker.
Doing It Properly and Legally
Decoupling is legitimate when it reflects a real change in ownership carried out under the normal rules. What you must not do is dress up a transaction to obtain a tax advantage that the arrangement does not truly support, as the authorities can look through artificial steps. Keep the transfer at genuine market value, document it properly, and make sure each stage stands on its own.
Practical steps before committing:
- Get a written estimate of every cost, including BSD, any SSD, CPF refunds, legal and valuation fees, so you can compare the full outlay against the ABSD you hope to avoid.
- Ask your bank to pre-assess whether the retaining spouse qualifies for the loan alone.
- Confirm current stamp duty treatment and any holding-period rules with IRAS, and CPF refund rules with the CPF Board.
- Have a conveyancing lawyer review the plan end to end, including estate and ownership implications.
- Sanity-check the whole thing against your longer-term plans, since a saving today is not worth much if you are forced to unwind it in a year.
Done with clear eyes and good advice, decoupling can be a sound way to manage a genuine upgrade. Done on a rough guess, it can cost more than the surcharge it was meant to avoid.
Get professional advice before taking any step
Decoupling touches ownership law, stamp duty, CPF and your home loan all at once, so it is not a do-it-yourself decision. Before acting, engage a conveyancing lawyer to handle the transfer and advise on the legal implications, and speak to a qualified financial adviser and your bank about the loan and the overall financial picture.
It also makes sense to confirm the current stamp duty position directly with IRAS and the CPF treatment with the CPF Board. Treat any guide as a starting point for your questions, then let the right professionals run the actual numbers for your situation before you decide.
Explore more
If you are weighing a second home, start with our guide to buying a second property in Singapore and our overview of stamp duty, BSD and ABSD. Since timing and holding periods matter here, also read about Seller’s Stamp Duty in Singapore and how ABSD scenarios and remission could change your numbers.
Frequently Asked Questions
Can HDB flat owners decouple to buy a private property? HDB flats come with their own ownership rules, and transferring a share between spouses is only allowed in limited circumstances set by HDB. Decoupling is therefore mostly discussed for private property, so check HDB’s rules on ownership changes before assuming it is possible for your flat.
How long does the decoupling process usually take? It often takes a few months from start to finish, because it involves a valuation, legal documents, stamp duty and frequently refinancing the home loan. Bank approval for the retaining spouse is usually the slowest step, so start that conversation early.
What happens to decoupled property if the couple later divorces? Once decoupled, the home is legally owned by one spouse, but the court can still treat it as a matrimonial asset when dividing property in a divorce. The paper title does not settle the outcome on its own, so a family lawyer should explain how your arrangement may be treated.
Can unmarried co-owners such as siblings decouple a property? Yes, any co-owners can transfer a share between themselves, so the process is not limited to spouses. The same stamp duty, CPF refund and loan qualification issues apply, and remission routes designed for married couples will not be available, so cost the move carefully.
Official sources: IRAS