
Welcoming a child is a joyful, life-changing event, and it helps to feel financially ready for it. Understanding the financial side of a baby Singapore parents plan for lets you focus on the happy parts rather than worrying about the sums. This is general information, not financial or legal advice, and every family is different, so consider a MAS-licensed adviser and always check current official details, which change from time to time.
Let us walk through the main costs, the support that exists, and the practical steps that give you peace of mind before and after your little one arrives.
The one-off costs
Some costs come once, mostly around the birth and the early setup of your home for a baby.
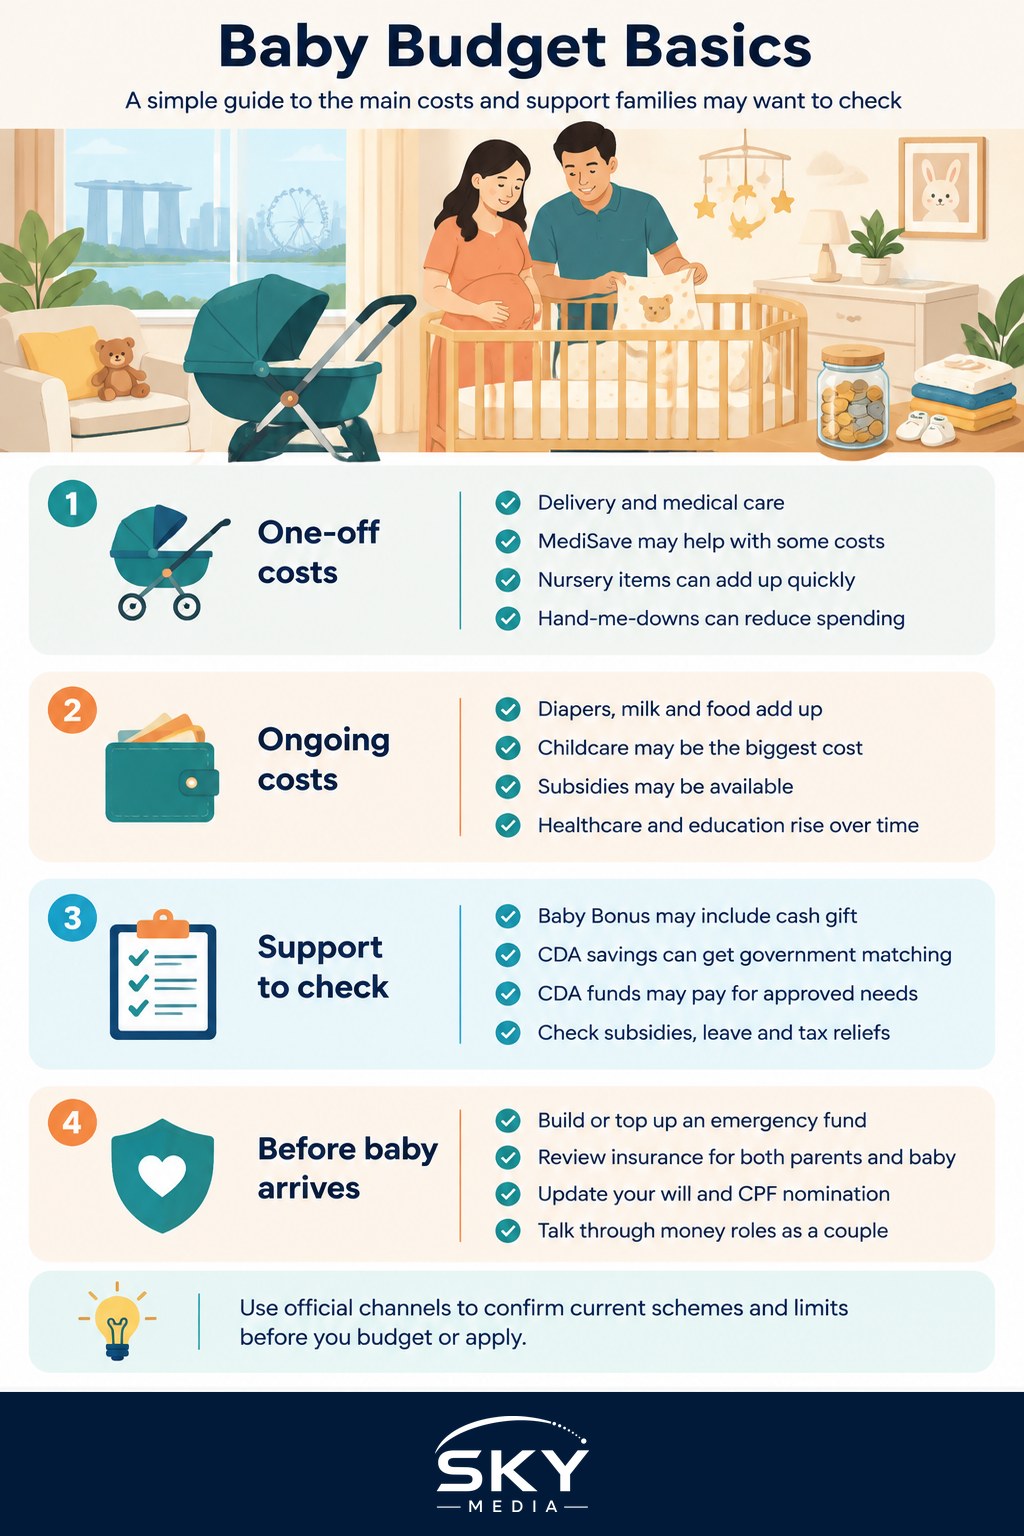
Delivery and medical care are usually the largest one-off expenses. Costs vary widely depending on the type of ward, the hospital and the kind of delivery. The good news is that MediSave can be used to help with delivery and pre-delivery expenses, within limits set by the authorities. Check the current withdrawal limits and rules before you budget, since they are updated periodically.
Then there is the nursery setup: a cot, a pram, a car seat, feeding equipment and clothing. These add up, but they are also areas where thoughtful parents save a great deal. Accepting hand-me-downs, buying gently used items and resisting the pull of every new gadget can trim this bill considerably.
When mapping out the financial side of a baby Singapore families often find the one-off costs less daunting than expected, especially once MediSave and available support are factored in.
The ongoing costs
The recurring costs are where planning really pays off, because they continue for years.
Everyday essentials such as diapers, milk and, later, food are a steady monthly expense in the early years. Childcare or infant care is often the biggest ongoing cost once both parents return to work, though subsidies may be available to help; verify what applies to your household.
Healthcare, enrichment, and later on education all add to the picture as your child grows. You do not need to plan every year in advance, but it helps to know these costs rise over time so you can save ahead.
Here is a simplified, hypothetical monthly snapshot for the early years. The figures are round examples only and not a recommendation or an estimate of real costs.
| Item | Example monthly cost |
|---|---|
| Diapers and milk | 200 |
| Infant or child care | 800 |
| Healthcare and insurance | 100 |
| Miscellaneous and savings | 200 |
Treat a snapshot like this as a prompt to build your own, using real quotes and your own circumstances.
Support that may be available
Singapore offers support for parents, and knowing what exists helps you plan with confidence. Because the specifics change, treat the following as general pointers and confirm the current details through official channels.
The Baby Bonus scheme typically includes a cash gift and a Child Development Account, often called the CDA, which can attract government matching on your savings up to certain limits. Funds in the CDA can usually be used for approved expenses such as childcare and healthcare at registered institutions. The exact amounts, eligibility and rules are set by the government and updated over time, so check the latest official information rather than relying on figures you read elsewhere.
There may also be other forms of support, from childcare subsidies to leave provisions and tax reliefs for parents. Explore what your family qualifies for, as these can meaningfully ease the load.
The key message is simple: real help exists, but you should verify the current details yourself, because schemes evolve.
Practical steps before baby arrives
A little preparation goes a long way towards a calm start to parenthood.
Build or top up your emergency fund. A new baby brings unpredictable costs, and a healthy buffer means a surprise does not become a crisis. Aim to have this in place before the birth if you can.
Review your insurance. This is the time to check that both parents have adequate coverage, and to look into health coverage for your child. Life and health protection matters more once someone depends on you.
Update your will and CPF nomination. Becoming a parent is a natural moment to make sure your wishes are documented and your beneficiaries are current. Do not assume these update automatically; confirm the requirements and act deliberately.
Plan for changes in income. If one parent will take extended leave or step back from work, budget for the temporary dip in household income. Planning for it in advance removes a common source of stress.
Talk as a couple. Agree on how you will handle the new costs, who manages what, and what your shared priorities are. Facing the financial side of parenthood as a team makes it far lighter.
Save little and often for the years ahead
The costs of raising a child stretch far beyond the newborn stage, and the gentlest way to meet them is to start saving early and consistently. Even a modest amount set aside each month, begun when your child is small, has years to grow before the larger expenses of schooling arrive. Small and steady beats large and late.
Consider opening a dedicated pot for your child’s future, separate from your everyday accounts, so the money is not accidentally spent. Some parents also explore longer-term, education-focused savings once the immediate baby costs settle. Whatever you choose, keep it simple and automatic, so saving happens without a monthly decision.
Above all, remember that a loving, secure home matters far more to a child than any specific amount of money. Plan sensibly, use the support you qualify for, and then give yourself permission to enjoy this precious, fleeting time.
Preparing financially for a baby is not about having everything perfect. It is about reducing worry so you can be present for the moments that matter. Plan the costs you can foresee, tap the support you qualify for, protect your family with sensible insurance, and keep a buffer for the rest.
This article offers general guidance only. For decisions about MediSave, insurance, grants or your will, please consult a qualified, MAS-licensed professional and always confirm the latest official information before you act.
Explore more
Building an Emergency Fund
Setting Financial Goals
Budgeting in Singapore
Teaching Kids About Money
Frequently Asked Questions
Can I use MediSave for my wife’s delivery bill? MediSave can be used towards certain delivery and pre-delivery expenses within limits set by the authorities. The rules on whose account may be used and how much change from time to time. Check the current rules with the CPF Board before you budget.
How do I register my baby for the Baby Bonus and CDA? Registration and eligibility are handled through official channels, and the details and amounts are updated over time. Look up the current process on the government’s family support websites, and keep your child’s documents ready when you apply.
How can I cut down nursery setup costs? Accept hand-me-downs, buy gently used items and resist buying every new gadget. Focus on essentials like a cot, car seat and feeding equipment first. Thoughtful parents often save a great deal this way without compromising safety.
Should I buy insurance for my baby? It is worth looking into health coverage for your child, and checking both parents have adequate cover, since protection matters more once someone depends on you. Compare options and ask a MAS-licensed adviser what suits your family.
How much should I budget for infant care? Childcare is often the biggest ongoing cost once both parents return to work, and fees vary by centre and arrangement. Get real quotes from places you are considering, then check which subsidies your household may qualify for.
Official sources: Ministry of Social and Family Development (MSF)