
Saving is rarely just about the numbers. Understanding the psychology of saving singapore residents grapple with can explain why good intentions so often fall apart, and how to build habits that stick. Once you see the mental patterns at work, you can design around them instead of relying on willpower alone. This article is general financial information for a Singapore audience, not personalised advice, so apply it in the way that suits your own life.
Why saving is psychologically hard
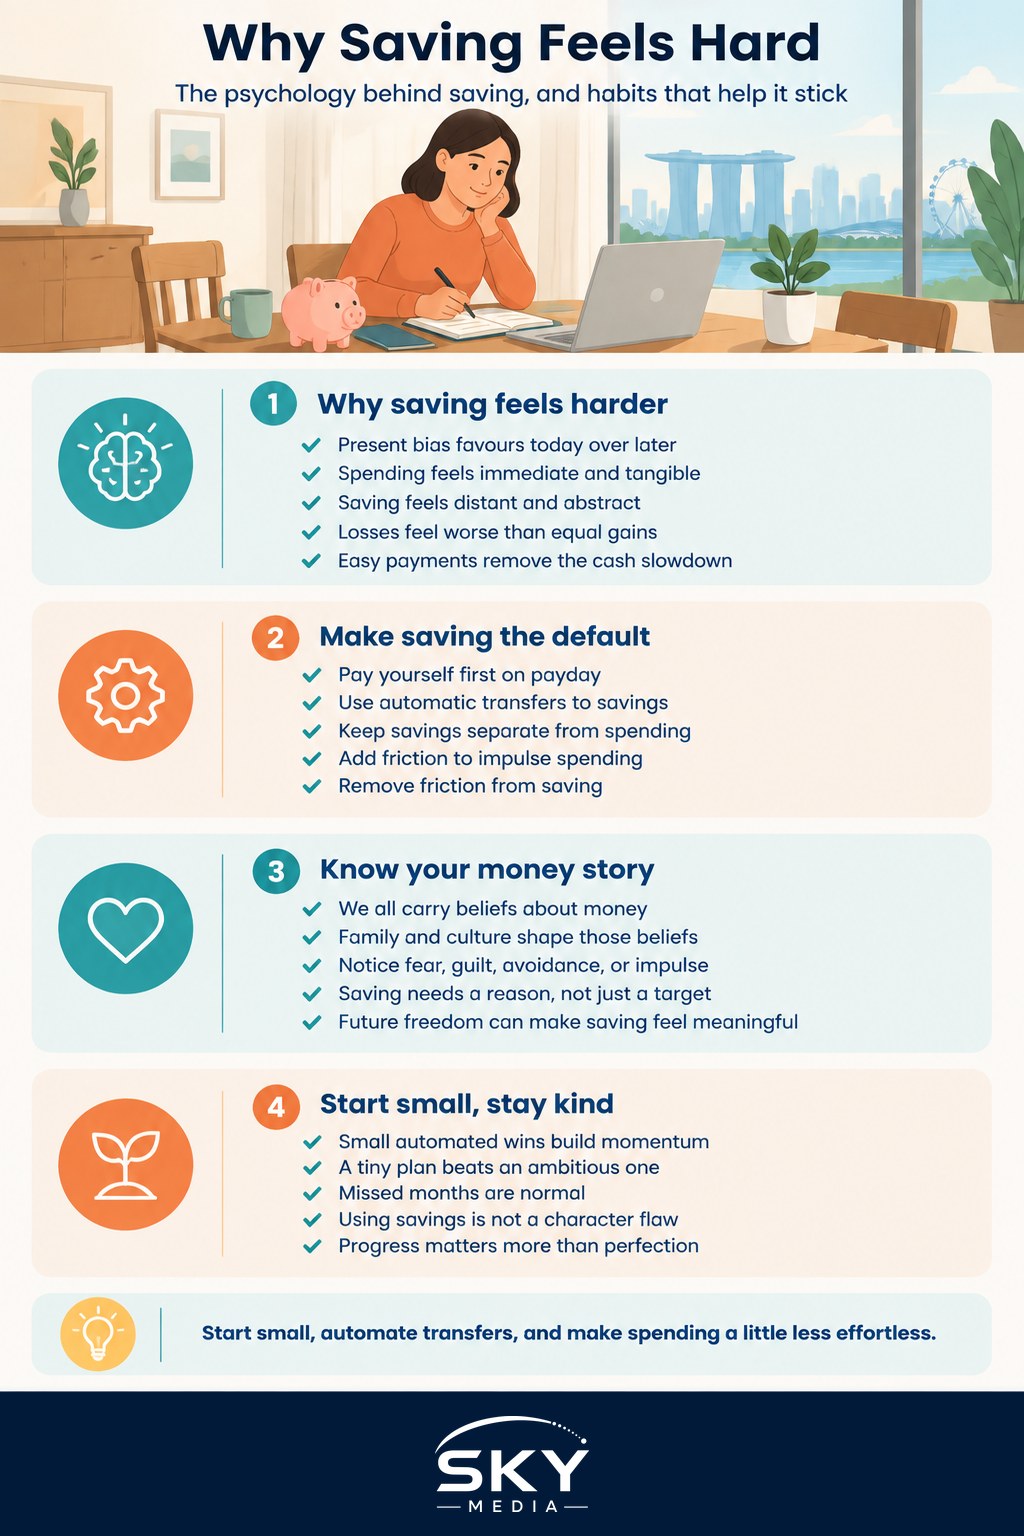
If saving were purely rational, most of us would do more of it. The trouble is that human minds are wired for the present. Spending gives an immediate, tangible reward, while saving offers a benefit that is distant and abstract. Our brains tend to value the reward we can enjoy now far more than the larger one we would enjoy later, a tendency behavioural researchers call present bias. That is why a treat today can quietly beat a stronger future you never quite pictures.
Several other patterns pull in the same direction:
- Loss aversion. Cutting back on spending can feel like a loss in the moment, and we are wired to dislike losses more than we enjoy equivalent gains.
- The pain of paying is fading. Cards, PayNow, and one-tap payments make spending frictionless, which removes the small mental speed bump that cash used to provide.
- Lifestyle creep. As income rises, spending tends to rise to match, so saving never feels any easier no matter how much more you earn.
None of these make you irresponsible. They are ordinary features of how people think about money. The useful response is not guilt but design: arranging your finances so the easy choice is also the sensible one.
Working with your biases, not against them
Because willpower is unreliable, the most effective savers lean on structure. The goal is to make saving the default that happens without a decision each month.
The single most powerful move is to pay yourself first. Set up an automatic transfer to savings on payday, before the money reaches your spending account. This flips the usual order, where people spend and then try to save whatever is left, which is usually not much. Automating removes the daily temptation entirely. Our guide on how to automate your money and savings covers the setup, and pairing it with smart money habits helps the routine hold.
A few more evidence-friendly nudges:
- Add friction to spending, remove it from saving. Unsave stored card details, mute shopping notifications, and keep your savings in a separate account that is a little inconvenient to raid.
- Name your goals. Money labelled “Japan trip” or “home fund” is harder to spend than an anonymous balance, because the label makes the future goal feel real.
- Make progress visible. A tracker, a chart, or a filling savings pot turns an abstract habit into something you can see, which keeps motivation alive.
Money stories and mindset
We each carry a “money story”, a set of beliefs absorbed from family, culture, and experience. Some people learned that money is a source of anxiety to be hoarded. Others learned that it is meant to be enjoyed now. Neither extreme is wholly right, and neither makes you good or bad with money. Noticing your own default reaction to money, whether it is fear, guilt, avoidance, or impulse, is the first step to responding more deliberately.
It also helps to define what you are saving for beyond a number. Saving purely to reach a figure can feel joyless. Saving for security, freedom, a family goal, or peace of mind gives the habit meaning, and meaning sustains effort far longer than discipline alone. Many people find that reframing saving as buying future freedom, rather than giving something up today, makes it feel less like deprivation.
If money is a source of ongoing stress, be gentle with yourself. Financial worry is common and does not reflect your worth. Our guide on how to cope with financial stress offers supportive, practical steps, and speaking to a professional is always a reasonable choice if the worry weighs heavily.
Small wins and self-compassion
Behaviour change sticks best when it starts small and feels achievable. A tiny automated transfer that you never miss beats an ambitious plan you abandon after a month. Early, easy wins build a sense of momentum and identity: you begin to see yourself as someone who saves, and that self-image does much of the work over time.
Just as important is dropping the perfectionism. A month where you save nothing, or dip into your fund for something that mattered, is not a failure of character. It is a normal part of a long journey. People who treat slip-ups with self-compassion tend to get back on track faster than those who spiral into guilt and give up entirely. Progress, not perfection, is the realistic aim.
A practical wrap-up
The psychology of saving comes down to a simple insight: our minds favour the present, so the fix is to make saving automatic and the future feel real. Pay yourself first, add friction to spending, name your goals, and be kind to yourself when things wobble. Understand your own money story, start small, and let structure carry the load that willpower cannot. For general financial education, MoneySense is a useful resource, and it is always worth checking current official information for your own circumstances.
Frequently Asked Questions
How do I stop lifestyle creep after getting a pay rise? Decide in advance where the extra income will go, before it lands in your account. Raise your automatic savings transfer on the same day your pay increases, and let only a small part of the rise go to spending. Because you never see the money, it is much harder to absorb into everyday habits.
Why do I overspend even when I know I should save? Overspending usually comes from how the mind treats rewards, not from a lack of intelligence. Spending feels good now while saving pays off later, and tap-to-pay makes buying almost effortless. Changing the setup helps more than trying harder: automate savings and add small hurdles to spending.
How can couples with different money habits save together? Start by talking about what each person wants the money to do, since different habits often trace back to different money stories. Many couples agree on shared goals and a joint pot for them, while keeping some personal spending money each. Having a clear plan removes a lot of friction and quiet resentment.
Is it normal to feel guilty when I spend on myself? Yes, it is very common, especially if you grew up around money anxiety. Guilt does not mean you did anything wrong. Planning a small amount for enjoyment in your budget can make spending feel deliberate rather than a lapse, which helps you stick with saving in the long run.
Should I save first or pay off debt first? It depends on how costly the debt is and how secure your finances feel. Debt with high interest generally deserves priority, but having at least a small cushion stops an emergency from pushing you deeper into borrowing. A licensed financial adviser or MoneySense resources can help you weigh your own situation.
Further reading: Savings Challenges That Actually Work