
A credit card can be one of the most useful tools in your wallet or one of the most expensive. The card itself is neutral. What decides whether it helps or hurts you is a handful of everyday habits: how you pay the bill, how you track spending, and how you respond when something goes wrong. These credit card tips for Singapore focus on those habits, so a card works as a convenience and a safety net rather than a slow leak on your finances.
This is general information, not financial advice. Card terms, fees and interest charges vary by bank and change over time, so always check the current details in your cardholder agreement or with your bank before deciding anything.
Always Pay the Full Statement Balance
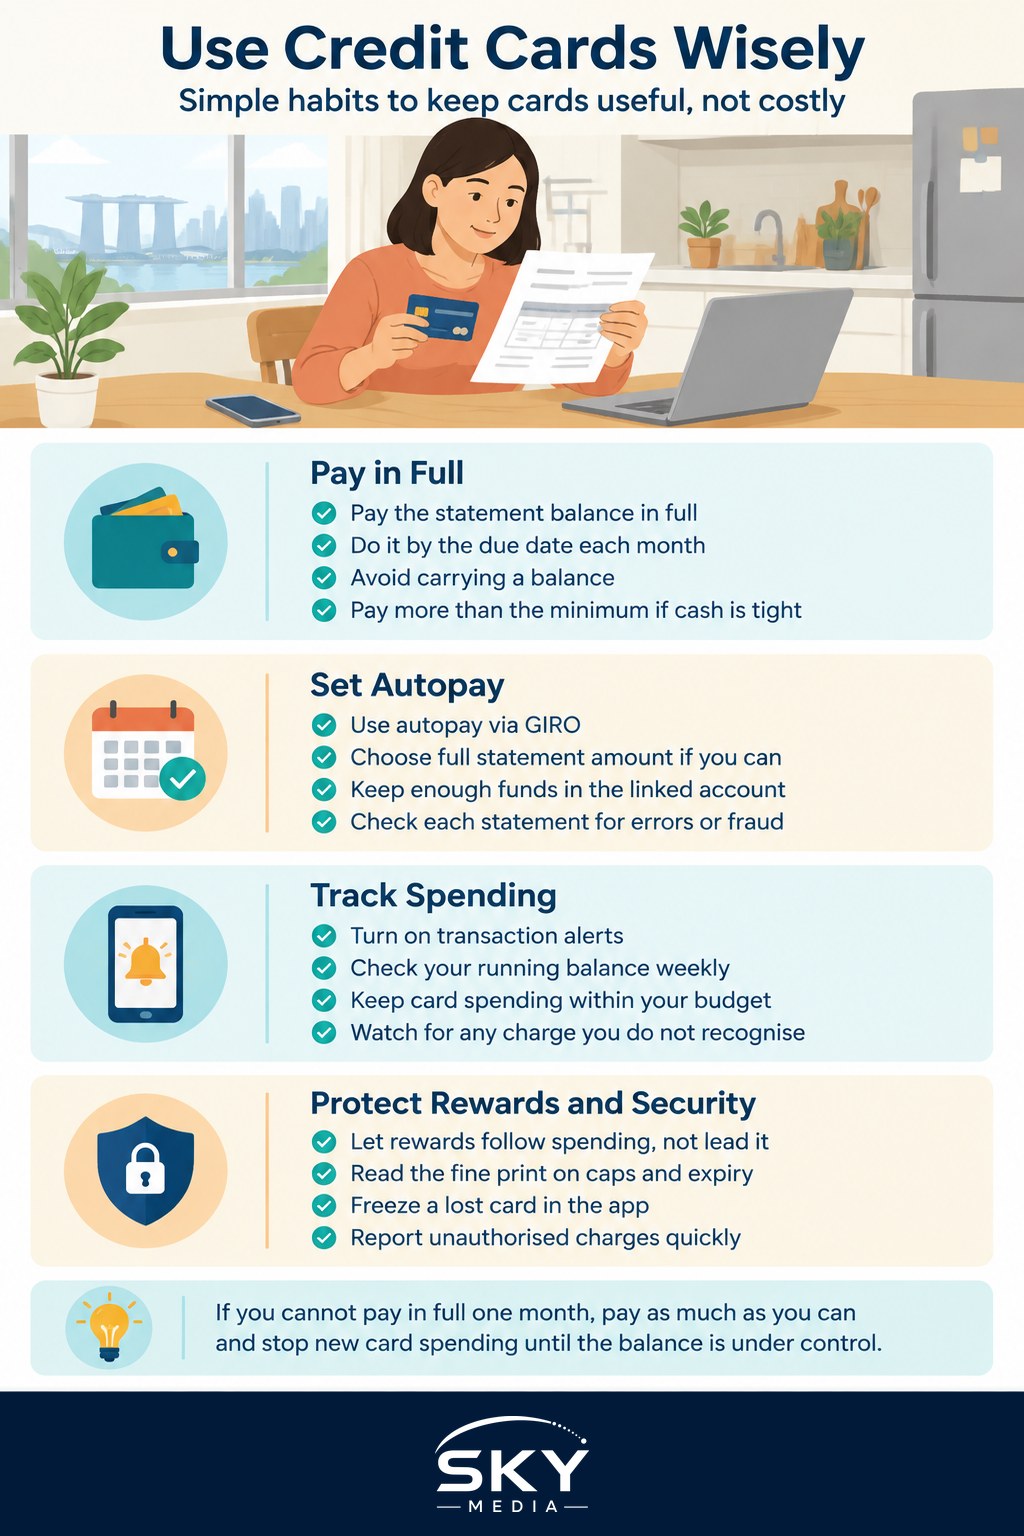
The single most important habit is to pay your statement balance in full, every month, by the due date. When you do this, a credit card is essentially a short interest-free convenience: you buy now, the bank fronts the cash, and you settle up a few weeks later at no extra cost.
The trouble starts the moment you carry a balance. Credit cards typically charge a much higher interest rate than most other forms of borrowing, and once you leave any amount unpaid, that interest can apply and compound. Because rates change and differ between banks, we will not quote a figure here. What matters is the principle: unpaid card balances are among the most expensive everyday debt you can hold, so clearing the full statement each month is the habit that protects you.
If money is tight one month and you genuinely cannot pay in full, pay as much as you can rather than the bare minimum.
Why Paying Only the Minimum Costs You
Every statement shows a minimum payment, a small fraction of what you owe. Paying only that amount keeps your account in good standing, but it is a trap in slow motion.
- The rest of your balance keeps accruing interest.
- New purchases can lose their interest-free grace period once you are carrying a balance, so fresh spending may start being charged interest straight away.
- Because you are chipping away so slowly, a modest balance can take a very long time to clear and can cost far more than the original purchases.
Think of the minimum payment as the emergency floor, not the target. The target is always the full balance. If you find yourself reaching for the minimum month after month, that is a sign to pause new card spending and make a plan to pay the balance down.
Set Up Autopay and Never Miss a Due Date
Late payments can trigger late fees and, over time, affect how lenders view you. The simplest fix is to remove human forgetfulness from the equation by setting up autopay via GIRO from your bank account.
Most banks let you choose to auto-deduct either the full statement amount or the minimum. Choose the full statement amount wherever your cash flow allows, so the bill is always cleared in full and on time. Keep enough in the linked account to cover it, and still glance at each statement when it arrives, because autopay pays the bill but it does not check the bill for errors or fraud.
If your income is irregular, a middle path is to set autopay to the minimum as a safety net against late fees, then manually top up to the full amount each month.
Track Your Spending as You Go
A card makes spending frictionless, which is exactly why it needs tracking. When the money does not physically leave your hand, it is easy to lose the thread until the statement lands.
- Turn on transaction alerts in your banking app so every charge pings you in real time. This doubles as early fraud detection.
- Check your running balance weekly rather than waiting for the statement.
- Keep card spending inside the budget you would have set for cash, not above it.
If you want a structured way to rein spending in, our guide on cutting your monthly expenses in Singapore pairs well with card discipline.
Don’t Let Rewards Drive Your Spending
Cashback, miles and points are genuinely nice when they ride along on spending you would have done anyway. The rewards trap is when the chase quietly reshapes your behaviour: spending more to hit a minimum, buying things you do not need for bonus points, or holding a balance whose interest dwarfs any reward earned.
A few guardrails keep rewards on your side:
- Rewards are only ever a rebate on spending, never a reason to spend.
- No rewards rate beats the cost of carrying interest. Earning points while paying interest is a net loss.
- Read the fine print on caps, minimum spends, exclusions and expiry so the perk you are chasing actually exists.
Choosing a card whose rewards match how you already live matters more than chasing the flashiest sign-up offer, something we cover in choosing a credit card in Singapore.
Manage Multiple Cards and Your Credit Limit
Several cards can make sense, but each one is another due date, another statement and another limit to watch. If you hold more than one, keep the system simple: put the bulk of spending on one main card, set every card to autopay, and diarise the due dates so none slips through.
Your credit limit is another lever you control. A high limit is not free money, it is simply the ceiling on what you can owe. If a large available limit tempts you to overspend, you can ask your bank to lower it to something that matches your real budget. If a card is lost, or you want to pause temptation, most banking apps let you freeze the card instantly and unfreeze it later. For a card you have stopped using, consider whether to keep it open or close it, weighing convenience against having one less account to monitor.
Protect Yourself From Fraud and Dispute Wrong Charges
Credit cards come with meaningful fraud protections, but they only work if you act promptly.
- Watch your alerts. If a charge looks unfamiliar, do not ignore it.
- Freeze or report immediately. Use the app to freeze the card, then call your bank’s official hotline (the number on the back of the card) to report a lost, stolen or compromised card.
- Dispute the charge. Banks have a formal dispute process for unauthorised or incorrect transactions. Raise it quickly, keep records, and follow up in writing.
- Guard your details. Never share your card number, CVV, OTP or PIN. No legitimate bank will ask for your OTP. If you suspect a scam, you can use ScamShield and the Police anti-scam resources, and verify the current reporting channels rather than trusting a number sent to you.
Treat your card details like cash and your OTP like a house key.
Habits That Keep a Card Working for You
| Habit | Why it helps |
|---|---|
| Pay the full statement each month | Keeps the card interest-free and stops costly balances forming |
| Set autopay to the full amount via GIRO | Removes the risk of late fees and missed due dates |
| Turn on real-time transaction alerts | Spots overspending early and flags fraud fast |
| Let rewards follow spending, never lead it | Avoids buying more just to earn points worth less than the interest |
| Match your credit limit to your real budget | Reduces the temptation and the damage of overspending |
| Freeze a card instantly if it is lost | Cuts off unauthorised use in seconds |
| Review every statement line by line | Catches billing errors and unfamiliar charges you can dispute |
Explore More
A card is only one part of a healthy money picture. If your balances have grown faster than you would like, our supportive guide on how to get out of debt in Singapore walks through practical steps to regain control. And before you apply for anything new, choosing a credit card in Singapore helps you pick a card that fits your spending rather than the other way around.
Frequently Asked Questions
What should I do first if I spot a charge I did not make? Contact your bank straight away through its official hotline or app, and ask to dispute the transaction and, if needed, block or replace the card. Keep screenshots or statements as evidence. Acting quickly matters because banks set time limits for reporting unauthorised transactions, so do not wait for the next bill.
Is it safe to save my card details on shopping sites and apps? It is convenient but carries some risk, since a breach at one merchant can expose your details. If you do save a card, stick to well-known platforms, use strong unique passwords with two-factor authentication, and check statements regularly. Many people prefer to enter details manually on smaller or unfamiliar sites.
Does using a credit card for everyday purchases help or hurt my finances? It helps only if you clear the full balance every month and the card does not push you to spend more. Used that way, you earn rewards and gain a record of your spending. If you find yourself buying more because it feels painless, switching some purchases back to debit or cash is a sensible reset.
Should I use a credit card or a debit card when travelling overseas? Many travellers carry both. A credit card often offers stronger dispute protection, but overseas charges and currency conversion may add fees, so check your card’s terms before you go. Keep a debit card or some cash as a backup, and tell your bank if you want to avoid your card being flagged.
Official sources: MoneySense