
If you have ever tried to sort out home insurance Singapore residents commonly get confused about two very different things that both get called “home insurance”. One is the fire insurance often required when you take an HDB or bank home loan, which covers the building structure. The other is home contents or renovation insurance, which protects your belongings and the money you sank into your renovation. They are not the same, and having one does not mean you have the other. This guide explains what each covers, why the policy tied to your mortgage is usually not enough on its own, what tenants should think about, and what to compare before you decide. Everything here is general information, not financial advice; your situation is unique, so weigh these points against your own circumstances and verify the terms directly with a MAS-regulated insurer, and consider a licensed financial adviser where relevant.
The Two Ideas People Confuse
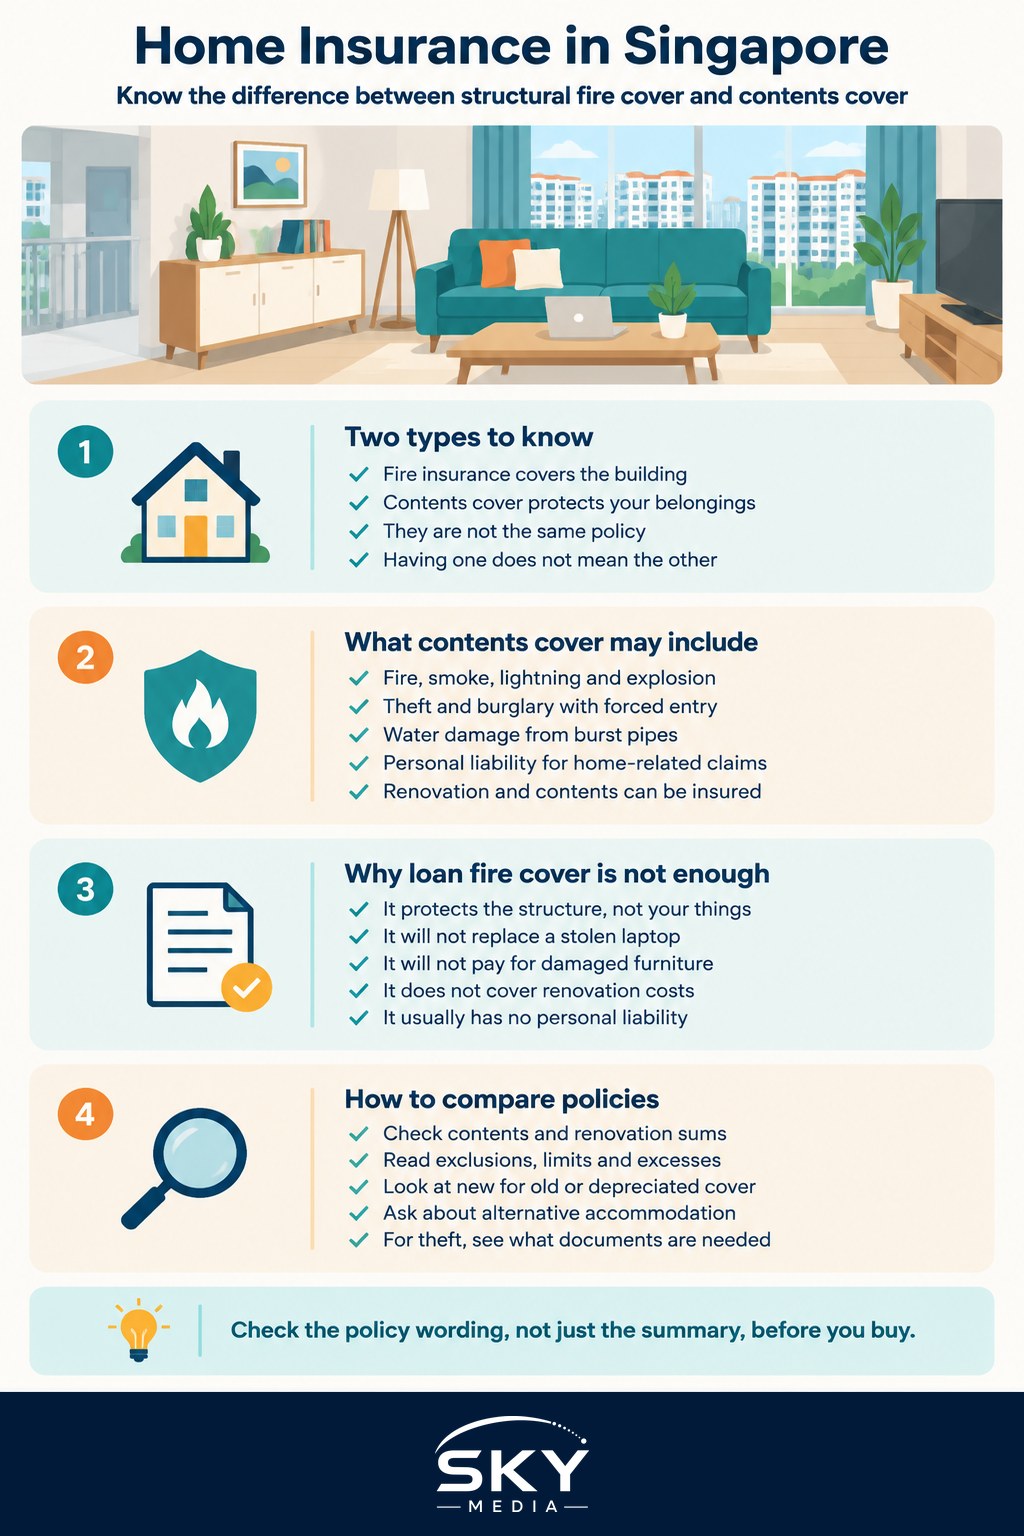
The first is fire insurance on the structure. When you buy an HDB flat with an HDB loan, you are typically required to have the HDB Fire Insurance Scheme, and when you buy with a bank loan the bank usually requires fire insurance too. This kind of policy covers the building itself, meaning the structure and the fixtures originally provided, against damage from fire and certain related perils. It exists mainly to protect the value of the property that the loan is secured against.
The second is home contents insurance, sometimes bundled and sold as a home or householder’s policy. This protects the things inside your home that belong to you, along with your renovation, against a range of events. Your furniture, appliances, electronics, clothes and the built-in carpentry you paid for are not covered by a basic structural fire policy, because they are not part of the original building. This gap is the single most important thing to understand about protecting your home here.
What Home Contents Insurance Covers
A contents or home insurance policy generally aims to cover your possessions and renovation against a defined list of events. Exactly what is included varies between insurers and between plan tiers, so always read the specific policy, but common areas of cover include:
- Fire and related perils. Damage to your belongings and renovation from fire, smoke, lightning and often explosion.
- Theft and burglary. Loss of your possessions from a break-in, usually where there is evidence of forced entry.
- Water damage. Damage from burst pipes, tank overflow or similar, subject to the policy terms.
- Personal liability. Cover if you are found legally liable for injury to someone or damage to their property connected to your home, up to a stated limit.
- Renovation and contents. Many plans let you insure your renovation and contents up to chosen sums, sometimes with cover for temporary accommodation if your home becomes unliveable after an insured event.
Policies carry exclusions, conditions, excesses and limits. Valuables such as jewellery or high-end gadgets may have single-item caps, wear and tear is generally excluded, and some perils may need to be added rather than being automatic. The claim you can make also depends on whether items are insured on a “new for old” basis or after depreciation, so this is worth checking carefully.
Why the Mortgage Fire Policy Is Not Enough
The fire insurance attached to your loan is designed to protect the lender’s and the property’s structural value, not your life inside the home. It is easy to assume you are fully covered because the bank arranged something, but that policy typically does none of the following: it does not replace a stolen laptop, it does not pay for water-damaged furniture, it does not cover the renovation and built-in carpentry you spent tens of thousands on, and it does not provide personal liability cover.
For most households, the belongings and renovation are worth far more than people realise once you add everything up. A single incident, a kitchen fire, a burst pipe soaking the flooring, or a break-in, can mean a large out-of-pocket bill if the only policy you hold is the structural fire cover. This is why many homeowners choose to add a separate home contents policy on top of the mandatory fire insurance, so that both the building and everything inside it are protected.
Mortgage insurance is not home insurance
Another common mix-up is mortgage reducing term insurance, which often comes up alongside your loan. This is a life insurance product that pays off your outstanding housing loan if the insured person dies or becomes totally and permanently disabled. It protects your family’s ability to keep the home, not the home itself. For HDB flats bought with CPF, the Home Protection Scheme (HPS), administered by the CPF Board, plays a similar role.
These products sit beside, not inside, property and contents insurance. A complete picture usually includes structural cover, a renovation and contents policy, and a mortgage or loan-protection arrangement, each doing a distinct job.
Renters and Home Contents
If you are renting, the situation is often misunderstood in the other direction. The landlord’s insurance, if any, covers the landlord’s interests, typically the building and possibly the landlord’s own fittings. It does not cover your personal belongings. If your laptop, clothes and furniture are damaged by an insured event, or stolen, the landlord’s policy is unlikely to help you.
Tenants can buy a contents-only home insurance policy that covers their own possessions without insuring the structure, since the structure is not theirs to insure. This tends to be a smaller, more affordable policy focused on your things and, in many plans, personal liability. If you rent, it is worth asking an insurer about a contents policy sized to what you actually own rather than assuming you are covered by someone else.
Comparing Home Insurance Policies
Because plans differ widely, comparing like for like matters more than chasing the lowest price. Look at the sum insured for both contents and renovation and check it reflects what it would actually cost to replace everything today. Read the list of covered perils and, just as important, the exclusions. Check whether items are covered new for old or on a depreciated basis, note the single-article limits for valuables, and understand the excess you pay per claim. Look at whether personal liability and alternative accommodation are included, and confirm the claims process and any documentation you would need, such as police reports for theft.
The table below sets out the main policy types and what each typically covers. Treat it as a general map; the exact terms always come from the specific policy wording.
| Policy type | What it typically covers | What it usually does not cover |
|---|---|---|
| HDB / bank fire insurance | The building structure and original fixtures against fire and related perils | Your belongings, renovation, theft, water damage to contents, liability |
| Home contents insurance | Your possessions and renovation against fire, theft, water damage, plus personal liability | The building structure itself, wear and tear, uninsured valuables above caps |
| Contents policy for renters | The tenant’s own belongings and often personal liability | The building structure and the landlord’s fixtures |
| Combined home / householder plan | Bundles contents and renovation cover, sometimes with add-ons like accidental damage | Anything listed as an exclusion; perils not selected or not included |
How Much Cover You Need
The two figures that matter most are your renovation value and your contents value.
- Renovation. Add up what you actually spent turning the unit into a home: carpentry, flooring, painting, wardrobes, kitchen cabinetry and similar fixed works. If you kept your quotations, this is straightforward. If your policy limit is lower than this figure, you are under-insured on the very part HDB fire insurance ignores.
- Contents. Walk through each room and estimate the replacement cost of everything you would need to buy again after a total loss. People consistently undervalue this: a television, a laptop, a refrigerator, a washing machine, wardrobes of clothing and a few years of accumulated household items add up faster than expected.
Also check two mechanical details in any quote:
- Basis of settlement. “New for old” replaces items at today’s cost, while “indemnity” deducts for wear and age, which can shrink a payout significantly.
- Single-article limit. Many policies cap the amount payable for any one item unless it is specifically listed, which matters for higher-value electronics or jewellery.
Deciding What Is Right for You
Start by taking stock. Roughly value your renovation and your belongings, note whether your loan requires structural fire insurance, and consider your personal risk, for example living in an older block, owning expensive equipment, or renting. From there you can see whether the mandatory fire policy is your only cover and whether a contents policy would close a meaningful gap. There is no single correct answer; it depends on what you own and what a loss would mean for you.
Whatever you choose, read the policy wording rather than the marketing summary, compare a few insurers on coverage and not just premium, and ask questions about anything unclear before you commit. Keep in mind that this article is general information and not financial advice. For anything specific to your home and finances, verify the details with the insurer directly and consider speaking with a licensed financial adviser.
Making a Claim Smoothly
Insurance is only as good as the claim you can substantiate, so prepare before anything goes wrong.
- Keep renovation quotations, invoices and receipts for major purchases in one folder, digital or physical.
- Photograph each room after renovation and periodically as you add items.
- Note down serial numbers for expensive appliances and electronics.
- Report incidents promptly and, for theft or certain damage, make a police report where required by the policy.
Policy terms, exclusions and any required schemes change over time, so confirm current details and requirements directly with the insurer, HDB or the CPF Board.
Explore more
For more on protecting yourself without wasting money, read our guide to common insurance mistakes to avoid in Singapore, which covers gaps like being underinsured or duplicating cover. If you are still getting your bearings, start with insurance basics in Singapore for how the main policy types fit together.
Frequently Asked Questions
Who pays if my neighbour’s leak damages my ceiling and belongings? Responsibility depends on the cause and the circumstances, and sometimes the neighbour’s insurer or the town council is involved. Your own contents or renovation policy may respond to damage to your property. Document the damage with photos and tell your insurer promptly.
When should I buy a contents policy, before or after moving in? Many people arrange cover once the renovation is under way or completed, so that fittings and belongings are protected from the day they arrive. Your contractor may also have insurance during works. Ask the insurer when your cover starts and what is excluded during renovation.
Can my landlord require me to buy home insurance? Landlords can ask for it as a lease condition, usually for the tenant’s belongings and liability. Check your tenancy agreement for what is required, and confirm with the insurer what the policy covers. Discuss any doubts with your landlord before signing.
Do I need to tell my insurer if I rent out a room? Yes, in most cases, because it changes the risk. Not informing the insurer could affect a claim. Disclose changes such as renting out a room, running a business from home, or major works, and ask whether adjustments to the policy are required.
How often should I update the sum insured on my contents? Review it after renovations, big purchases and every year or two, since replacement costs and your belongings change. Underinsuring can shrink a claim payout. Update the figures with your insurer when your home or possessions change significantly.
Official sources: Monetary Authority of Singapore (MAS)
Further reading: Home Contents and Renter’s Insurance in Singapore