
Singapore Savings Bonds (SSB) are a popular low-risk savings option backed by the government. This guide explains what they are, how they work, their features and who they suit. This is a general overview, not financial advice; for details, refer to official sources such as MAS.
What are Singapore Savings Bonds?
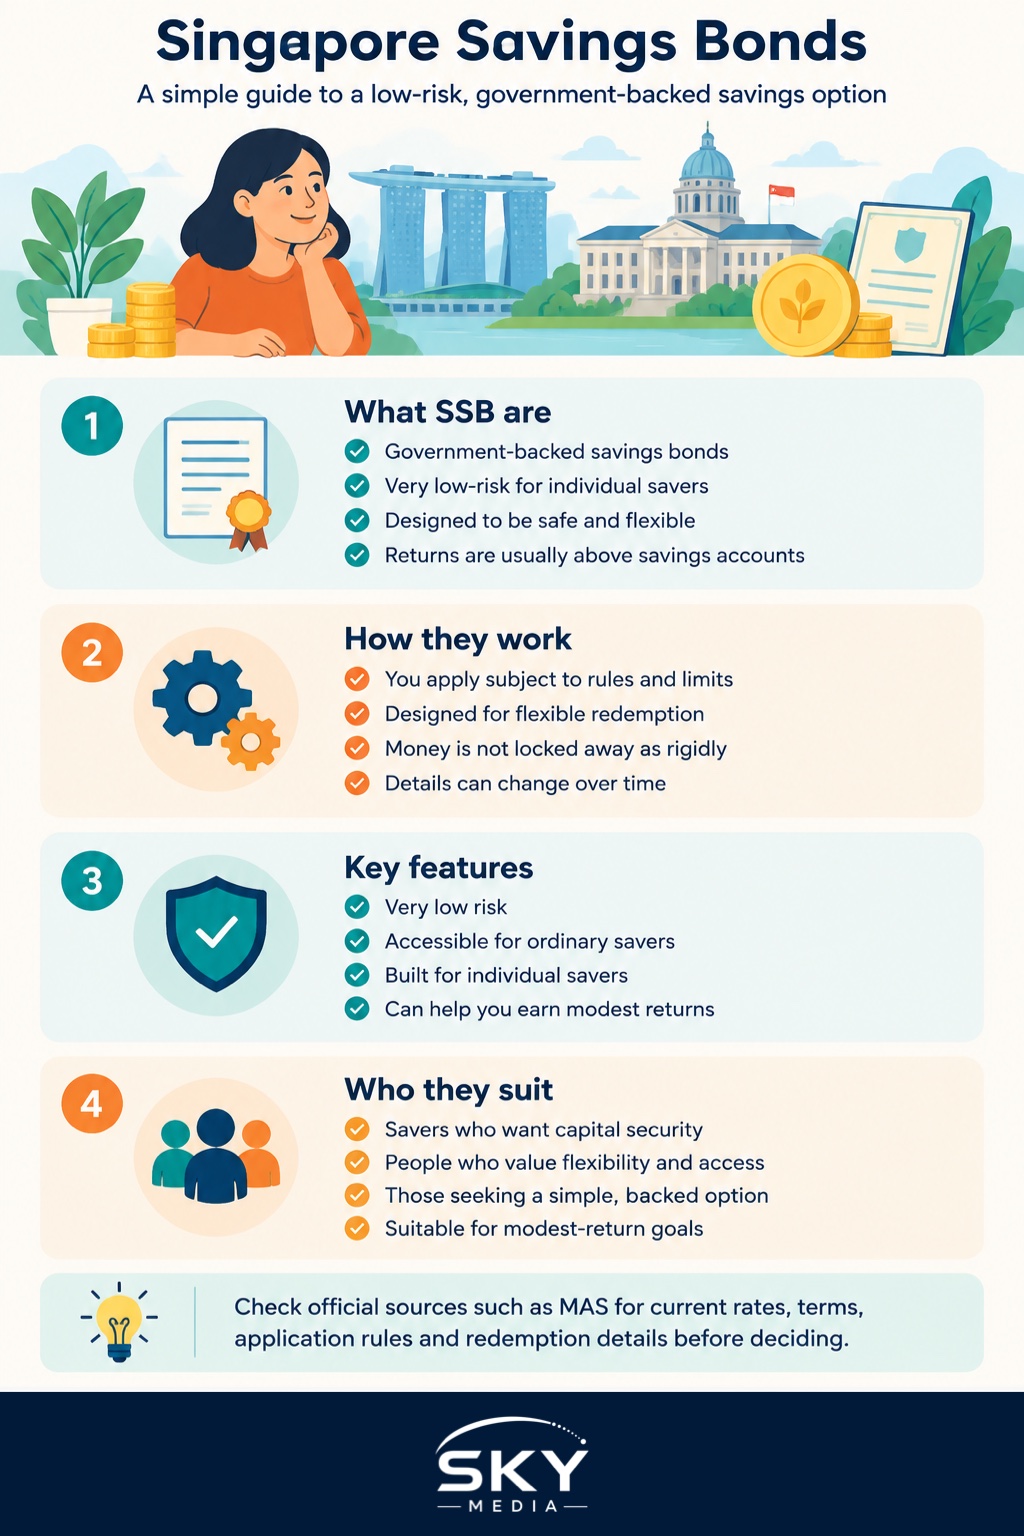
Singapore Savings Bonds, commonly known as SSB, are a type of government savings bond designed to offer individuals a safe, flexible and accessible way to save and earn returns. Backed by the Singapore Government, they are considered a very low-risk option, appealing to those seeking a secure place to put their money with returns typically higher than ordinary savings accounts. SSB are designed to be accessible and flexible, with features that make them suitable for individual savers rather than sophisticated investors. They form part of the range of savings and investment options available in Singapore. Understanding what Singapore Savings Bonds are, a safe, flexible, government-backed savings option, helps you approach them as a potential tool for low-risk saving, and to appreciate their place among the options for growing your money securely. For authoritative details, always refer to official sources.
How they work
| Feature | Broadly |
|---|---|
| Government-backed | Very low-risk |
| Flexible | Redeemable with flexibility |
| Accessible | Designed for individual savers |
| Returns | Typically above ordinary savings |
Singapore Savings Bonds are designed to be simple and flexible for individual savers. Broadly, you can apply to invest in them subject to the applicable rules and limits, and they offer returns over time. A key feature is their flexibility: they are designed to allow redemption with relative ease and flexibility, so your money is not locked away as rigidly as some other instruments. They are government-backed, making them very low-risk, and are intended to be accessible to ordinary savers. The specific mechanics, rates, application process, limits and redemption terms are set by the authorities and can change over time. Because these details are important and subject to change, official sources such as MAS provide the definitive, current information. Understanding broadly how SSB work, as a flexible, low-risk, government-backed savings tool, helps you consider them appropriately while relying on official sources for the specifics.
How to apply for Singapore Savings Bonds
- You need the right accounts. Individuals generally apply using a bank account with one of the main local banks and a Central Depository, or CDP, account for holding the bonds, or through the relevant Supplementary Retirement Scheme route where applicable. Check the current requirements before you start.
- Apply during the application window. Each SSB issue has an application period. You submit your application through your bank’s digital banking platform, an ATM, or the internet banking services that support SSB. Services linked through SGFinDex can also help you see your holdings in one place.
- Allotment. When an issue is popular and demand is high, not everyone necessarily gets the full amount they applied for. The Government uses an allotment process so that the available bonds are shared out, often in a way that favours smaller applications so more people can take part. If you are not fully allotted, the balance is refunded.
- Holding and redeeming. Once allotted, your bonds sit in your CDP or relevant account and earn interest. When you want your money, you submit a redemption request in any month, and the funds are returned to you.
There are limits on how much any one person can hold in Savings Bonds in total, set by the authorities and subject to change, so confirm the current cap before planning a large purchase.
Key features and benefits
Singapore Savings Bonds offer several appealing features. Their safety, being government-backed, makes them a very low-risk option, attractive for those prioritising capital security. Their flexibility, designed to allow redemption without the rigid lock-in of some instruments, is a notable benefit for savers who value access to their money. They typically offer returns above those of ordinary savings accounts, making them a way to earn a little more on savings while keeping risk very low. Their accessibility and design for individual savers make them approachable. These features position SSB as a useful, low-risk savings tool. Understanding the key features and benefits, safety, flexibility, accessible returns, helps you see why Singapore Savings Bonds are a popular option for low-risk saving, and to weigh them against your own needs, while referring to official sources for current rates and terms.
Who they suit
Singapore Savings Bonds may suit those seeking a safe, flexible, low-risk place to save money and earn modest returns. They can appeal to savers who prioritise capital security over higher but riskier returns, those building or holding savings they may need access to, and those wanting a simple, accessible, government-backed option. They can form part of a broader savings and financial plan, complementing other savings and investments. However, because they are low-risk, their returns are correspondingly modest compared to riskier investments, so they suit different goals than growth-focused investing. As with any financial decision, suitability depends on individual circumstances and goals. Understanding who SSB may suit, essentially those seeking safe, flexible, low-risk saving, helps you consider whether they fit your needs, while remembering that this is a general overview and personal circumstances and official information should guide any decision.
Considering SSB
If you are considering Singapore Savings Bonds, approach the decision thoughtfully and with good information. Understand how they fit within your broader financial situation, savings and goals, and how they compare with other options such as savings accounts, fixed deposits and other instruments, each with different risk, return and flexibility profiles. Consider your need for safety, flexibility and access versus higher potential returns. Crucially, refer to official sources such as MAS for the current rates, terms, application process and rules, as these are the authoritative and up-to-date details. If unsure, consider seeking guidance suited to your circumstances. Understanding how to approach considering SSB, informed by your own situation and official information, helps you make a sensible, well-informed decision about whether this low-risk savings option fits your needs, as part of a thoughtful approach to managing and growing your money.
Singapore Savings Bonds vs fixed deposit vs T-bills
Savers often weigh SSB against two familiar alternatives: a fixed deposit at a bank and Treasury bills, or T-bills, which are short-term government securities. Each suits a different need.
- Backed by: SSB are backed by the Government, fixed deposits are backed by the bank, with SDIC deposit insurance up to a set limit, and T-bills are backed by the Government.
- Typical term: SSB can run for up to 10 years with flexibility, fixed deposits have a fixed term, often a few months to a few years, and T-bills are short, generally up to about a year.
- Early exit: SSB can be redeemed in any month with no penalty and capital returned. Fixed deposits are usually locked in, and early withdrawal may forfeit interest. T-bills are generally held to maturity, while selling early depends on the market.
- Interest pattern: SSB step up the longer you hold them, fixed deposits are fixed for the chosen term, and T-bills are bought at a discount and paid at face value on maturity.
- Best suited to: SSB suit flexible medium-term savings you might need back, fixed deposits suit a set amount you can lock away for a known period, and T-bills suit parking a lump sum for a short, defined window.
None of these is universally better. A fixed deposit can suit money you are sure you will not touch for a set period. T-bills can suit a short parking spot for a lump sum. SSB sit comfortably where you want government-backed safety plus the freedom to change your mind. The right choice depends on your time horizon, how likely you are to need the money, and the current rates on offer, which you should always compare at the time.
Where SSB fit in your overall savings
Singapore Savings Bonds are not a get-rich product, and they are not meant to be. They shine as a low-risk holding place for money beyond your day-to-day needs: savings you want to keep safe and growing gently while staying within reach. Many people use them for medium-term goals or as a step up from leaving cash idle, once their basic buffers are in place.
For money you might need instantly, an accessible savings account may fit better, while for genuinely long-term goals you may want a broader mix of investments and their risks.
Remember that all investing, even very safe options, involves weighing return against your own needs, and rates are never guaranteed to stay the same across future issues. This article is general information, not financial advice. Consider your own circumstances and, where useful, speak to a licensed financial adviser or check directly with the official SSB and MAS resources before you decide.
The takeaway
Singapore Savings Bonds (SSB) are a safe, flexible, government-backed savings option designed for individual savers, offering very low risk, notable flexibility with redemption, and returns typically above ordinary savings accounts. They may suit those seeking a secure, accessible place to save and earn modest returns while prioritising capital security and access to their money, and can form part of a broader financial plan. Their low risk means correspondingly modest returns compared with riskier investments. When considering SSB, weigh them within your overall situation and against other options, and always refer to official sources such as MAS for current rates, terms and rules. This is a general overview, not financial advice; personal circumstances and official information should guide any decision.
Explore more: T-bills in Singapore explained · Fixed deposits in Singapore · Investing basics in Singapore
Official sources: MoneySense