
Walk into a bank with a lump sum to place and you may be offered something that sounds like a supercharged savings product: a deposit that could pay more than an ordinary one if markets behave. These structured deposits singapore banks market can be appealing, but they are frequently misunderstood, and the word deposit in the name does a lot of misleading work. This article is general information only and not financial or investment advice. Before committing money, speak to a MAS-licensed adviser and read the product documents in full.
What a Structured Deposit Really Is
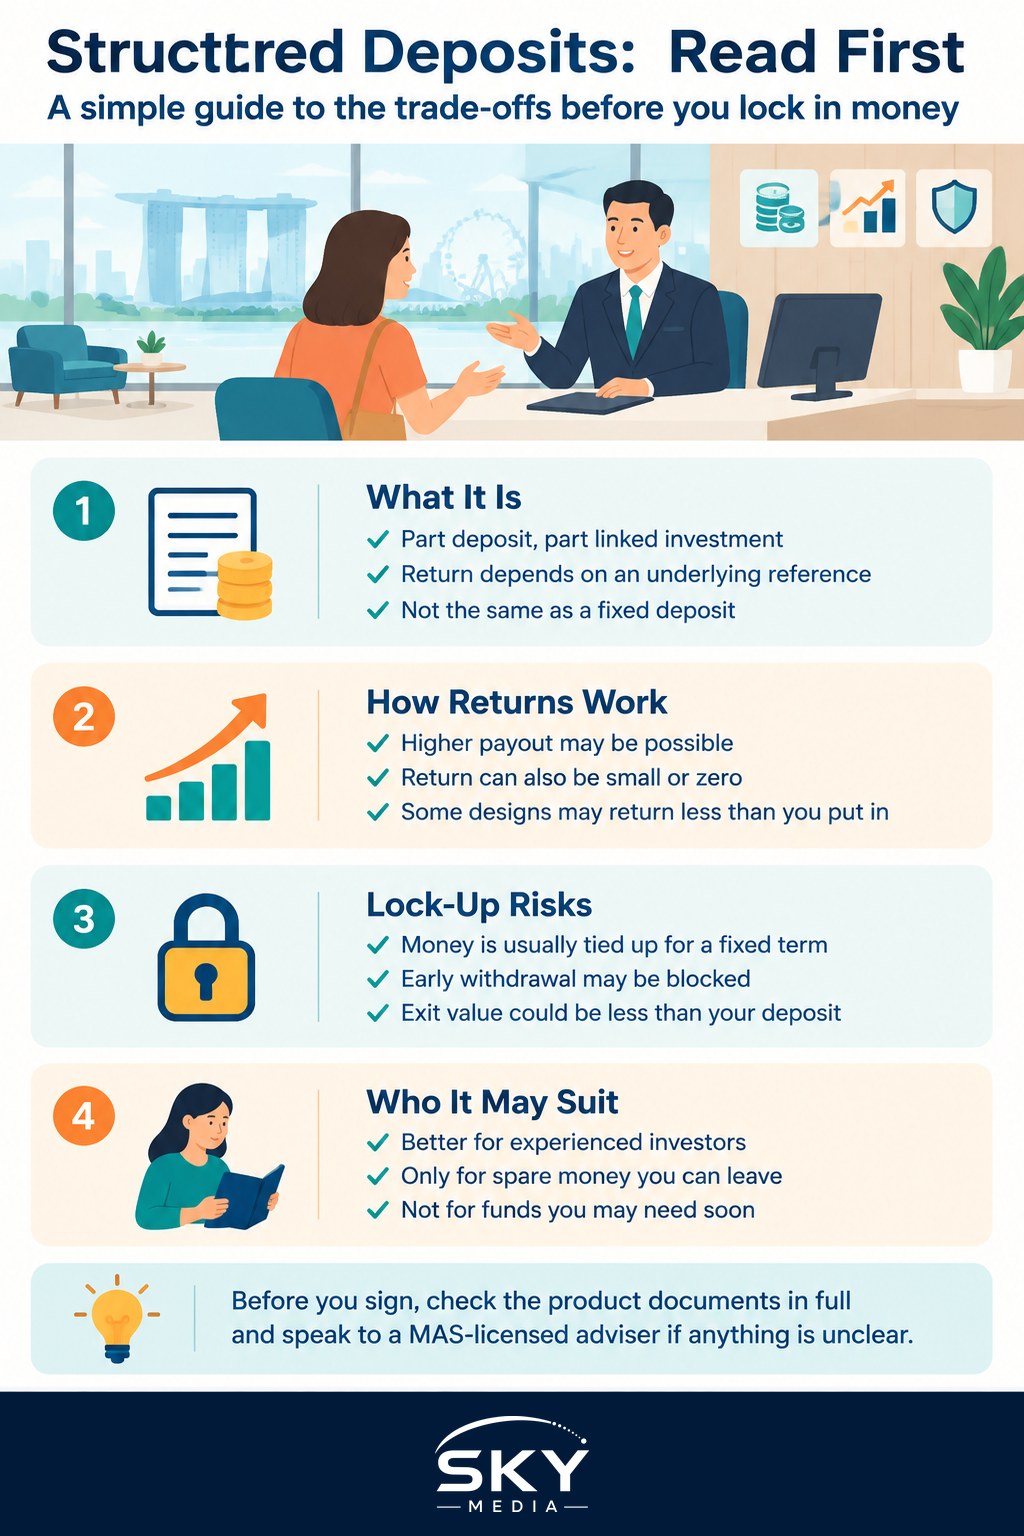
A structured deposit combines two things: a deposit element and an investment element linked to the performance of something else, such as an interest rate, a currency pair, an equity index, or a basket of shares. Your return is not a simple fixed rate. Instead it depends on how that underlying reference performs over the term, according to a formula set out in the product documents.
This is the crucial distinction. A structured deposit is not the same as a fixed deposit. A fixed deposit pays a known, agreed rate and, within the eligible limits, is protected under the deposit insurance scheme. A structured deposit is a more complex product whose return is uncertain and which carries risks a plain fixed deposit does not. Confusing the two is the single most common and costly misunderstanding.
How the Returns Work
The appeal is the possibility of a higher payout. If the underlying reference moves in the way the product is designed to reward, you may receive a return better than a conventional deposit would give. That is the sales pitch, and in the right conditions it can come true.
The catch is that the reverse is also possible. If the underlying does not perform as hoped, you may receive only a small return, no return at all, or in some product designs, less than the full amount you put in. Many structured deposits promise to return your original capital only if you hold them all the way to maturity, and even that promise depends on the bank behind the product remaining sound. Read carefully whether a given product protects your capital fully, partially, or not at all, because these vary widely.
The Lock-Up Problem
Structured deposits typically run for a fixed term, which might be anything from several months to a few years. During that time your money is committed. If you need to withdraw early, you may not be able to at all, or you may be allowed to exit only at a value set by the bank, which could be less than you put in. The capital protection some products advertise usually applies only if you hold to maturity, so an early exit can turn a supposedly safe product into a loss.
This lock-up is a serious practical risk. Money you might need for an emergency, a property purchase, or any near-term goal has no business in a multi-year structured product. Only genuinely spare, long-dated cash should even be considered.
A Simple Comparison
The table below uses hypothetical round numbers to contrast a structured deposit with a plain fixed deposit. These are illustrative figures for teaching only and do not represent any real product or rate.
| Feature | Fixed deposit | Structured deposit |
|---|---|---|
| Return | Known, for example 3 per cent | Uncertain, for example 0 to 6 per cent |
| Capital at maturity | Returned in full | May return only capital, or less in some designs |
| Early withdrawal | Usually allowed, small penalty | May be blocked or at a loss |
| Deposit insurance eligible | Often yes | No |
| Complexity | Simple | Complex |
The comparison makes the trade-off plain. You are being offered the chance of a higher return in exchange for accepting uncertainty, a lock-up, and greater complexity. Whether that trade is worthwhile depends entirely on your circumstances and on fully understanding the specific product.
Questions to Ask Before You Sign
A good habit is to slow down and ask hard questions before committing. Is my capital fully protected, and only if I hold to maturity? What exactly does my return depend on, and under what conditions do I get nothing? Can I withdraw early, and if so, what would I get back? Who is the issuer, and what happens if they run into trouble? What are the fees and costs built into the product? How does this compare with simply placing the money in a fixed deposit or another straightforward option?
If the person selling the product cannot answer these clearly, or if the answers make you uneasy, that is a signal to walk away. There is no obligation to buy something you do not fully understand, and complexity is not a virtue in a savings product.
Who These Might Suit, and Who They Do Not
Structured deposits are generally more appropriate for experienced individuals who understand the underlying references, can afford to lock money away for the full term, and are comfortable with the possibility of a poor or zero return. They are poorly suited to anyone who needs certainty, may need the money sooner, or believes they are buying something as safe as an ordinary deposit.
Capital can be at risk depending on the product, returns are not guaranteed, and past performance of any underlying reference does not guarantee future results. Take your time, read the full documentation, and get independent advice from a qualified professional before placing money into any structured product.
Common Misunderstandings to Clear Up
A few myths lead people astray. The first is the belief that the word deposit guarantees safety. It does not, and a structured deposit is a different animal from a fixed deposit despite the shared name. The second is assuming capital protection is absolute. In many products it applies only if you hold to maturity, and it still depends on the issuing bank staying solvent, so it is a conditional promise rather than an iron guarantee. The third is thinking the advertised maximum return is the likely return. That headline figure is usually the best case, achievable only if the underlying reference behaves in a specific way, and the realistic outcome may be far lower.
The fourth misunderstanding is treating these as flexible. They are not. Your money is committed for the term, and exiting early can be impossible or costly. Clearing up these points before you sign, rather than after, is the difference between an informed choice and an unpleasant surprise later on.
Explore more
Fixed Deposits Guide
Singapore Savings Bonds Explained
Bond Investing
Investing Basics for Beginners
Frequently Asked Questions
Can I lose money on a structured deposit even if the bank is stable? Yes, depending on the product. Some designs return less than your original amount if you exit early or if the underlying reference moves against you. Read the product documents to see exactly when capital is protected, and ask for a clear written explanation.
Does a structured deposit count as a deposit for insurance purposes? Do not assume so. Structured deposits are complex products and may not be covered the way an ordinary fixed deposit can be. Check with the bank and the deposit insurance scheme’s official information before relying on any protection.
Why do banks recommend structured deposits so often? They can be profitable for the bank through built-in costs and, in some cases, commissions, though the details vary by product. That is not a reason to avoid them, but it is a reason to ask about fees and compare plain alternatives.
What is a cooling-off period and does it apply to these products? A cooling-off period lets you cancel certain products within a set time after buying, but it does not cover everything. Ask your bank in writing whether it applies to your product and how long it lasts. Do not assume it exists.
Is it safe to put my retirement savings into a structured deposit? Retirement money usually needs certainty and access, which structured deposits may not provide because of the lock-up and uncertain returns. Speak to a licensed adviser about whether any such product fits your retirement plan before committing.
Official sources: Monetary Authority of Singapore (MAS) · MoneySense