
When people think about selling a property, they focus on the sale price and imagine the whole sum landing in their bank account. In reality, several costs come off the top, and one of the biggest “costs” is not a fee at all but money returning to your own CPF. Understanding the full cost of selling home singapore before you list helps you set realistic expectations and avoid an unpleasant surprise at completion.
This article is general information only, not legal, financial, or property advice. Every sale is different. Speak to your bank, a property lawyer or conveyancer, and a CEA-registered property agent, and check current official rates before you make any decisions.
Agent Commission
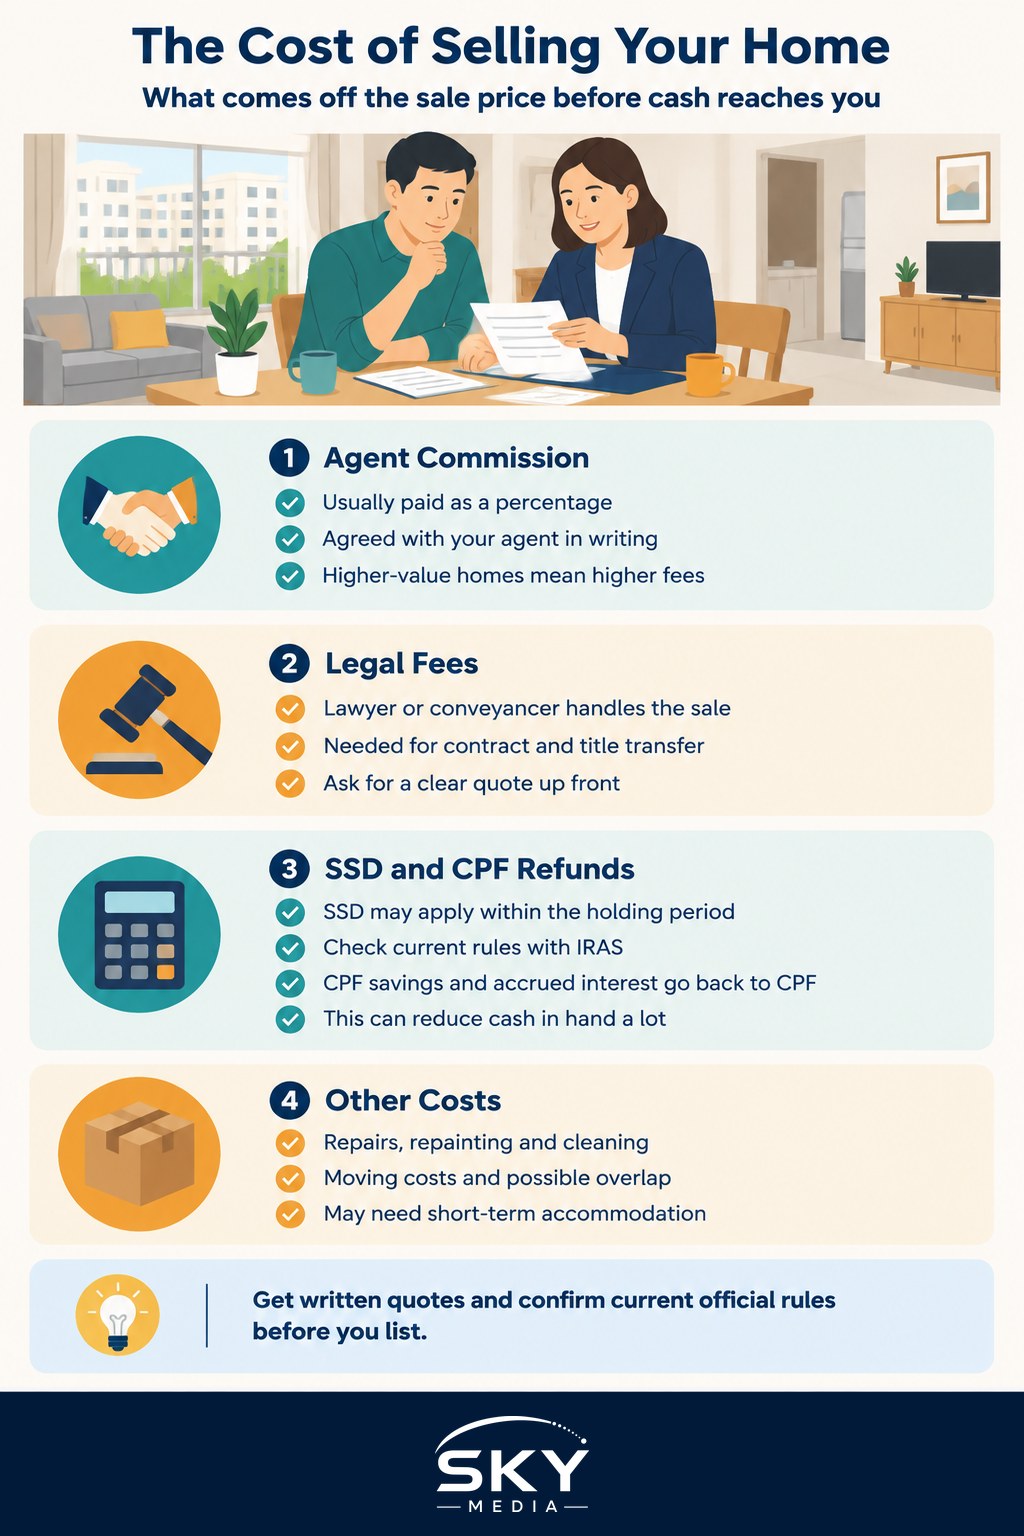
Most sellers engage a property agent to market the home, arrange viewings, and negotiate. Agents are typically paid a commission calculated as a percentage of the final sale price, and the exact rate is a matter of agreement between you and your agent rather than a fixed figure set by law.
A good agent can be worth the cost by reaching more buyers and handling the paperwork and negotiation, but you should still agree the rate and scope of work clearly in writing before you sign anything. Because commission is a percentage of the price, it scales with the value of your home, so factor it in early when you estimate your net proceeds.
Legal and Conveyancing Fees
Selling a property involves a lawyer or licensed conveyancer who handles the contract, liaises with the buyer’s side, manages the CPF and mortgage discharge, and ensures the title transfers cleanly. These legal fees are a necessary part of any sale, and it is sensible to get a clear quote up front so there are no surprises.
If you still have an outstanding home loan, there may also be steps to redeem or discharge the mortgage, and your bank may have its own requirements or charges depending on the terms of your loan. Ask your bank early what applies to your specific situation.
Seller’s Stamp Duty, If It Applies
Seller’s Stamp Duty (SSD) is a tax that may apply if you sell a residential property within a defined holding period after buying it. The idea is to discourage very short-term flipping. If you have owned the home beyond that holding period, SSD generally does not apply at all.
Because the holding period and the rates are set by the authorities and can change, do not rely on old figures or rules of thumb. Check the current position with the Inland Revenue Authority of Singapore (IRAS) or your conveyancer, especially if you bought fairly recently and are thinking of selling sooner than planned.
The CPF Refund With Accrued Interest
This is the part sellers most often forget. If you used your CPF savings to help buy the home, you generally have to refund the amount you withdrew back into your CPF account when you sell, together with the accrued interest, which is the interest that money would have earned had it stayed in CPF.
Crucially, this is not a loss. The money goes back into your own CPF, where it continues to grow for your future housing or retirement. But it does mean the cash that reaches your bank account after the sale can be far smaller than the headline price suggests, because a large chunk is quietly returning to your CPF. Planning for this in advance prevents shock at completion, particularly if you are relying on the sale to fund your next home.
A Hypothetical Illustration
The table below uses round, made-up numbers purely to show how the pieces fit together. These are not real rates, commissions, or prices. Your actual figures will differ, so always work from current official information and your own quotes.
| Item | Hypothetical Amount |
|---|---|
| Sale price | 800,000 |
| Agent commission | 16,000 |
| Legal and conveyancing fees | 3,000 |
| Seller’s stamp duty (if within holding period) | 0 |
| CPF refund with accrued interest | 250,000 |
| Illustrative cash to you | 531,000 |
Look at how much the CPF refund moves the final figure. In this made-up example, the seller receives far less cash than the sale price implies, even though nothing has truly been “lost”, because most of that refund is their own retirement money going home. Redo this exercise with your own numbers well before you sign anything.
Other Costs Not to Overlook
Beyond the big items, smaller costs add up. You may spend on repairs, repainting, cleaning, or minor staging to present the home well. If you are moving, budget for removalists and any overlap where you are paying for two homes at once. If your sale and your next purchase do not line up neatly in time, you may need short-term accommodation or bridging arrangements, which your bank can explain.
Plan Before You List
The smartest thing you can do is map out every cost before the property goes on the market. Ask your agent for the commission terms in writing, get a legal quote, confirm with IRAS or your conveyancer whether SSD applies to you, and request your CPF refund figure including accrued interest. Only then will you know your likely net proceeds, which is the number that actually matters for your next move.
The Bottom Line
The true cost of selling a home in Singapore goes well beyond the sale price. Agent commission, legal fees, any seller’s stamp duty within the holding period, and the CPF refund with accrued interest all shape what you finally receive. None of this should stop you selling, but knowing the numbers in advance turns a stressful surprise into a calm, well-planned decision. Confirm every figure with your bank, a property lawyer or conveyancer, a CEA-registered agent, and current official sources before you commit.
Explore more
Stamp Duty (BSD and ABSD)
Using CPF for Your Home
Home Loan Options
Buying Your First Condo
Frequently Asked Questions
How long does it take to get cash after selling a home? Cash usually does not arrive on the day you sign the sale. It comes at completion, after your lawyer has settled any mortgage and the CPF refund. Timing depends on the contract terms you agree with the buyer, so ask your conveyancer for the expected completion date and the order in which payments are made.
Can I sell my home if I still have an outstanding loan? Yes, many owners sell while still paying off a loan. The sale proceeds are used to redeem the mortgage first, and your lawyer handles the discharge. Check your loan terms with the bank early, because some loans carry notice requirements or charges when repaid before the term ends.
Should I use a property agent or sell my home on my own? It depends on how much time, market knowledge and negotiation confidence you have. An agent can reach more buyers and manage paperwork, while selling alone saves commission but puts all the work on you. Whichever you choose, you still need a lawyer or conveyancer to complete the transfer.
How can I work out my net proceeds before listing? Start with your expected sale price, then subtract agent commission, legal fees, any seller’s stamp duty and the outstanding loan. Finally deduct the CPF refund with accrued interest. Ask your bank and CPF Board for the exact refund figure, since that is often the biggest deduction.
Does the CPF money I refund after a sale belong to me? Yes, it goes back into your own CPF account rather than disappearing. It stays available for future housing or retirement, subject to CPF rules. Think of it as moving savings back to where they came from, not as a cost, although it does reduce the cash you can spend straight away.
Official sources: Council for Estate Agencies