

Most sellers focus on the price their home will fetch, then get a surprise when they see how much comes off the top. The costs of selling Singapore property stretch well beyond the sale price on the listing. There are agent fees, legal work, loan settlement, CPF refunds and the everyday expense of actually moving out. Knowing these in advance helps you set a realistic budget, avoid nasty shocks and understand the cash you will really walk away with. This is general information, not financial or legal advice, and every figure below changes over time, so treat the official sources as the final word and confirm the current numbers before you plan.
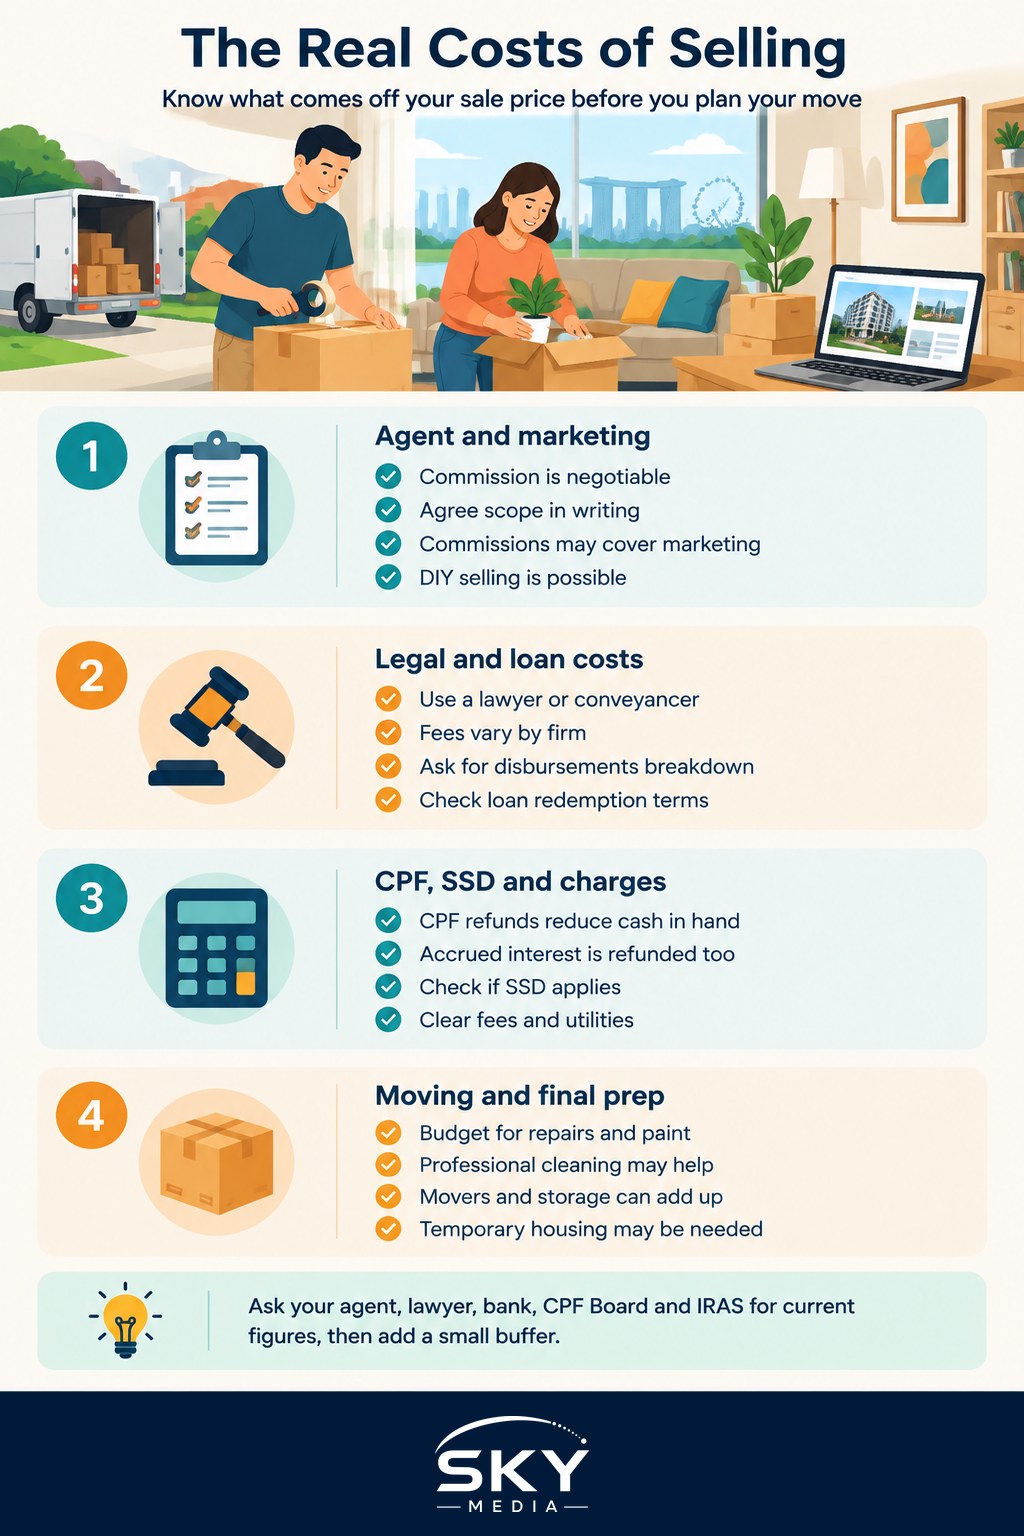
Agent Commission and Marketing
If you appoint an agent, their commission is usually the largest single selling cost. In Singapore, commission is negotiable and is not fixed by any regulator to a set percentage, so do not assume a standard rate. What you pay depends on the agent, the property type and what the market looks like when you sell. Always agree the figure and what it covers in writing before you sign anything.
Use a CEA-registered agent and check their status on the CEA Public Register. A commission typically pays for professional photography, listing on portals, arranging and hosting viewings, negotiating offers and guiding the paperwork through to completion. Some sellers choose to market their home themselves to save on this cost, though that shifts the workload and the legal care onto you. Whatever you decide, clarify whether marketing extras, such as premium listing placements or video, are included in the fee or charged separately.
Legal and Conveyancing Fees
Selling a home is a legal transfer, so you will engage a lawyer or conveyancer to handle it. Their fee covers reviewing the Option to Purchase, preparing and lodging documents, liaising with the buyer’s lawyer, coordinating with your bank and CPF, and managing completion. Conveyancing fees vary between firms, so it is worth asking two or three for a quote and confirming exactly what the fee includes.
There can be additional small charges on top of the base legal fee, such as disbursements for title searches, registration and administrative items. Ask your lawyer for a full breakdown up front. Because the legal steps carry real consequences, this is one cost worth paying properly rather than cutting to the bone. Your lawyer also protects you if a buyer defaults or a completion date slips, which makes their role central rather than optional.
Settling Your Loan and CPF
Two of the biggest items are not really fees at all, but repayments that come out of your sale proceeds. First, if you still have a home loan, the outstanding balance is redeemed from the sale money at completion. Depending on your loan terms and how far into any lock-in period you are, there may also be a prepayment or redemption penalty, so check the exact terms with your bank before you sell.
Second, if you used CPF to buy the home, that money must be refunded to your CPF account when you sell, together with the accrued interest you would otherwise have earned. This is not lost money, since it returns to your own CPF, but it does reduce the cash in hand at completion. Many sellers are caught out here because the sale price looks healthy while the actual cash received is smaller. Work through your own numbers with the CPF Board and your bank so there are no surprises.
Seller’s Stamp Duty and Other Charges
Seller’s Stamp Duty (SSD) may apply if you sell a residential property within a certain holding period after buying it. The rates, the holding period and the exact conditions are set by IRAS and they change, so do not rely on any figure you see quoted casually. Check the current SSD position on the IRAS website, or ask your lawyer to confirm whether it applies to your sale at all. For many long-term owners it will not, but it is essential to check rather than assume.
Depending on your property, there may be other minor costs to close out, such as settling any outstanding maintenance fees, property tax or utilities up to the handover date. For HDB flats, confirm any administrative charges and procedures directly with HDB. None of these are usually large on their own, but together they add up, which is why a written checklist helps.
Moving, Repairs and the Cash You Keep
The final group of costs is the practical one. Getting your home ready to sell and then moving out has its own price tag. Common items include:
- Minor repairs, repainting or decluttering to present the home well
- Professional cleaning before handover
- Movers, packing materials and possibly short-term storage
- Temporary accommodation if your next home is not ready
- Redirecting mail and transferring or closing utility accounts
To see how everything nets out, it helps to compare the main cost categories side by side.
| Cost category | What it typically covers | Who to confirm it with |
|---|---|---|
| Agent commission | Marketing, viewings, negotiation, paperwork | Your CEA-registered agent, agreed in writing |
| Legal and conveyancing | Document work, completion, disbursements | Your lawyer or conveyancer |
| Loan and CPF settlement | Outstanding loan, any penalty, CPF refund | Your bank and the CPF Board |
| Seller’s Stamp Duty | Duty if sold within the holding period | IRAS, or your lawyer |
| Moving and preparation | Repairs, cleaning, movers, temporary housing | Your own quotes and budget |
Once you subtract all of these from your sale price, what remains is your true net proceeds. That figure, not the headline price, is what you can put towards your next home or your savings. Building the estimate early, with real quotes and current official figures, keeps your plans grounded.
Planning Your Sale Budget
The reassuring news is that none of these costs are hidden if you look for them. Ask your agent, lawyer, bank and the CPF Board for their specific numbers, then add a modest buffer for the small items that always appear. Because rates, penalties and duties change, revisit your estimate close to the actual sale rather than relying on old figures. If your situation is complex, for example you are selling and buying together or you are unsure whether SSD applies, get professional advice before you commit. A clear budget turns selling from a stressful guessing game into a straightforward, well-planned move.
Explore more
Before you list, our guide on property agent commissions and fees explains the biggest cost in more depth, while selling your property without an agent covers the do-it-yourself route. If you are moving straight into a new home, read selling and buying a home at the same time, and to understand your final figures see how property valuation works.
Frequently Asked Questions
How can I work out my net proceeds before listing my home? Start with your expected sale price and subtract the loan balance, CPF refund with accrued interest, agent and legal fees, and any stamp duty or moving costs. Get real quotes and ask your bank and the CPF Board for exact figures. Add a small buffer for surprises.
Is it cheaper to sell without an agent once all costs are counted? You save the commission, but the other costs stay, and you take on marketing, viewings and negotiation yourself. Whether that is cheaper depends on how smoothly it goes and how much your time is worth. A lawyer is still needed either way.
Will I pay a penalty for settling my home loan early? Possibly, depending on your loan terms and whether you are within a lock-in period. Check the redemption terms in your loan documents or ask your bank for a written figure before you list. The amount is not something you can safely guess.
Do I have to pay Seller’s Stamp Duty on every sale? No, it applies only if you sell within a certain holding period after buying. Many long-term owners are not affected, but rules and rates change. Check the current position with IRAS, or ask your conveyancing lawyer to confirm for your sale.
Is it worth repainting and repairing before I sell? Small, inexpensive fixes and a tidy clean often help a home show better and attract more interest. Large renovations rarely pay for themselves, so keep spending modest. Compare any quotes against what the work might realistically add to buyer interest.
Official sources: IRAS