
Exchange traded funds are popular for good reason: they offer instant diversification, they trade like a share, and many track a broad market at low cost. Yet the topic of etf fees singapore investors most need to grasp is often glossed over, because the headline expense ratio looks tiny. A fraction of a per cent sounds harmless. Over decades, though, those small percentages compound into real money. This article is general information only, not financial or investment advice. Speak to a MAS-licensed adviser about your own circumstances.
What the Expense Ratio Actually Covers
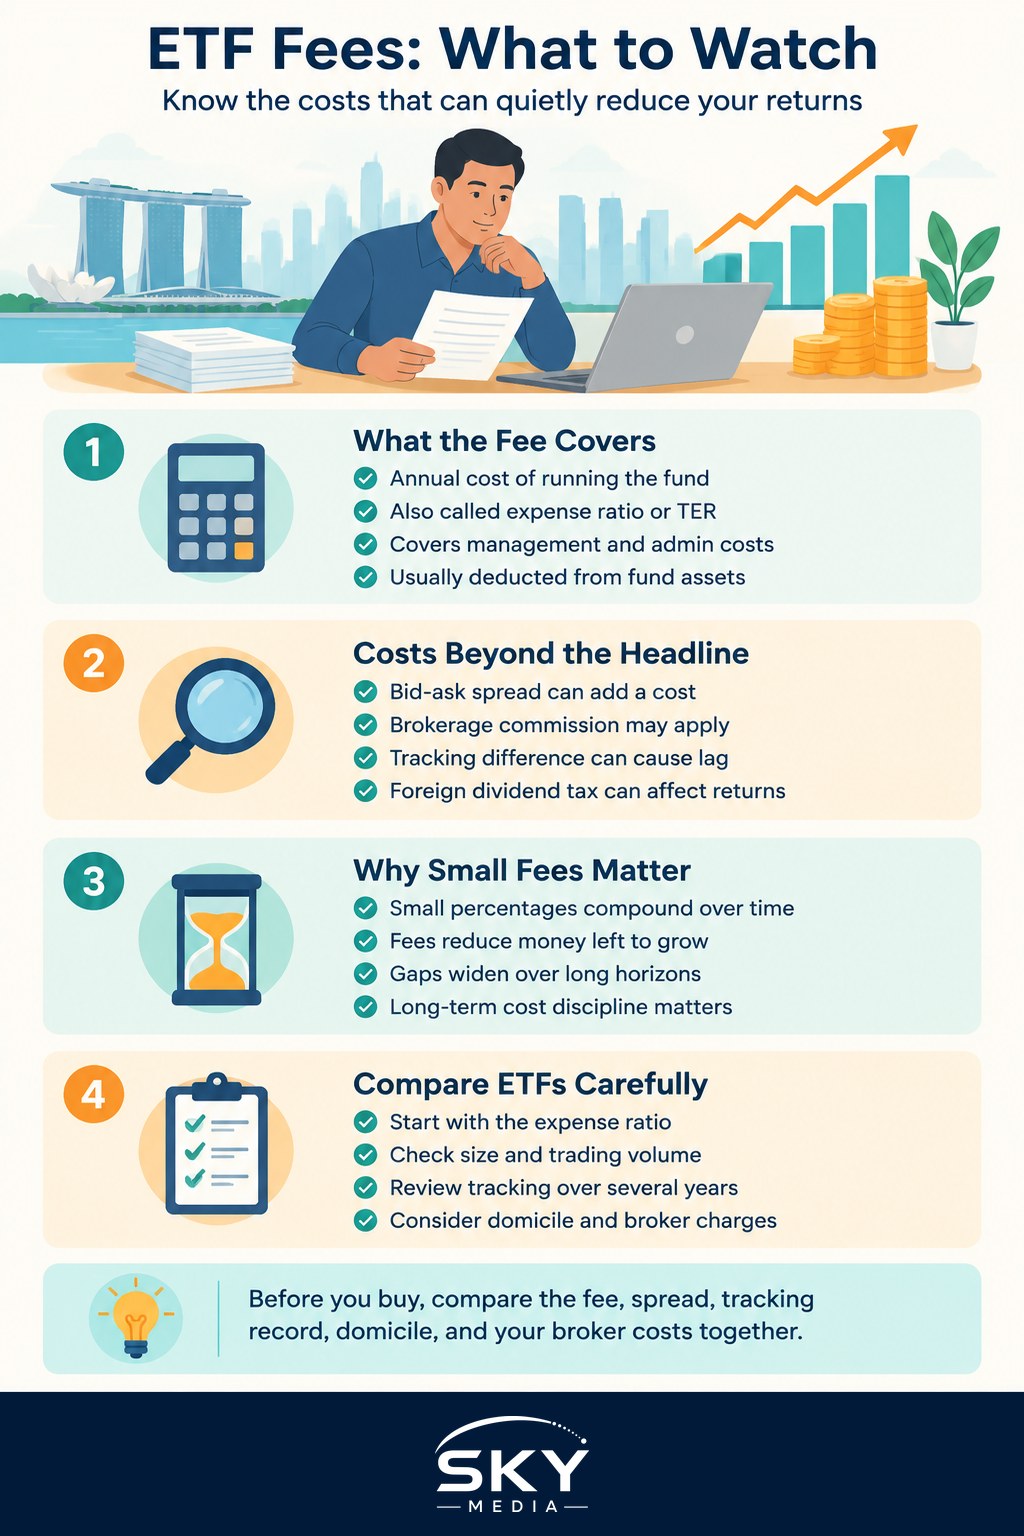
The expense ratio, sometimes called the total expense ratio or TER, is the annual cost of running the fund, expressed as a percentage of the assets. It bundles together the management fee, administrative costs, and various operating expenses. You never receive a separate bill for it. Instead it is quietly deducted from the fund’s assets, which means it is already reflected in the price and the returns you see.
Because the charge is invisible in that way, it is easy to ignore. A broad index ETF might carry an expense ratio well under half a per cent, while some specialised or actively managed products charge considerably more. The difference between a fund charging 0.1 per cent and one charging 1.0 per cent may look trivial on paper, but it is a tenfold gap in ongoing cost.
Why Small Percentages Compound Into Large Sums
Fees do not just cost you the amount charged each year. They also cost you the future growth that money would have earned had it stayed invested. This is the compounding effect working against you.
Consider a simplified, hypothetical illustration. Imagine two funds that both deliver the same gross return before costs, but one charges a low fee and one charges a high fee. The gap between them starts small and widens every year, because the lower-fee fund keeps more money invested and compounding. The table below uses round hypothetical numbers to show the shape of this over time. These are illustrative figures, not a forecast, and real returns vary and are never guaranteed.
| Time horizon | Low-fee fund value | High-fee fund value |
|---|---|---|
| Start | 10,000 dollars | 10,000 dollars |
| After 10 years | 19,000 dollars | 17,000 dollars |
| After 20 years | 36,000 dollars | 29,000 dollars |
| After 30 years | 68,000 dollars | 50,000 dollars |
Notice how the gap grows. Early on the difference is modest, but by the later years the higher-fee fund has fallen well behind, purely because of a persistent drag. This is why cost-conscious long-term investors pay such close attention to the expense ratio.
The Costs Beyond the Headline Number
The expense ratio is important, but it is not the whole story. Several other costs can eat into your returns, and some are easy to miss.
The first is the bid-ask spread, the small gap between the price to buy and the price to sell. On a large, heavily traded ETF this spread is usually narrow. On a thinly traded one it can be wide, and it is a real cost every time you deal.
The second is brokerage commission. Every time you buy or sell an ETF you may pay your broker, so frequent trading multiplies this cost. For someone investing small amounts regularly, commissions can be proportionally heavy.
The third is tracking difference. No fund tracks its index perfectly. The fund’s actual return can lag the index by a little more or a little less than the stated expense ratio would suggest, because of the way the fund is run, cash drag, and how dividends are handled.
The fourth, for funds holding foreign shares, is the tax treatment of dividends inside the fund. Where a fund is domiciled affects the withholding tax it suffers on the dividends it receives, and that quietly affects your net return. Two funds tracking the same index can deliver different outcomes for this reason alone.
How to Compare Funds Sensibly
When you weigh up two similar ETFs, start with the expense ratio but do not stop there. Look at the fund’s size and trading volume, because larger and more liquid funds tend to have tighter spreads. Check the tracking record over several years to see how closely the fund has followed its index in practice. Consider the domicile if the fund holds overseas assets. And factor in what your broker charges you to trade it.
A slightly higher expense ratio is not always the worse choice if the fund tracks its index more tightly or trades with a narrower spread. The goal is the best net outcome after all costs, not simply the lowest single number on the fact sheet.
Keeping It in Perspective
Fees matter, but they are only one part of investing well. A low-cost fund that you panic-sell in a downturn will serve you worse than a slightly pricier one you hold with discipline. Capital is at risk in any market fund, values fall as well as rise, and past performance does not guarantee future returns.
The sensible takeaway is simple. Understand what you are paying, favour transparency, avoid unnecessary trading, and let the maths of low costs work quietly in your favour over the years. Read the fund documents before you buy, and if anything is unclear, ask a qualified professional.
A Quick Checklist Before You Buy
It helps to run through a short mental checklist before committing money to any ETF. Start with the expense ratio and note it down, then find the fund’s assets under management and daily trading volume, since larger and busier funds usually deal at tighter spreads. Look up the tracking difference over the past few years to see how faithfully the fund has followed its index in the real world rather than in theory. If the fund holds overseas shares, check its country of domicile and how that affects the tax drag on dividends. Finally, work out what your own broker will charge you to buy and hold it, including any platform or custody fees.
None of these steps takes long, and together they give you a far clearer picture than the headline expense ratio alone. The habit of checking costs before you buy, rather than discovering them later, is one of the simplest ways to keep more of your returns over a lifetime of investing. Small, consistent attention to cost is not glamorous, but it is one of the few edges an ordinary investor genuinely controls.
Explore more
ETFs Explained for Singapore Investors
Index Investing
How to Read a Fund Fact Sheet
Building an Investment Portfolio
Frequently Asked Questions
What is a good expense ratio for an ETF? There is no fixed benchmark. Broad index ETFs are generally cheaper than specialised or actively managed ones, as the article notes, so compare like with like. Weigh the expense ratio together with spread, tracking difference and your broker’s charges.
Where do I find an ETF’s expense ratio and other costs? Check the fund’s fact sheet and prospectus on the provider’s website, which list the expense ratio and other charges. Your broker may show it too. Look for the tracking record and domicile in the same documents, and ask an adviser if terms are unclear.
Are the fees on an ETF charged separately or taken out of returns? The expense ratio is not billed to you separately; it is deducted within the fund, so it is already reflected in the price. Brokerage commissions and other platform charges are separate and appear on your own account statements.
Does a lower fee always mean a better ETF? Not always. A fund with a slightly higher fee may track its index more closely or trade at a tighter spread, giving a better net result. Compare total cost and tracking over several years rather than looking at one number.
Do robo-advisers and unit trusts charge more than ETFs? They can, since many layer an advisory or platform fee on top of fund costs, while ETFs are often cheaper to hold. Charges vary, so ask for a full breakdown of every fee before you commit. A licensed adviser can help compare.
Official sources: MoneySense
Further reading: Understanding Thematic and Sector ETFs · Irish-Domiciled ETFs Explained for Singapore Investors