
If you have recently moved from the mainland to Singapore, you probably already know the e-CNY digital yuan, and this guide looks at what it means for a Singapore resident who still travels home, sends money to family, or keeps ties across the border. Back home you may have tapped the e-CNY wallet at a metro gate or a supermarket till. In Singapore the day to day picture is different, so it helps to set expectations clearly before you assume the same habits will carry over.
This is general information only. It is not financial advice, and it does not tell you to hold, spend, or avoid any currency. Rules, availability, and supported wallets change often, so always confirm the current position through official channels and your own bank before you rely on anything here.
What e-CNY Actually Is
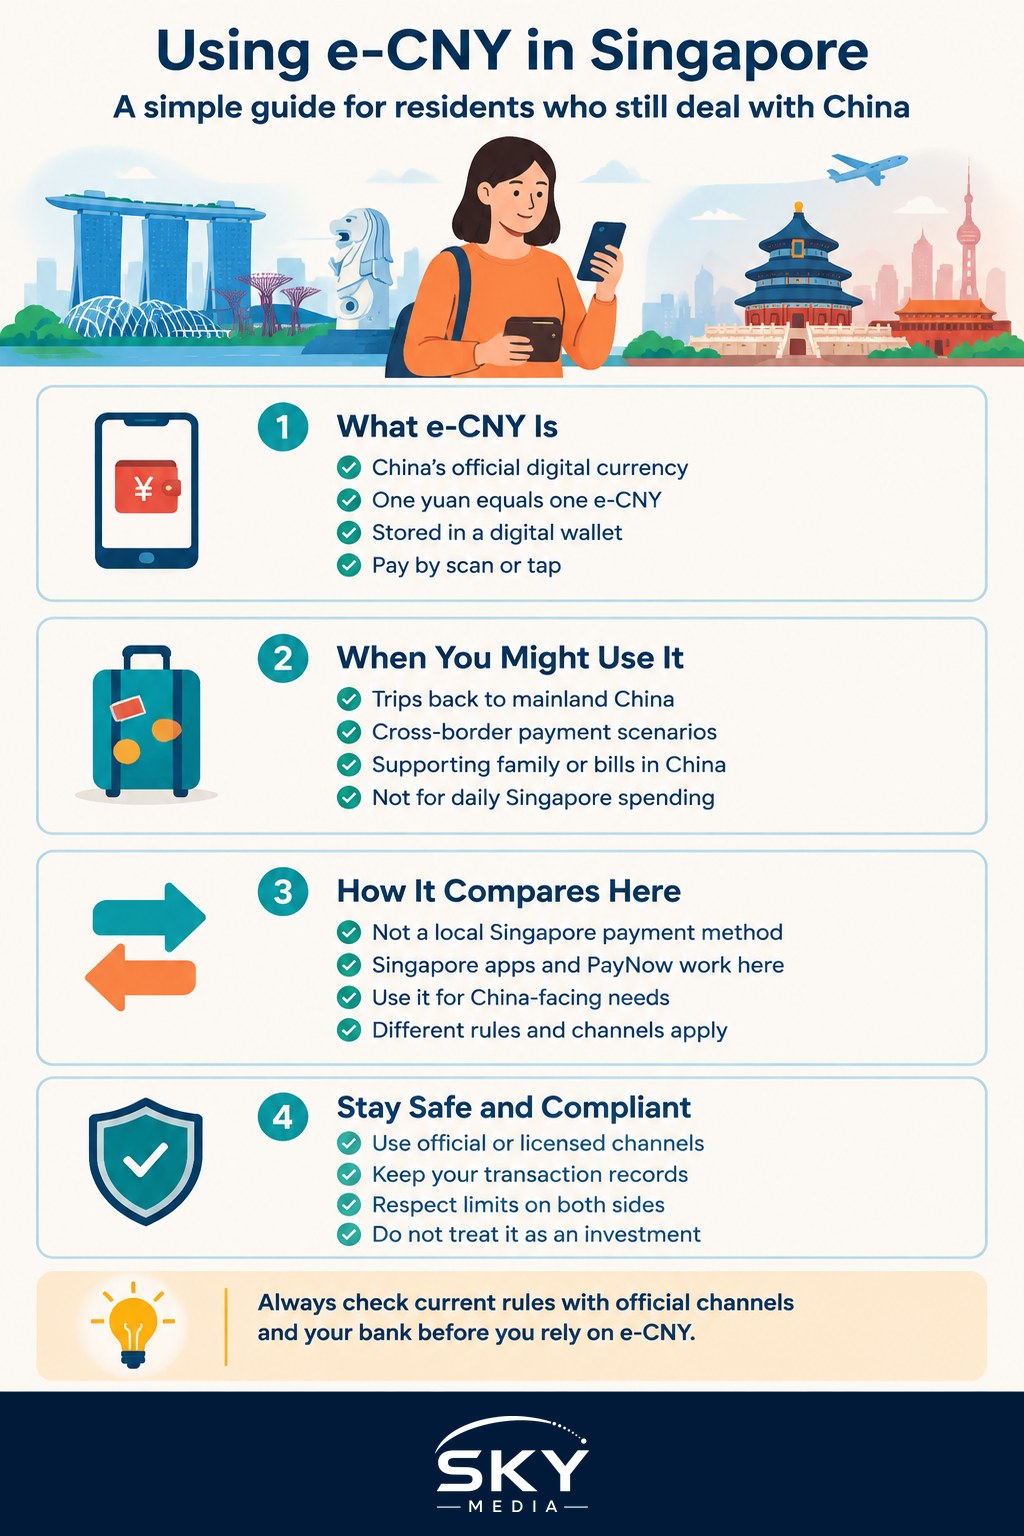
The e-CNY is the digital form of China’s official currency, issued by the central bank. It is not a private coin and not a speculative crypto token. One unit of e-CNY is meant to be the same as one yuan in physical notes. You hold it in a digital wallet, usually inside an app, and you can pay by scanning a code or tapping a phone at a participating merchant.
For a newcomer the key mental shift is this. In China the e-CNY sits alongside the private wallets you already use, and acceptance in the big cities has grown steadily. It is designed for everyday small payments, and it can work in settings where a signal is weak. That is the home context. It does not automatically mean the same convenience follows you to Singapore.
You should treat the e-CNY as one option among several for the specific moments when you are dealing with China, rather than a replacement for how you pay locally in Singapore. Keeping that boundary clear will save you confusion later.
When a Singapore Resident Might Use It
There are a few realistic situations where the digital yuan comes up for someone living here.
The most common is a trip back to the mainland. If you visit family, handle property, or take a work trip, you may want a China facing payment method ready before you land. Setting up or topping up a wallet through a proper channel, rather than on the day at a busy counter, tends to be smoother.
A second situation is cross border activity. Interest in using the e-CNY for tourism spending and for certain cross border pilots has been growing, and some banks and payment providers have explored links that touch our region. Whether any specific service is open to you as a Singapore resident, and under what limits, depends entirely on the current pilot terms and on the bank offering it. This is exactly the kind of detail that shifts, so check it fresh each time.
A third situation is simply keeping ties. You may support relatives, settle a recurring bill in China, or keep a small home currency float. The e-CNY may or may not be the most practical tool for that compared with an ordinary remittance, and the sensible move is to compare your options rather than assume.
What you should not do is treat the e-CNY as an investment. It is a currency, not a growth product. Anyone promising returns from holding digital yuan is not describing how an official currency works, and that should raise an immediate flag.
How It Compares With What You Use Here
The table below sets out, in general terms, how the digital yuan sits next to the everyday methods a Singapore resident relies on. Treat it as a orientation, not a rate sheet, because the specifics depend on your bank and the current rules.
| Feature | e-CNY (Digital Yuan) | Local Singapore Methods (bank app, PayNow, cards) |
|---|---|---|
| Issued by | China’s central bank | Your bank or card scheme, under Singapore regulation |
| Everyday use in Singapore | Not a local payment method | Designed for daily local payments |
| Main use for you | China facing trips and cross border scenarios | Rent, food, transport, bills in Singapore |
| Where to confirm rules | Official China channels and your bank | Your bank and the local scheme |
| Nature | Official currency in digital form | Local payment rails |
| Investment product | No | No |
The point of the comparison is not to rank one above the other. They serve different jobs. Your Singapore bank app and PayNow handle life here. The e-CNY, if you use it at all, is for the China facing corner of your finances.
Staying On the Right Side of the Rules
A few habits will keep you safe and compliant.
First, use official and licensed channels. Set up or top up any wallet through a recognised bank or the official app, never through a stranger, a chat group offer, or an unverified link. Newcomers are a favourite target for scams that dress themselves up as a helpful shortcut for handling money across the border.
Second, keep your records. If you move money between countries, keep the transaction details. This matters for your own clarity and for any question a bank may ask under its normal checks.
Third, respect the limits on both sides. Singapore and China each have their own rules on cross border money movement, and pilots often carry caps. Do not try to work around a limit through informal channels, because that is where real trouble starts.
Fourth, separate currency from speculation. Holding some yuan because you have genuine spending or family needs in China is ordinary personal finance. Chasing a promised gain from a currency is not, and it usually ends badly.
Finally, expect change. The digital yuan is still expanding, and cross border features are being tested rather than settled. What is true this year may be broader or narrower next year. Because of that, the single most useful thing you can do is verify the current position with an official source and your own bank each time you plan to use it, rather than relying on memory or on what a friend did last year.
Used with that mindset, the e-CNY is simply a modern form of the home currency you already understand, ready for the moments when your life still reaches back across the border. Keep it in its lane, use proper channels, and let your Singapore accounts do the everyday work of living here.
Explore more
How to Switch Banks in Singapore
How to Budget for Life in Singapore
Avoiding Common Scams and Fraud
Frequently Asked Questions
Can I top up an e-CNY wallet from my Singapore bank account? It depends on the wallet, the provider and your status, and rules for non-residents of China can be restrictive. Do not assume it will work like a local top-up. Check the wallet app’s official instructions and ask your own bank which services it supports.
How is e-CNY different from Alipay and WeChat Pay? Alipay and WeChat Pay are private payment apps, usually funded from bank accounts or cards, while the e-CNY is an official currency issued by China’s central bank in digital form. They can look similar at a till. The difference lies in who issues the money and the rules behind it.
How do I compare ways to send money to family in China? Compare fees, the exchange rate offered, transfer speed and any limits across bank transfers and licensed remittance services. Use a provider licensed in Singapore, and check MAS’s information if unsure. The cheapest headline fee is not always the best once the exchange rate is included.
What are the warning signs of a digital yuan scam? Be wary of anyone promising guaranteed returns, pushing you to act fast, or sending a link to an unofficial wallet or app. Only use official apps and recognised banks. If you suspect a scam, stop, tell your bank and report it to the police.
Why might my bank ask questions about transfers to China? Banks run routine checks on cross-border transfers, so a question about the purpose or source of funds is normal and not an accusation. Keep your transaction records and supporting documents, answer honestly, and ask the bank what it needs.
Further reading: Can You Use a Foreign E-Wallet in Singapore