
Trading a monthly payslip for your own name on every invoice is one of the biggest working decisions you can make in Singapore. Going from employee to self-employed in Singapore is exciting, but it also shifts a lot of responsibility onto your shoulders. No HR team files your tax, no employer tops up your CPF, and no one sets your hours except you. Done with a plan, the move can be freeing and financially healthy. Done on a whim, it can be stressful. This guide walks through what actually changes, how to prepare, and where to go for the official details.
What Really Changes When You Stop Being an Employee
As an employee, a lot happens quietly in the background. Your employer deducts and contributes CPF, your income tax is easy to track through your payslip, and you are covered by parts of the Employment Act. You also get paid whether or not a client is happy that week.
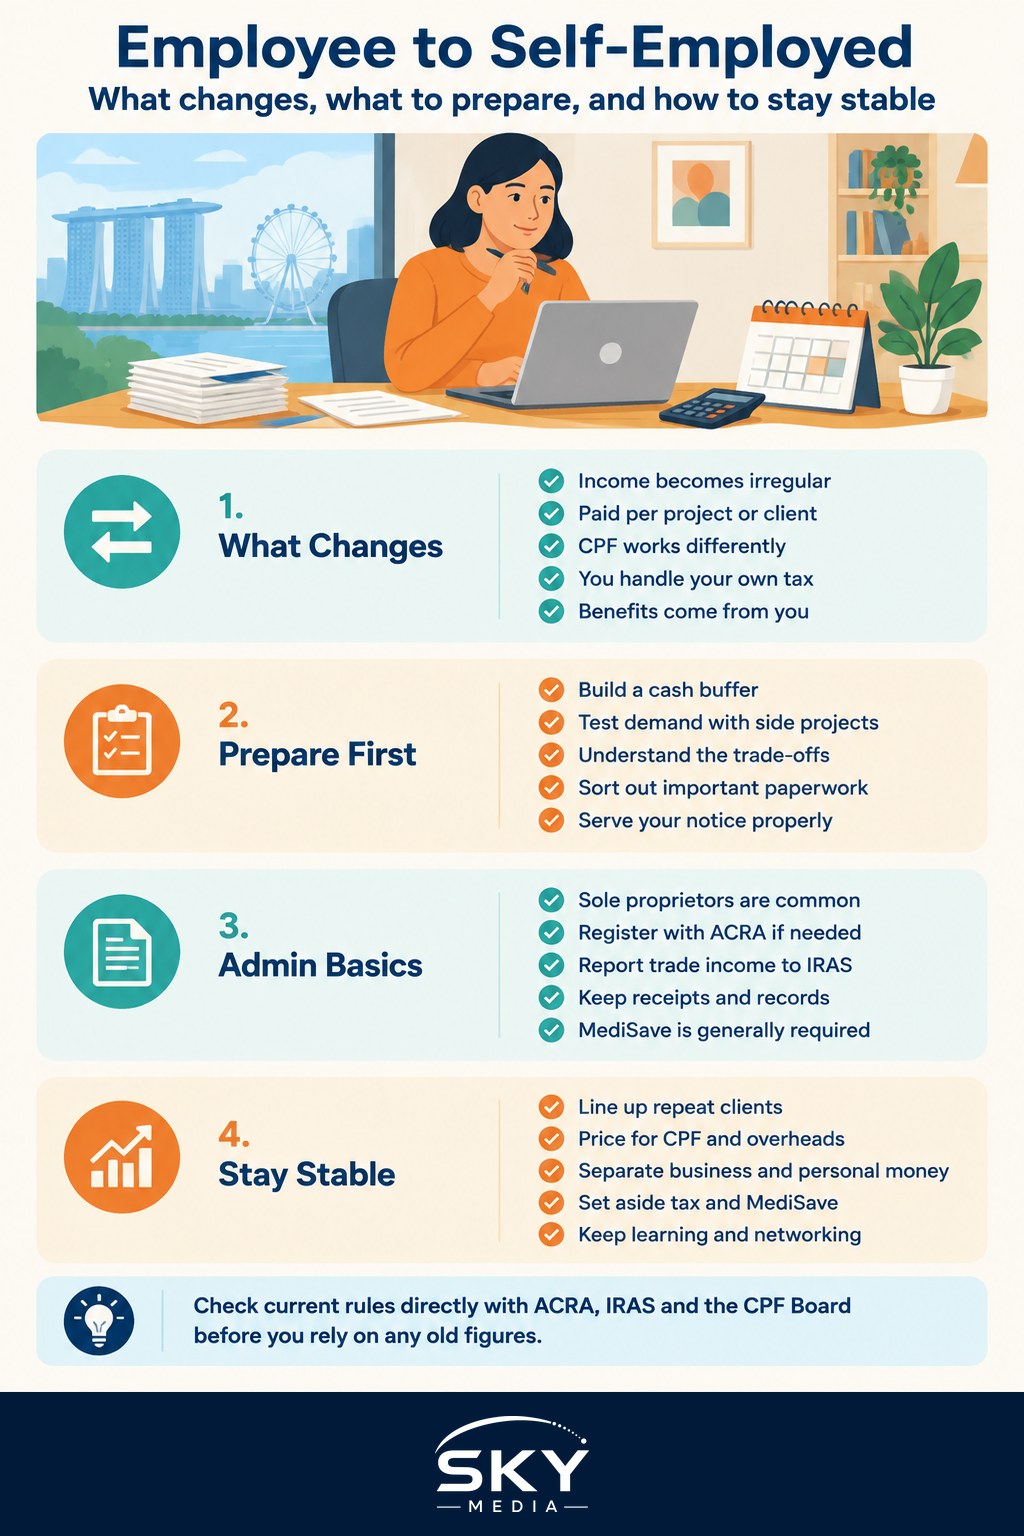
When you become self-employed, several of those safety nets change:
- Income becomes irregular. You are paid per project or per client, not per month.
- CPF works differently. Employer CPF contributions stop. As a self-employed person, MediSave contributions become your responsibility, and other CPF top-ups are voluntary.
- You handle your own tax. You declare business or trade income to IRAS rather than relying on an employer’s return.
- Employment Act protections shift. Many rules that cover employees do not apply the same way to someone running their own trade.
- You provide your own benefits. Leave, insurance, and downtime are all funded by you.
None of this should scare you off. It simply means the structure that an employer used to provide is now something you build for yourself.
Preparing Before You Hand in Your Notice
The strongest transitions usually start while you are still employed. Your current salary is the cheapest runway you will ever have, so use it wisely.
- Build a cash buffer. Aim for several months of essential expenses set aside before you rely fully on self-employed income. If you want a framework, our guide to building an emergency fund in Singapore is a good starting point.
- Test demand first. Take on a small side project or two so you know real clients will pay for what you offer. Our guide to starting a side hustle in Singapore covers doing this alongside a job.
- Understand the trade-offs. Read freelancing vs full-time in Singapore so you go in with clear eyes about stability, benefits, and control.
- Sort out the paperwork you rely on your employer for. Insurance, loans, and rental applications can be harder to arrange once you no longer have a fixed salary letter, so handle time-sensitive ones early.
- Serve your notice properly. Check your contract for the notice period and any clauses about clients or non-competition, and leave on good terms. Former colleagues and managers often become your first referrals.
A clean, planned exit protects both your reputation and your cash flow.
Registering and Getting the Admin Right
You do not always need a formal company to work for yourself. Many freelancers operate as sole proprietors, and some register a business name while others trade under their own name. If you plan to build a brand, hire, or work with larger clients, registering a business with ACRA may make sense. If you are unsure which structure fits, check the current rules and options directly on the ACRA website rather than assuming.
On tax, self-employed people report their trade income to IRAS and may deduct allowable business expenses, so keeping clean records from day one matters. Set up a simple system to track what you earn and spend, and keep your receipts. For a fuller walkthrough, see our guide to taxes for the self-employed in Singapore, and always confirm current filing requirements and deadlines on the IRAS website.
CPF also changes. As a self-employed person, MediSave contributions are generally required based on your income, and you can make voluntary contributions to your other CPF accounts if you choose. Because the exact rates and thresholds are set by the authorities and can change, confirm your current MediSave obligations on the CPF Board website rather than relying on old figures.
This is general information, not legal or financial advice. Your obligations depend on how you structure your work and the current rules, so verify the specifics with ACRA, IRAS, and the CPF Board.
Employee Versus Self-Employed at a Glance
Seeing the two side by side makes the switch easier to plan for.
| Area | As an Employee | As Self-Employed |
|---|---|---|
| Income | Fixed monthly salary | Varies by client and project |
| CPF | Employer and employee contributions | MediSave required; other CPF voluntary |
| Tax | Simple, tied to your payslip | You declare trade income to IRAS |
| Leave and benefits | Provided by employer | Funded by you |
| Job security | Contract and notice terms | Depends on your client pipeline |
| Admin work | Mostly handled for you | You handle registration and records |
Use this as a checklist. Each row that used to be your employer’s job is now something you plan for yourself.
Building Stability Once You Are on Your Own
The first few months set the tone, so treat stability as a project in itself. Line up a base of repeat clients before you leave if you can, since predictable work smooths out the lumpy months. Price your work so it covers not just your time but also your own CPF, insurance, taxes, and unpaid admin days; our guide to pricing your freelance services in Singapore can help you set rates that are sustainable rather than just cheap.
Cash flow discipline is the other half. Separate your business and personal money, set aside a portion of every payment for tax and MediSave, and pay yourself a steady amount rather than spending each windfall. For a self-employed version of budgeting and protection, see our guide to financial planning for freelancers in Singapore.
Finally, keep investing in skills and relationships. SkillsFuture SG supports ongoing learning, and staying visible through your network keeps new work coming without a hard sell. Going solo does not mean going it alone; it means choosing who you work with and how you grow.
Explore More
If you are still weighing the leap, read freelancing vs full-time in Singapore and try starting a side hustle in Singapore before you commit. Once you are ready to earn, our guides to finding clients as a freelancer in Singapore and freelancing in Singapore will help you build a steady pipeline.
Frequently Asked Questions
Can I still contribute to my CPF Ordinary Account after becoming self-employed? Yes, you can make voluntary contributions to your CPF accounts, which may be allocated across them, on top of the compulsory MediSave contributions. This helps keep your housing and retirement savings growing without an employer. Voluntary contributions may also qualify for tax relief within limits, so check the current rules with the CPF Board and IRAS.
Should I register a sole proprietorship or a private limited company? A sole proprietorship is simpler and cheaper to run, but you are personally liable for business debts. A private limited company separates your personal assets from the business and may suit those planning to hire or take on larger contracts, though it involves more compliance. Compare both on ACRA’s website and consider an accountant’s advice.
Can my former employer stop me from working with its clients? Possibly, if your contract has a non-solicitation or non-compete clause, though such restrictions must generally be reasonable in scope and duration to be enforceable. Read the clause carefully and avoid approaching former clients until you are sure. For anything unclear, get advice from a lawyer before you start.
How do I get health insurance once I am no longer on a company plan? Your MediShield Life coverage continues regardless of employment, but group insurance from your employer usually ends when you leave. Many self-employed people buy an Integrated Shield Plan or other personal cover, ideally before resigning in case health conditions affect underwriting later. A licensed adviser can help compare options.
Is it better to start self-employment gradually or quit cleanly? Starting part-time alongside your job lowers risk and proves demand, but check your contract for restrictions on outside work first. Quitting cleanly gives you full time to build the business but needs a bigger buffer and a clearer pipeline. Many people test on the side, then leave once repeat clients cover their basic expenses.
Further reading: Home Loans for Self-Employed and Commission Earners in Singapore · Tax for the Self-Employed and Freelancers