
Singapore’s housing market is watched closely by buyers, sellers and policymakers alike, and one reason it stays relatively stable is a toolkit the government reaches for when prices or borrowing look like they are running too hot. These tools are the property cooling measures singapore residents read about whenever the market makes headlines. They are not one rule but a set of levers that raise the cost or lower the borrowing power of certain purchases, aimed at keeping housing affordable and the market steady. This guide explains what the main measures are, why they exist, who they tend to affect, and why you should always confirm the current rates and rules with the official agencies. It is general information, not financial or legal advice.
Why Singapore Uses Cooling Measures
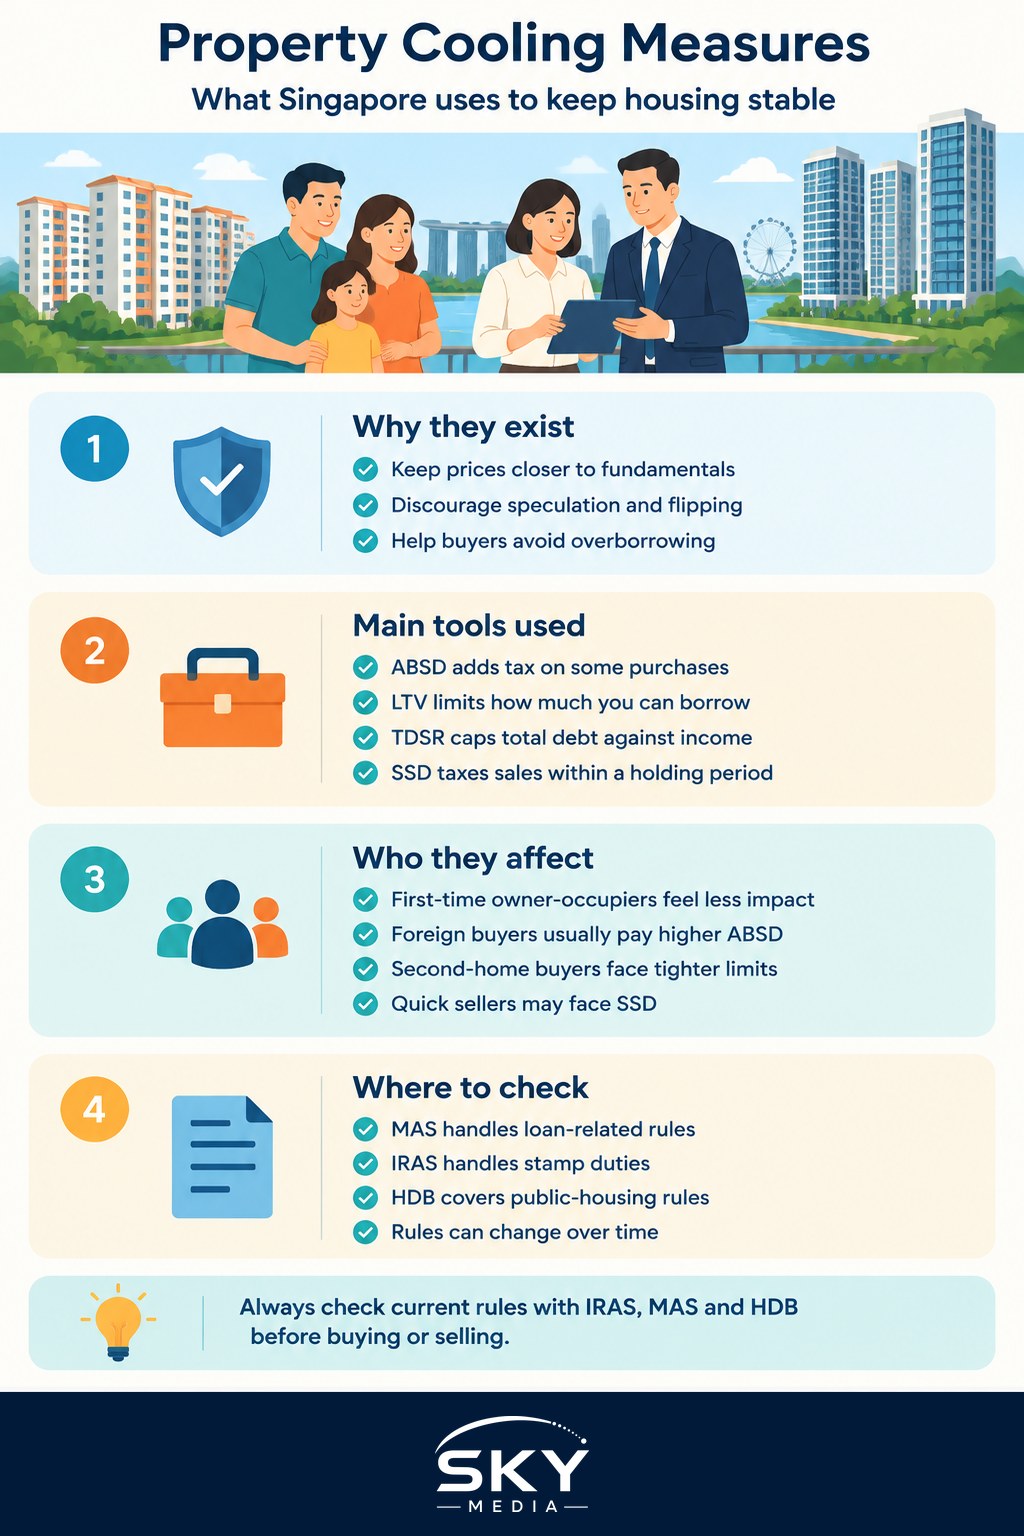
Housing is both a basic need and, for many, their largest asset, so the government treats market stability as a matter of national interest. Property cooling measures exist to keep home prices broadly in line with economic fundamentals, to discourage speculation and short-term flipping, and to make sure buyers do not borrow more than they can safely repay.
The concern is straightforward. If prices rise far faster than incomes, homes drift out of reach for ordinary families, and a market fuelled by cheap credit and speculation can swing sharply, hurting owners and the wider economy if it corrects. Cooling measures lean against that. By adding cost to purchases that are more speculative and by capping how much people can borrow, they aim for a market that grows steadily rather than in booms and busts.
Several agencies share the work. The Monetary Authority of Singapore (MAS) sets the lending rules, the Inland Revenue Authority of Singapore (IRAS) administers the stamp duties, and the Ministry of National Development and HDB shape policy for public housing. Because the levers span more than one body, the details live on more than one official site.
The Main Tools, in Plain Terms
The cooling toolkit is usually described through a handful of core measures. Each works differently, and they are often used together for a combined effect.
- Additional Buyer’s Stamp Duty (ABSD). An extra tax on top of the standard buyer’s stamp duty, charged on residential purchases. It is typically higher for those buying additional properties and for buyers who are not citizens, which raises the cost of speculative and multiple-property purchases.
- Loan-to-Value (LTV) limits. A cap on how much of a property’s price you can borrow, meaning the rest must come from your own funds as a down payment. Lower limits usually apply to second and subsequent housing loans.
- Total Debt Servicing Ratio (TDSR). A framework that caps how much of a borrower’s monthly income can go towards servicing all debts, so that a home loan does not stretch a household beyond what it can afford.
- Seller’s Stamp Duty (SSD). A tax charged when a residential property is sold within a set holding period after purchase, designed to discourage quick, speculative flipping.
For public housing, a related limit, the Mortgage Servicing Ratio, caps the share of income that can go towards an HDB or executive condominium loan specifically. Together these measures shape both what buyers pay upfront and how much they can borrow.
How the Main Measures Compare
The table below sets out what each core measure does in general terms. It deliberately avoids quoting rates or percentages, because those are adjusted over time; check the official agencies for the figures that apply now.
| Measure | What it does | Administered by |
|---|---|---|
| Additional Buyer’s Stamp Duty (ABSD) | Adds a tax on certain residential purchases | IRAS |
| Loan-to-Value (LTV) limit | Caps how much of the price can be borrowed | MAS |
| Total Debt Servicing Ratio (TDSR) | Caps total debt repayments against income | MAS |
| Seller’s Stamp Duty (SSD) | Taxes sales made within a holding period | IRAS |
Who the Measures Affect
Cooling measures are targeted rather than blanket, so they land differently depending on the buyer. In general, first-time buyers purchasing a single home to live in feel the lightest touch, since the measures are designed to keep that path open. The weight falls more heavily on other groups.
- Foreign buyers typically face the highest additional stamp duty, reflecting a policy preference to prioritise homes for citizens.
- Buyers of a second or subsequent property, including investors and those upgrading before selling, generally pay higher ABSD and can borrow less under tighter LTV limits.
- Highly leveraged borrowers are limited by TDSR, which prevents taking on a loan that would consume too much of their income.
- Short-term sellers who dispose of a property soon after buying may be caught by SSD.
There are usually reliefs and transitional arrangements in specific situations, such as certain remissions for particular buyer types or timelines, but these come with conditions. Because the categories and any concessions are defined precisely in the rules, anyone affected should read the current official guidance rather than rely on a general summary.
Planning Around the Measures Sensibly
- Size your loan against the caps, not your hopes. TDSR and MSR mean your income, not the asking price, often sets your ceiling. A mortgage broker or your bank can run the real numbers.
- Save for the down payment the LTV limits imply, including the portion that must be in cash. Remember stamp duties are paid on top and cannot be borrowed.
- Think about your holding period. If there is any chance you will need to sell soon, factor in SSD before you buy.
- Check whether CPF can help with the down payment or instalments, within its own limits. See using CPF for your monthly instalments.
- Confirm every figure at the time you buy, because a measure may have moved since you started looking.
Do Not Try to Game the System
Because the measures add cost, some buyers are tempted by arrangements that appear to sidestep them, such as unusual ownership splits or putting a purchase in someone else’s name. This is risky ground. Structuring a purchase mainly to avoid ABSD or other duty can amount to tax avoidance, and IRAS has pursued arrangements it views as artificial, with back-duty and penalties as the result. Frame any such idea neutrally and get proper legal and tax advice before going anywhere near it, rather than acting on what a forum or an agent claims works.
Property can fall as well as rise, and the cooling measures are partly there to remind everyone of that. Nothing here is a prediction that prices will move one way or another, and no home is a guaranteed good buy.
Why the Rules Keep Changing
A defining feature of cooling measures is that they are adjusted over time. The government reviews the market and tightens or eases the levers as conditions shift, tightening when prices or borrowing look overheated and easing when the market cools. This is deliberate: the tools are meant to respond to the market, not to stay fixed.
The practical consequence for you is simple. Any rate, threshold or holding period you read in an older article, a forum post or a property listing may already have changed. A single adjustment can alter how much stamp duty you owe or how large a loan you qualify for, which can move a purchase by a significant sum.
So treat specifics as something to verify, not memorise. The reliable sources are IRAS for the stamp duties (ABSD, BSD and SSD), MAS for the lending rules (LTV and TDSR), and HDB for public-housing loan and eligibility rules. Before committing to a purchase or sale, confirm the current figures there, and for a large decision, consider professional advice tailored to your situation.
Where to Check the Current Rules
Because the property cooling measures change with conditions, the value of this guide is the map, not the numbers. For the figures and rules that apply on the day you buy or sell, go to the source: MAS for loan-related measures such as TDSR, MSR and LTV, IRAS for ABSD, buyer’s stamp duty and SSD, HDB for flat and executive condominium rules, and URA for private property and market data. For anything touching your personal legal or tax position, speak to a conveyancing lawyer or a tax adviser, and verify agents on the CEA public register. Get those checks done early, and the cooling measures become a set of guardrails you can plan around rather than a nasty surprise at signing.
The Bottom Line
Property cooling measures are Singapore’s way of steering the housing market towards stability and affordability, using stamp duties like ABSD and SSD alongside borrowing limits like LTV and TDSR. They are targeted, so they weigh most on foreign buyers, multiple-property purchasers, heavily leveraged borrowers and quick sellers, while keeping the path clearer for those buying a first home to live in. Understanding what each tool does helps you plan, but because the rates and rules are adjusted over time, always check the current position with IRAS, MAS and HDB before you act.
Explore more
To see how these market tools fit alongside the public-housing system, read our guide to HDB housing policy explained. And if you are weighing a first home purchase, our overview of housing grants explained covers the support that can help with the upfront cost.
Frequently Asked Questions
Do cooling measures apply if I am buying an HDB flat? Some do, though the main constraints for flats are HDB’s own loan and eligibility rules and the Mortgage Servicing Ratio. The heavier stamp duties and borrowing limits tend to bite when you already own property or are buying private homes. Check HDB, IRAS and MAS for your situation.
Are permanent residents treated the same as citizens under the measures? No. Buyer status matters, and PRs and foreigners generally face higher additional stamp duty than citizens buying a first home. Rates differ by status and by how many properties you own, and they change from time to time. Check the latest figures on the IRAS website.
Will I pay ABSD if I buy a new home before selling my old one? You may have to pay it upfront, because the new purchase counts as an additional property at the time. Some situations allow a remission or refund, but only if you meet conditions and timelines. Confirm the rules with IRAS and speak to a conveyancing lawyer before committing.
How long must I hold a property to avoid Seller’s Stamp Duty? It depends on the holding period set in the current rules, which has been adjusted before. SSD applies when you sell within that window after purchase, so check the latest period on the IRAS website before buying. If you might need to sell early, factor the duty into your plan.
How much cash should I have ready beyond the home loan? More than most buyers expect. The loan-to-value limit means part of the price must come from your own funds, and stamp duties are paid on top and cannot be borrowed. Ask your bank or a mortgage broker to run your numbers using current rules.
Official sources: IRAS