
Bringing an animal into your home is a joy, but budgeting for a pet singapore residents plan to keep for years is a serious commitment that deserves honest sums. A pet is not a one-off purchase. It is a living companion that brings recurring costs across its whole life, from daily food to routine vet visits and the occasional unexpected bill. Thinking through the numbers before you adopt or buy helps ensure you can care for the animal properly for the long haul. This article is general information only and not financial advice, so please plan around your own circumstances and check current requirements with NParks and AVS.
Upfront Costs to Expect
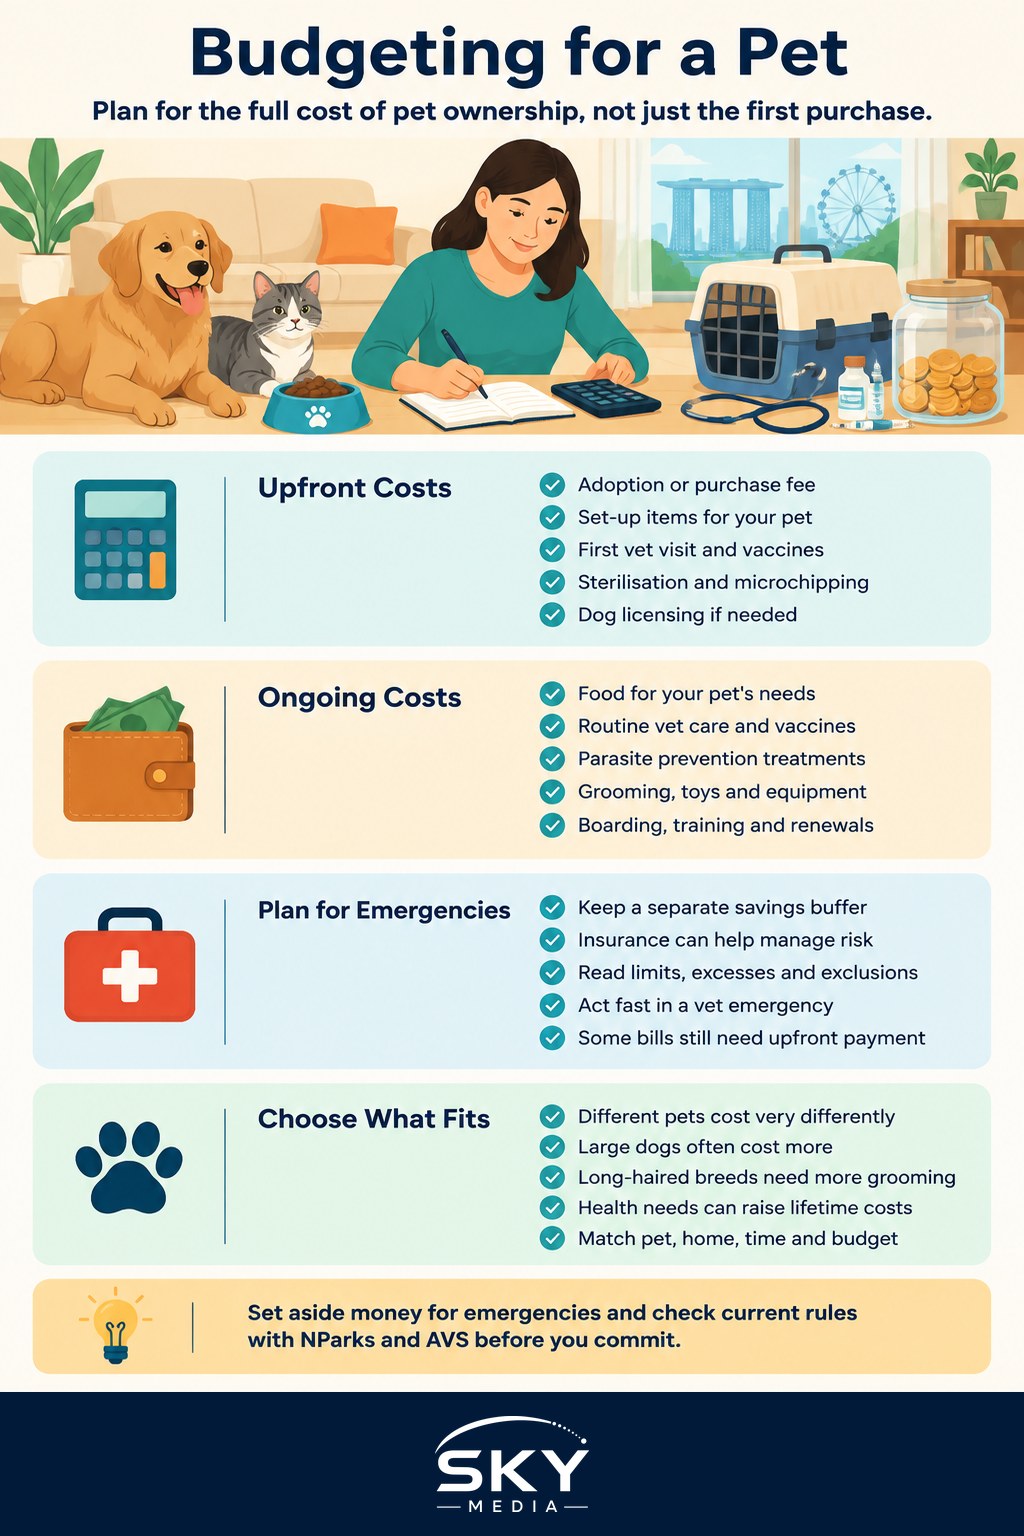
The first costs arrive before your pet has settled in. Depending on the animal and where it comes from, there may be an adoption fee or purchase price. On top of that sit the setup essentials, which differ by species but often include a carrier or crate, bedding, bowls, a collar or harness, a tank or cage, litter trays, toys and grooming tools. For dogs, licensing is a legal requirement, and this is administered through NParks and its Animal and Veterinary Service, known as AVS.
Early veterinary care is another upfront cost. Vaccinations, a health check, sterilisation and microchipping are common starting points, and responsible ownership usually means arranging these soon after your pet arrives. Some of these, such as microchipping and sterilisation, may also tie in with licensing conditions, so it is worth checking the current rules rather than assuming.
These initial costs can be significant, and they vary widely by the type and size of animal. A small caged pet has very different needs from a large dog. Before committing, list out the specific setup and early-care items your chosen pet will need, and price them realistically so the first few months do not blindside your budget.
Ongoing Costs Over a Pet’s Life
The larger financial picture is the ongoing cost, repeated month after month for many years. Food is the most obvious, and quality diets suited to your pet’s size, age and health can add up. Beyond food come routine veterinary care and vaccinations, parasite prevention such as flea, tick and worm treatments, and grooming, which for some breeds is frequent and not cheap.
Then there are the costs that come and go. Boarding or pet-sitting when you travel, replacement toys and equipment, training classes, and licence renewals for dogs all recur over time. Pet insurance is worth considering too, as it can help with the cost of accidents or illness, though you should read what any policy covers and excludes before relying on it. Insurance is a tool to manage risk, not a guarantee that every bill is covered.
The single most important habit is to plan for the whole lifespan, not just the first exciting year. Many pets live for well over a decade, and their needs, and costs, often rise as they age. Older animals may need more frequent vet visits, special diets or ongoing medication. Budgeting realistically means assuming costs across the full life of the animal, not only while it is young and healthy.
A Simple Cost Category Overview
- Upfront: Once. Examples include adoption or purchase, first vet visit, sterilisation, equipment, and licensing.
- Recurring: Monthly. Examples include food, litter, waste bags, treats, and parasite prevention.
- Periodic: Yearly. Examples include health checks, vaccinations as advised, licence renewal, and grooming.
- Unexpected: Anytime. Examples include illness, injury, emergency vet care, and dental work.
An Illustrative Yearly Budget
The figures below are deliberately hypothetical and rounded. They are not real prices, and they are not a quote from any vet, insurer or shop. They exist only to show the categories of ongoing cost, so please do not treat them as accurate amounts for your own pet.
Imagine an invented yearly budget for a made-up medium-sized pet. Here is roughly how the ongoing costs might be shared across categories in this illustration.
| Category | Illustrative yearly amount | Notes |
|---|---|---|
| Food | 800 | Varies by size and diet |
| Routine vet and vaccines | 400 | More for older pets |
| Grooming and supplies | 300 | Depends on breed |
| Insurance | 500 | Read what it covers |
| Boarding when away | 200 | Only when travelling |
| Total | 2,200 | Excludes emergencies |
Notice that this illustrative total deliberately excludes emergencies. A single accident or serious illness can cost far more than the whole year’s routine budget, which is exactly why a separate cushion matters.
Build an Emergency Vet Fund
Even with insurance, an emergency vet fund is one of the wisest things a pet owner can set up. Accidents and sudden illnesses happen, and specialist treatment or surgery can be expensive and needed at short notice. Insurance may reimburse part of a bill, but often after you have paid upfront, and policies come with limits, excesses and exclusions. A dedicated pot of savings means you can act quickly in a crisis without agonising over money or reaching for costly debt.
Building the fund can be gradual. Setting aside a small amount regularly into a separate savings account, and leaving it untouched for genuine emergencies, turns a frightening unexpected bill into a manageable one. Think of it as part of the true cost of responsible ownership rather than an optional extra. Combined with suitable insurance, a cash buffer gives your pet the best chance of prompt care and gives you peace of mind.
Before you commit to any animal, add all of this together honestly. Upfront setup, yearly ongoing costs, licensing, insurance and an emergency fund make up the real price of ownership. If the full picture is affordable and sustainable for you, a pet can be a wonderful part of life. If it is a stretch, it is kinder to both of you to wait or to choose an animal whose needs fit your budget.
Planning Beyond Your Emergency Fund
Two sensible strategies help with unexpected medical costs. First, build a dedicated savings buffer for your pet so a sudden vet bill does not become a crisis. Even a small amount set aside each month adds up over time. Second, look into pet insurance and understand what it does and does not cover, including any waiting periods and exclusions, before deciding whether it suits your situation. Neither approach replaces the other, and many owners use a combination.
Knowing where to go in a crisis is part of planning too. Familiarise yourself in advance with emergency vet care in Singapore so you are not searching for options during a stressful moment. Red flag signs such as trouble breathing, collapse, seizures, a bloated hard abdomen, or refusing to eat or drink mean you should get to an emergency vet right away.
The Takeaway
Budgeting for a pet means looking well beyond the adoption fee. Upfront setup and early vet care, steady ongoing costs for food, health and grooming, dog licensing through NParks and AVS, and a separate emergency vet fund all form part of the true cost. Insurance can help manage risk but does not replace planning or a cash cushion. Price it all honestly across the animal’s full lifespan, and check current requirements with the authorities. Done thoughtfully, budgeting well is simply part of being a responsible and loving owner.
Matching Your Pet to Your Budget and Lifestyle
The most caring financial decision happens before you bring an animal home. Different pets carry very different lifelong costs. A large, active dog generally costs more to feed, groom, and care for than a small one. Long haired breeds need more grooming. Some breeds are prone to particular health issues that can add to lifetime costs, so research honestly and speak to a vet or a responsible source.
Choosing an animal whose needs match your home, your time, and your finances is the foundation of responsible ownership. If you are still deciding, our guide to getting a pet in Singapore walks through the bigger picture and helps you set expectations before you commit.
Explore more
Budgeting in Singapore
Building an Emergency Fund
Insurance Basics in Singapore
Setting Financial Goals
Frequently Asked Questions
Which pets cost the least to keep? Smaller animals with simpler needs generally cost less than large, long-haired or high-maintenance ones, though no pet is free. Food, vet care, equipment and unexpected illness still apply. Research the species and breed honestly, and ask a vet what a typical lifetime of care involves.
Is pet insurance worth buying? It can help with accident or illness bills, but it is a way to manage risk rather than a guarantee. Read what the policy covers, its exclusions, waiting periods and limits, and note that claims are often paid after you have already covered the bill. Many owners combine insurance with a savings buffer.
Do I need to register or license my pet? Dogs must be licensed, which is administered through NParks and its Animal and Veterinary Service. Other animals have their own rules, and some cannot be kept at all. Check the current requirements with NParks and AVS before you adopt, rather than relying on hearsay.
Can I leave my pet at home when I travel? Not for long. Pets need regular feeding, water, company and sometimes medication, so arrange boarding or a trusted pet-sitter and include that cost in your yearly budget. Last-minute arrangements are stressful for you and your animal, so plan ahead of holidays.
What if I cannot afford my pet any more? Speak to your vet early, as they may suggest cheaper treatment options or ways to manage costs. If you truly cannot cope, contact a reputable animal welfare group about rehoming rather than abandoning the animal. Abandonment can be an offence, so seek help before things reach a crisis.