
Fitting out a new home costs real money, and few of us pay for everything upfront. A renovation loan in Singapore is one of the most common ways to spread that cost, but it is not the only route, and it is not right for everyone. This guide explains how the main financing options generally work and what to weigh up, so you can have an informed conversation with your bank. It is general information, not financial advice.
Understanding what a renovation loan is
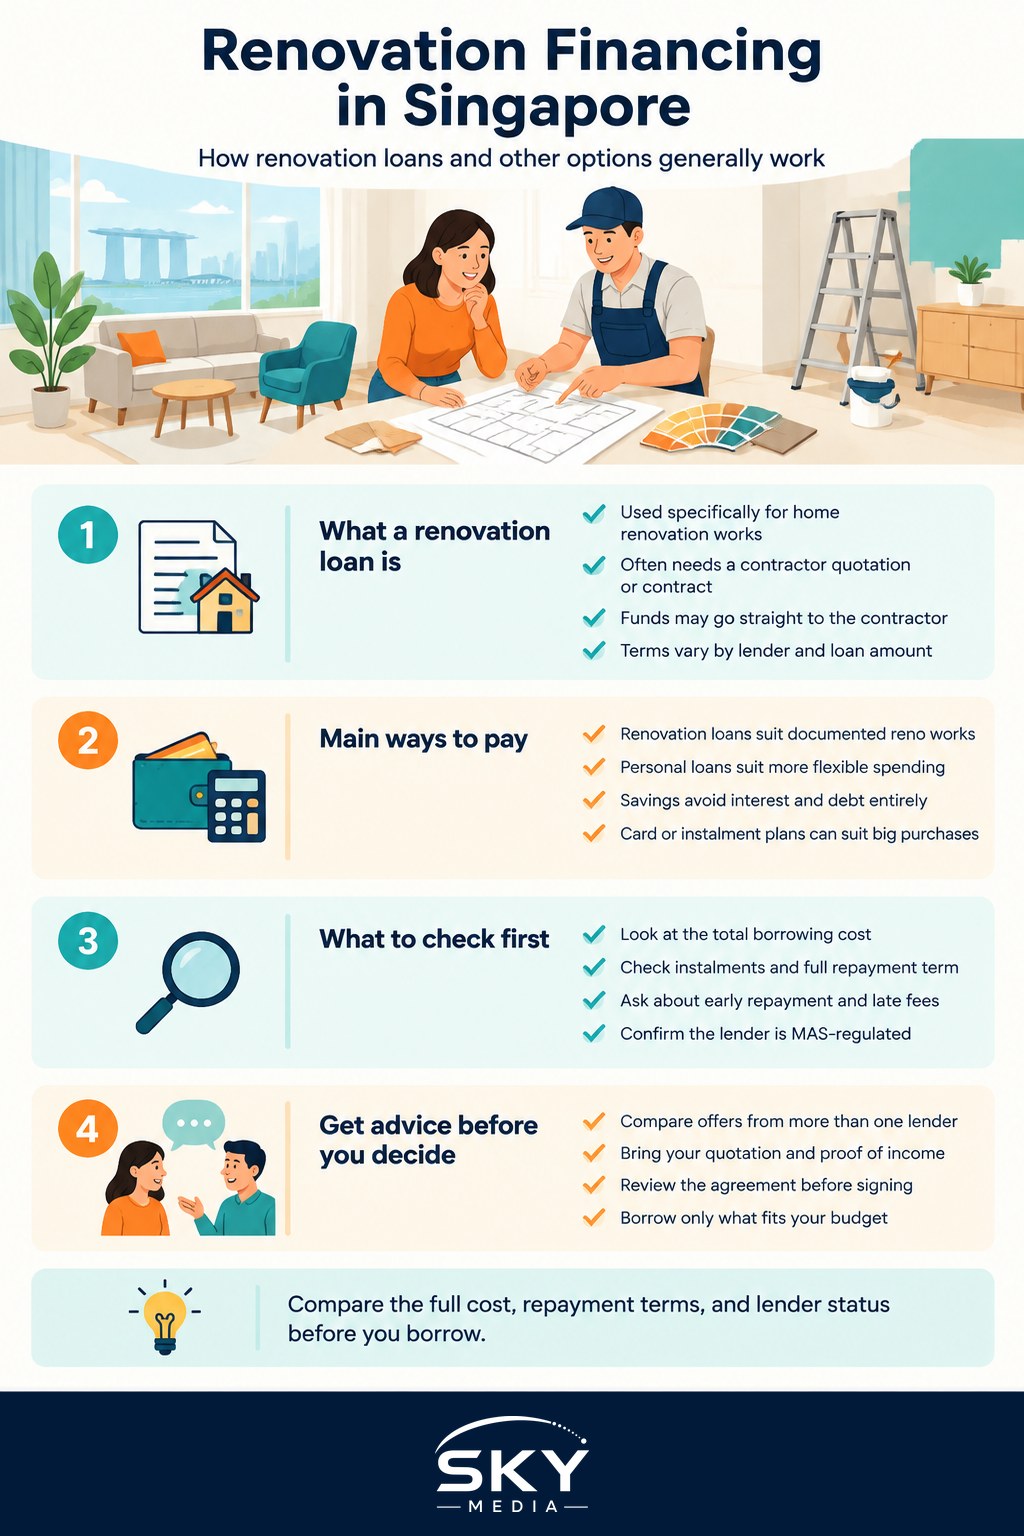
A renovation loan is a form of borrowing offered by banks and financial institutions specifically to fund home renovation works. Unlike a general personal loan, it is usually tied to your renovation, so lenders often ask for a signed quotation or contract from your renovation contractor and may pay the funds directly to that contractor rather than into your account.
Because they are earmarked for renovation, these loans tend to have their own eligibility criteria, borrowing limits, and repayment terms set by each lender. Limits are often expressed as a multiple of your monthly income up to a capped amount, and repayment periods typically run over a few years. The exact figures, interest rates, and fees differ between institutions and change over time, so treat any number you read online as illustrative only and confirm the current terms directly with the bank.
Renovation loans in Singapore are offered by MAS-regulated banks and licensed institutions. Sticking to regulated lenders protects you and gives you recourse if something goes wrong. Be wary of any lender offering terms that seem too good, and never borrow from an unlicensed moneylender.
How it differs from a home loan
The two are easy to confuse, so it is worth being clear. A home loan finances the purchase of the property itself: it is secured against the property, involves large sums and stretches over many years. A renovation loan is generally smaller, unsecured and repaid over a shorter term, and lenders often pay your contractor directly rather than handing the cash to you.
The interest rate, loan amount, tenure and eligibility criteria are all set by the lender, within the wider lending rules overseen by the Monetary Authority of Singapore, and these can change over time. Always confirm the current terms directly with the bank you are considering. If you want the bigger picture first, our guide to how to budget for a home renovation helps you decide how much you actually need to borrow.
The main ways people finance a renovation
A dedicated renovation loan is popular, but it sits alongside several other options. Which suits you depends on how much you need, how quickly you can repay, and what you qualify for.
- Renovation loan. Purpose-built for reno works, often with competitive rates compared with unsecured borrowing, but tied to documented renovation costs and sometimes capped below what a full home makeover needs.
- Personal loan or line of credit. More flexible in how you spend the money and quicker to arrange, but rates and fees vary widely, so compare carefully.
- Savings. Paying from cash you already have avoids interest and debt entirely. Many people fund part of the reno this way and borrow only the balance.
- Credit cards or instalment plans. Some contractors and retailers offer instalment options for furniture or appliances. These can be convenient but may carry high effective costs if not cleared on time.
Many households use a mix, for example savings for the bulk of the work and a renovation loan for a specific large item. There is no single right answer.
Comparing common financing options
The table below sets out the general character of each route. It is a broad guide only, not a statement of any lender’s actual terms, which you must verify yourself.
| Option | Generally suits | Typical trade-off | Where to confirm terms |
|---|---|---|---|
| Renovation loan | Documented reno works within the loan cap | Tied to contractor quotes; capped amount | MAS-regulated banks |
| Personal loan or credit line | Flexible spending or amounts above the reno cap | Rates and fees vary; compare closely | Licensed banks and institutions |
| Own savings | Any budget, if funds allow | No interest, but reduces your cash buffer | Your own financial plan |
| Instalment or card plans | Individual big-ticket purchases | Can be costly if not cleared promptly | Retailer or card issuer |
Use the table to shortlist, then get precise, current quotes before deciding. The best option is the one you can comfortably repay without straining your monthly budget.
How a renovation loan differs from a personal loan
A renovation loan is earmarked for home improvement works, while a general personal loan can be used for any purpose. That restriction is exactly why the renovation loan often carries a lower effective interest rate. The key differences:
- Purpose: home renovation only, versus any purpose for a personal loan.
- Interest rate: often lower for a renovation loan, generally higher for a personal loan.
- Disbursement: a renovation loan may be paid to your contractor, while a personal loan usually goes to you.
- Documentation: a renovation loan often needs a renovation quote or invoice, while a personal loan has fewer conditions.
Because it is cheaper but restricted, a renovation loan is usually the better choice when the money is genuinely for renovation. It is generally not meant for loose furniture or appliances, so plan your cash separately for those.
What to check before you borrow
Borrowing to renovate is a serious commitment, so slow down and read the fine print. A few checks make a real difference:
- The total cost of borrowing, not just the headline rate. Ask for the effective interest rate and any processing fees, so you can compare offers fairly. A low advertised rate can look different once fees are added.
- The repayment schedule. Know the monthly instalment and the full term, and be honest about whether it fits your budget alongside your mortgage and other commitments.
- Early repayment and late payment terms. Check whether repaying early triggers a penalty and what happens if you miss a payment.
- Your total debt position. Lenders assess your existing obligations, and regulated limits apply to how much you can borrow relative to income. Do not overextend.
- The lender’s standing. Confirm the institution is MAS-regulated and read the actual loan agreement rather than relying on a salesperson’s summary.
Build a realistic renovation budget first, with a contingency buffer for surprises that often appear once works begin, then decide how much, if anything, you actually need to borrow. Borrowing less is almost always the safer path.
Eligibility and What Lenders Assess
Renovation loans are usually aimed at Singapore Citizens and Permanent Residents who own or are buying the property being renovated, whether an HDB flat or private housing. Most lenders also set a minimum age and a minimum annual income, and want to see that you can service the repayments alongside your other commitments. Criteria differ between lenders and change over time, so treat this as what lenders typically look at and confirm the exact requirements with the lender you approach.
- Proof of income, commonly recent payslips, CPF contribution history, or your latest Notice of Assessment from IRAS if you are self-employed.
- Property and ownership details, since the loan is tied to the home being renovated.
- A renovation quotation or contract showing the scope and cost the loan is meant to cover.
- Your existing debt commitments, weighed against your income before an amount is approved.
The maximum a lender offers may be lower than you hoped, and can be capped as a multiple of your monthly income. If your plans exceed it, trim the scope or top up with your own cash rather than stretching for a second loan.
Getting personalised advice
Everyone’s finances are different, and this guide cannot tell you what is right for your situation. For decisions about how much to borrow, which product suits you, or how a loan fits your wider financial plan, speak to your bank directly or consult a licensed financial adviser. They can look at your income, existing debts, and goals and give advice tailored to you.
When you approach a lender, come prepared with your renovation quotation, proof of income, and a clear idea of your budget. Compare offers from more than one MAS-regulated bank, ask questions until you fully understand the terms, and take the time to read the agreement before signing. A renovation should be exciting, and choosing your financing calmly and carefully keeps it that way. Remember, this article is general information only and not financial, tax, or investment advice.
Explore more
Sound financing works best with a solid plan, so pair this with the practical questions to ask your interior designer before you sign a contract. Understanding the works you are paying for helps too, from our guide to hacking walls in HDB flats to waterproofing and wet works, so your budget reflects what your home genuinely needs.
Common Mistakes to Avoid
Even a well-priced renovation loan can cause regret if it is arranged carelessly. Most pitfalls are easy to sidestep once you know to look for them.
- Judging offers by the advertised rate alone. Always compare on the effective interest rate, which folds in fees and the repayment structure.
- Borrowing the maximum offered. Borrow the shortfall you actually need and no more.
- Forgetting the cost of moving in. Furniture, appliances, curtains and lighting add up, and a renovation loan generally will not cover them.
- Signing without reading the fine print. Late-payment charges, early-repayment fees and processing costs all matter, so ask the lender to spell them out.
- Stacking multiple loans. Look at your total monthly commitments, not each loan in isolation.
Gather two or three quotes, read the loan terms in full, and be honest about the monthly repayment you can sustain once furniture, bills and daily life are factored in.
Practical Steps Before You Apply
A little preparation makes the process smoother:
- Firm up your renovation scope and get a detailed contractor quotation.
- Work out how much you genuinely need to borrow, not the maximum you could get.
- Compare offers from more than one lender, looking at the full cost and not just the headline rate.
- Check the fine print on fees, tenure and repayment flexibility.
- Make sure the monthly repayment fits your budget with room to spare, alongside your home loan, utilities, insurance and daily expenses.
Keeping your renovation scope disciplined stops the loan from ballooning. Our guide to dealing with a renovation that goes over budget covers how to keep spending in check, and reviewing your renovation contract closely ensures the quote you borrow against matches the works you actually receive.
Further reading: How to Budget for Home Repairs Without a Renovation Loan